The Law Offices of Anidjar and Levine help Largo property owners document storm and weather damage, review policy terms, and address disputes over coverage, repair scope, or payment. Whether wind, hail, heavy rain, or a tornado damaged your home, we can help organize photographs, estimates, receipts, and claim communications. Our team can explain available options and pursue a fair resolution while you focus on safety and restoration. Learn more about our Largo Personal Injury Lawyer services. Below, we outline common claim issues and how legal guidance may help.
Main Takeaways
- A Largo storm-damage lawyer can review your policy and explain coverage, exclusions, deadlines, and claim requirements.
- Document roof, window, water, and belongings damage with dated photos, repair estimates, receipts, and weather records.
- Report the loss promptly, keep insurer communications, and take safe, reasonable steps to prevent further damage.
- A lawyer can help address disputes over storm causation, damage scope, repair costs, or a denied or underpaid claim.
- Compare any settlement offer with documented losses, and understand a release’s effect before signing.
How We Can Help With Your Largo Property Claim Storm & Weather Damage Injury Claim
When a storm damages your Largo property, we can help you pursue a claim and address disputes with your insurer. We’ll listen to your concerns, review the damage, and explain practical steps for seeking coverage. Our goal is to help you protect your home or business while reducing the burden of managing a difficult claim.
We can examine your policy’s terms, exclusions, and deadlines to clarify what coverage may apply. Careful Policy interpretation helps us identify questions that require answers and respond to an insurer’s position with relevant information. We can also organize photographs, repair estimates, receipts, and other records that support your request.
When repairs are needed, contractor coordination can help keep communication clear among you, your insurer, and qualified professionals. We’ll address delays, incomplete evaluations, or disagreements about repair scope through focused advocacy. Throughout the process, we’ll keep you informed, explain your options, and pursue a fair resolution so you can restore your property and keep serving your family, customers, or community.
Don’t Wait. Call Our Florida Personal Injury Lawyers Now!
Understanding Largo Property Claim Storm & Weather Damage Injury Cases
OUR CONSULTATIONSARE FREE
START YOUR FREE CASE REVIEW
Understanding a Largo storm damage claim starts with identifying the cause of the loss, the damage it caused, and the policy terms that may apply. We review the policy’s coverage, exclusions, deadlines, and duties so you can understand what your insurer must consider. We also help you connect the evidence of property damage to the amount you’re seeking and respond to requests for records or inspections.
A claim may become difficult when the insurer disputes the cause, scope, or value of the damage. We examine estimates, photographs, repair records, and other relevant documentation to identify gaps and explain your position. If the parties disagree about the loss amount, appraisal disputes may arise under the policy’s appraisal process. We can help you understand its requirements and assess whether it fits your situation.
When an insurer mishandles a claim, Insurer bad faith may become a concern. We evaluate the available facts and explain practical options, helping you pursue a fair resolution while protecting your ability to serve others.
Common Causes of Largo Property Claim Storm & Weather Damage
We often see Largo property claims arise from hurricane winds that tear roofing and siding, as well as hail that damages shingles, windows, and other exterior surfaces. Heavy rainfall can cause leaks and flooding, while tornadoes may produce sudden, concentrated structural damage. We’ll explain how these hazards affect property and what evidence can help support a claim.
Hurricane Winds
Hurricane winds can damage Largo homes and businesses by tearing off roofing, breaking windows, and driving rain into exposed areas. Windborne debris can puncture siding, shatter glass, or damage equipment, while roof uplift may loosen shingles and expose the structure to further water intrusion. Even when damage isn’t obvious from the ground, compromised materials can let moisture spread and lead to costly repairs.
After a storm, we encourage you to document visible damage, protect openings from additional rain when it’s safe, and keep receipts for temporary repairs. A qualified inspection can help identify affected areas and distinguish storm damage from preexisting wear. We can review your policy, organize supporting records, and communicate with the insurer about covered losses. By addressing concerns promptly, we help you pursue a fair claim and restore a safe property for everyone who relies on it.
Hail Damage
Hail can damage Largo properties even when a storm causes little visible disruption elsewhere. Hail formation occurs when strong updrafts carry water droplets into freezing parts of a storm cloud, where they collect layers of ice before falling. Hailstone sizes vary, and even small stones can crack shingles, dent metal roofing, break windows, or damage siding. Larger stones may puncture roofing materials and harm outdoor equipment. We should promptly inspect affected areas, including surfaces not readily visible from the ground, and document the damage with clear photographs. If you’re responsible for a home, business, or community property, timely attention can help protect occupants and preserve evidence for an insurance claim. We can review the policy, assess the reported damage, and help you understand available options.
Heavy Rainfall
When heavy rainfall overwhelms drainage systems or saturates the ground, water can enter Largo homes and businesses through roofs, windows, foundations, and low-lying areas. Changing rainfall patterns may bring intense downpours that exceed a property’s drainage capacity, causing water to pool around structures or back up through drains. Even when a storm passes quickly, runoff can damage flooring, drywall, insulation, electrical systems, and personal belongings. We encourage you to document affected areas promptly, take reasonable steps to prevent further damage, and keep receipts for emergency work. Photographs, repair estimates, and rainfall records can help clarify the extent and timing of your loss. If you’re helping a neighbor or managing a commercial property, prioritize safety and report damage to the insurer immediately. We can help you understand the claim process.
Tornado Damage
Tornadoes can cause sudden, concentrated damage to Largo properties through powerful winds and flying debris. They may tear off roofs, break windows, damage siding, and send branches or other objects into buildings. Even when a tornado does not strike directly, nearby winds can weaken structures and expose interiors to rain.
Tornado Formation often involves severe thunderstorms, changing wind speeds, and rotating air, though local conditions vary. After a storm, we can help you document visible damage and take reasonable steps to prevent further harm, such as covering openings when it is safe. Keep receipts and photographs, and report the loss promptly to your insurer.
Tornado Ratings describe estimated wind intensity based on observed damage; they don’t establish the full scope of your property loss. We can help you review the evidence and policy terms.
Legal Rights of Largo Property Claim Storm & Weather Damage Injury Victims
Storm and weather damage can leave Largo property owners facing costly repairs, disputed insurance claims, and uncertainty about their legal options. We can help you understand your policy rights and take informed steps to protect your home, finances, and family.
Florida law and your insurance contract may provide remedies when an insurer mishandles a valid claim.
- You can review the policy, document losses, and submit supporting records within required deadlines.
- You may challenge an inadequate payment or denial through your insurer’s appeal process.
- The Right to Appeal can help you seek a fair review, though deadlines and procedures matter.
- Bad Faith Claims may apply when an insurer fails to meet legal duties; evidence and legal guidance are vital.
We can explain your options, communicate with the insurer, and help you pursue the benefits your policy covers. By asserting your rights, you can restore your property safely and maintain stability for those who depend on you. A lawyer can assess your circumstances and clarify possible next steps.
Why Do Largo Property Claim Storm & Weather Damage Injuries Happen?
Understanding the causes of storm and weather damage can help Largo property owners identify risks and document losses for an insurance claim. Storm-related injuries and property losses often begin with heavy rain, high winds, lightning, or flooding that overwhelms a building’s defenses. Wind can lift shingles, break windows, and send debris into structures, while water may enter through damaged roofs, poorly sealed openings, or overwhelmed drainage systems.
Building code vulnerabilities can increase these risks. Older construction, inadequate roof connections, and neglected maintenance may leave a property less able to withstand severe weather. Climate change patterns can also contribute to heavier rainfall, stronger storms, and changing flood risks, placing added pressure on homes and community facilities.
When damage affects a residence or a public facility, the consequences can extend beyond repair costs. We can help you understand how weather conditions, building features, and maintenance may have contributed to a loss. Recognizing these factors helps us assess an insurance claim more clearly.
What Should You Do After a Largo Property Claim Storm & Weather Damage Injury?
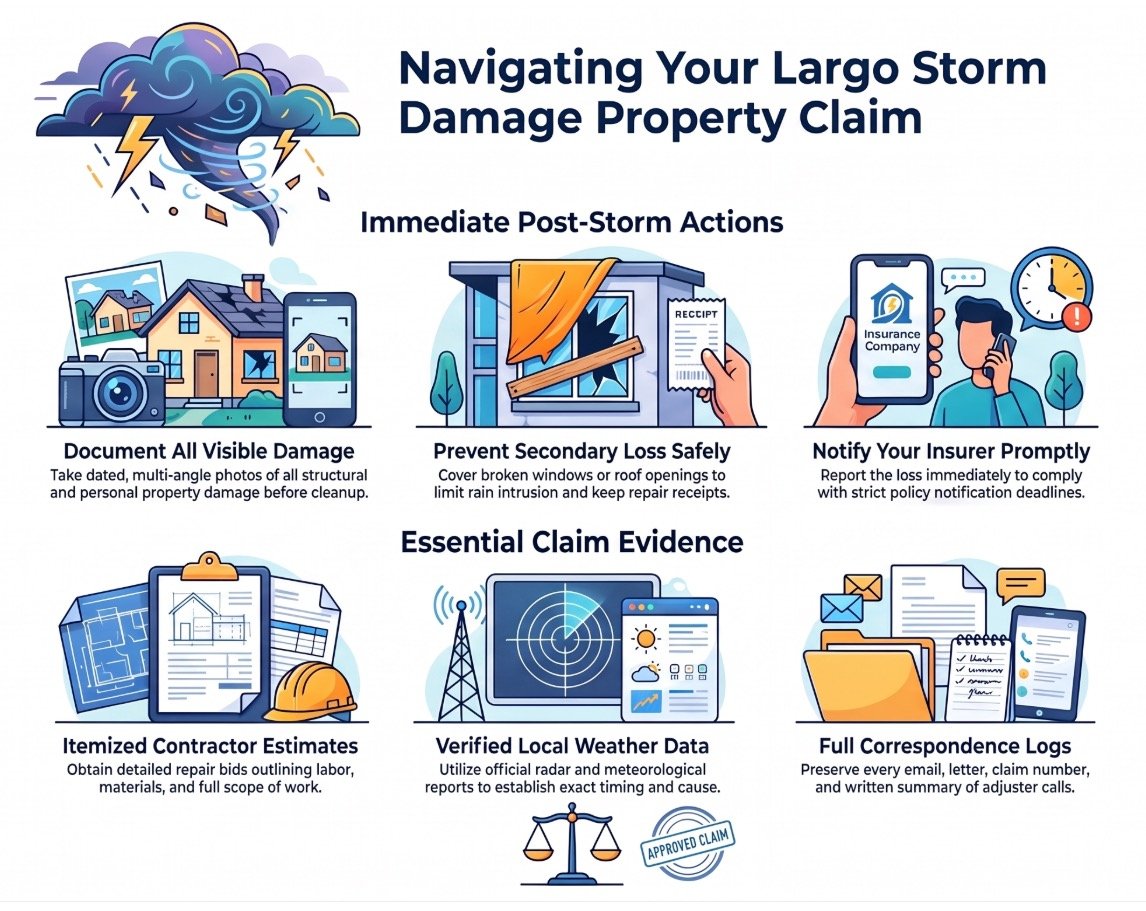
After storm or weather damage, we should document the affected areas with clear photographs and keep records of any related expenses. We can take reasonable steps to protect the property from further harm while preserving evidence of the damage. Then contact your insurer promptly and provide accurate information about the loss.
Document the Damage
To protect your Largo property claim, document the storm damage as soon as it’s safe. Photograph and record each affected area before cleanup, capturing wide views and close-ups that show the extent of the damage. Include damaged belongings, structural concerns, and visible water intrusion. Note the date, time, and location of each image, and keep original files.
Create an Inventory checklist listing damaged or missing items, their approximate age, purchase price, and replacement cost. Save receipts, repair estimates, inspection reports, and insurer communications in one organized file. If you need temporary relocation, keep lodging receipts and document why you couldn’t safely stay at home. We can help you present clear, consistent evidence so your insurer can assess the loss accurately and you can focus on supporting your household and community.
Protect Your Property
After you document the damage, take reasonable steps to prevent further loss without putting yourself at risk. If conditions remain dangerous, wait for qualified professionals rather than entering a damaged structure. When it’s safe, cover broken windows or roof openings with sturdy materials to limit rain and debris. Secure outdoor furniture and loose items that could become hazards in another storm. If your garage door is damaged, avoid operating it until you’ve checked for instability; reinforce garage doors only when you can do so safely. Move undamaged belongings away from wet areas, and use buckets or towels to contain minor leaks. Keep children, neighbors, and pets clear of exposed wires, standing water, and unstable debris. These practical steps can protect people and property while preserving the damaged area for later assessment.
Contact Your Insurer
With immediate safety measures in place, contact your insurer promptly to report the storm damage and ask how to proceed with your Largo property claim. We can help the claims process move efficiently by providing the date of the event, a clear description of affected areas, and any available photographs or receipts. Review your policy for Policy notification deadlines, since late notice may complicate coverage. Ask what temporary repairs you may make to prevent further damage, and keep receipts for reasonable expenses. Request claim confirmation numbers and record the representative’s name, the date, and the instructions provided. We should answer questions accurately, avoid guessing about the cause or extent of damage, and follow up in writing when possible. Clear communication helps protect your interests and supports a fair review for everyone affected.
Don’t Wait. Call Our Florida Personal Injury Lawyers Now!
Critical Evidence in a Largo Property Claim Storm & Weather Damage Injury Case
Strong evidence can help us show how a storm affected your property and support your claim. We’ll focus on records that document the damage, repair costs, and your insurer’s response.
Keep these essential materials organized:
- Clear photos of storm damage, taken as soon as it’s safe
- Weather reports confirming conditions on the date of loss
- Repair estimates detailing necessary work and costs
- Claim correspondence, including letters, emails, and insurer decisions
Storm Damage Photos
How clearly can photographs show what a storm damaged and when? Clear, timely images can help us document a property’s condition and support a fair claim. Photograph each affected area before cleanup or repairs, when it’s safe to do so. Take wide shots showing the location, then close-ups capturing specific damage, such as broken roofing, water stains, or damaged belongings. Include multiple angles and place an object nearby for scale when useful. Keep original files because Photo metadata may record the date, time, and device used. Don’t edit or add markings to originals; save annotated copies separately. Create image backups in secure locations, and preserve receipts and repair records alongside the photographs. We can help organize this evidence so insurers and others can assess the loss accurately.
Weather Reports
Weather reports can help establish the conditions that caused damage to your Largo property and when the storm occurred. We can compare official records with the timeline you provide, including when you first noticed damage and any changes afterward. This evidence may clarify whether wind, hail, heavy rain, or another weather event affected your home or business. Radar interpretation can show a storm’s path, intensity, and proximity to your property, while station data may document nearby conditions. We’ll also consider forecast accuracy carefully: a forecast describes expected conditions, not necessarily what occurred at your location. By reviewing reliable reports alongside your photographs and account, we can present a clearer, evidence-based claim. This careful work supports fair treatment for you and helps us advocate responsibly for the community we serve.
Repair Estimates
When a storm damages your Largo property, a detailed repair estimate can help show the scope and cost of the necessary work. We can use a clear, itemized estimate to connect visible damage to the repairs needed to safely restore your home or business. Contractor bids provide useful comparisons, especially when they describe labor, materials, and the work each task requires. We should also review material pricing, since local availability and changing costs can affect a reasonable repair budget. Photographs, measurements, and inspection findings can support the estimate and help identify damage that isn’t immediately apparent. Keep copies of each version and note who prepared it and when. By organizing these records, we can present a reliable account of the property’s needs and support a fair assessment of storm-related losses.
Claim Correspondence
Along with repair estimates, claim correspondence can provide a clear record of how you reported storm damage and how the insurer responded. We can review emails, letters, claim forms, and messages to identify important dates, requests, and explanations. Keep each communication in its original format, including attachments and delivery details, so the record shows what was sent and received. Effective Email organization helps us trace the claim’s progress and compare the insurer’s statements with inspection findings and policy requirements. Preserve letters by saving paper letters, envelopes, and copies of anything you send. Avoid deleting messages or relying only on brief notes about conversations; instead, document calls promptly with dates, names, and summaries. When we organize this evidence carefully, we can help you present a clear, accurate account and support a fair review of your claim.
Long-Term Effects of Largo Property Claim Storm & Weather Damage Injuries
Storm and weather-related injuries may cause chronic pain that continues long after the initial incident. We’ll also consider lasting mobility issues that can limit your ability to work or manage daily tasks. Ongoing emotional distress may affect your well-being, and we can explain how it factors into a property injury claim.
Chronic Pain
Chronic pain can persist long after storm-related injuries from a Largo property claim, affecting mobility, sleep, and the ability to work. When you’re accustomed to caring for family, coworkers, or neighbors, ongoing pain may also limit how reliably you can support them. We encourage you to seek medical guidance and describe your symptoms consistently, including when they worsen and which activities increase discomfort. Effective Chronic Pain Management may involve treatment, prescribed medication, counseling, or other clinician-recommended strategies tailored to your condition. Keep records of appointments, expenses, missed work, and changes in daily responsibilities. Tracking Pain Flare Triggers, such as prolonged activity or disrupted sleep, can help your care team adjust treatment and document the injury’s continuing effects. If an insurer questions your claim, organized medical records can help show how pain affects your life.
Lasting Mobility Issues
When storm-related injuries from a Largo property claim limit your movement, everyday tasks such as walking, climbing stairs, or standing for extended periods may become difficult. These limitations can affect your ability to work, care for family, and serve others in your community. We can help you document how reduced mobility changes your daily routine and identify practical needs, including home modifications and Assistive device adaptations. A cane, walker, or wheelchair may support safer movement, while accessible transportation can help you reach medical appointments, work, and community commitments. Keep records of treatment, mobility assessments, equipment costs, and assistance you require. These details may help show the lasting impact of your injuries when pursuing a property claim. We can review the evidence you have and explain your options for seeking compensation for related losses.
Ongoing Emotional Distress
After a storm-related injury on a Largo property, emotional distress may continue long after physical wounds begin to recover. You may experience anxiety, low mood, or fear of returning to the location where you were hurt. Sleep disruption can make daily responsibilities harder and affect your ability to care for family, coworkers, and others who depend on you. We encourage you to discuss persistent symptoms with a qualified health professional and follow a treatment plan. Anxiety management may include counseling, practical coping strategies, or other support recommended by your provider. Keep records of symptoms, appointments, and related expenses, since this information can help explain how the injury affects your life. If another party’s negligence contributed to the hazardous conditions, we can help you understand your options for seeking compensation for documented losses.
Proving Liability in Largo Property Claim Storm & Weather Damage Injury Cases
Proving liability in a Largo storm or weather damage claim requires more than showing property damage; we must establish that the responsible party failed to meet a legal duty and that this failure caused the loss. We begin by identifying who controlled the property and what steps a reasonable owner or manager should have taken before and after severe weather. The Duty of care may include inspecting roofs, clearing drains, securing hazardous areas, and addressing known weaknesses. Negligence standards require us to link a specific failure to the damage or injury, not the storm alone.
We gather records, photographs, maintenance logs, weather reports, and witness accounts to build that connection. These details can show whether the danger was foreseeable and whether timely action could have reduced harm. We also consider expert assessments when structural conditions or repair practices require technical explanation. By carefully documenting what happened, we can help you pursue accountability while protecting those affected.
Dealing With Insurance Companies After a Largo Property Claim Storm & Weather Damage Injury
Insurance companies may question the cause, scope, or value of storm damage, so we should approach every discussion with clear documentation and care. Keep photographs, repair estimates, receipts, and relevant correspondence organized so you can support your account of the loss. Prompt, factual communication with your adjuster helps reduce misunderstandings; answer questions accurately, and avoid guessing when you need time to verify a detail. If an insurer requests a recorded statement or broad authorization, we can help you understand its purpose and consider the potential consequences before responding.
During settlement negotiations, compare any offer with documented damage, necessary repairs, and other covered losses. Don’t accept a payment simply because it arrives quickly, and don’t sign a release without understanding what rights it may affect. We can communicate firmly and professionally while recognizing that adjusters represent the insurer’s interests. When questions remain, seek clarification in writing and preserve copies of every exchange. Careful, respectful advocacy can help you pursue fair treatment while keeping your focus on those who depend on you.
What to Expect During a Largo Property Claim Storm & Weather Damage Injury Claim Process
We’ll start by evaluating the storm or weather damage and reviewing your policy to identify applicable coverage. We’ll also help you gather clear evidence and documentation to support your claim. From there, we’ll explain the resolution steps and keep you informed as the claim progresses.
Initial Property Assessment
After a storm damages your Largo property, an initial assessment documents the home’s condition and identifies urgent repairs. We’ll begin with a Preliminary Walkthrough, noting visible damage to roofing, windows, walls, flooring, and personal belongings. We’ll photograph affected areas, record dates, and preserve damaged materials when safe, creating a clear account of what happened. Our Structural Inspection will look for concerns such as weakened supports, shifting walls, or water intrusion that may threaten safety. We’ll also identify hazards that require prompt attention, including exposed wiring or unstable debris, and recommend qualified professionals when needed. You can help by sharing what you observed and keeping receipts for emergency work. Together, we’ll organize the initial findings so your property’s condition is accurately documented and urgent needs get timely attention.
Policy and Coverage Review
Once we’ve documented the damage, we’ll review your policy to identify the coverage that may apply to your Largo storm claim. We’ll explain relevant limits, covered causes of loss, and duties the policy requires you to meet. Because policy language can be difficult to interpret, we’ll clarify how its terms may affect your recovery and answer your questions directly.
We’ll also examine Coverage exclusions that could limit or prevent payment, including provisions addressing flooding, wind, or delayed reporting. If the insurer relies on an exclusion, we’ll assess whether its interpretation fits the policy and circumstances. We’ll explain deductible calculations and show how the deductible may reduce any payment.
Our goal is to help you understand your options so you can make informed decisions and protect your household’s stability. We’ll discuss potential disputes and next steps before you respond to the insurer.
Evidence and Documentation
Strong evidence can help establish how a storm damaged your Largo property and support your claim amount. We can help you document affected areas before repairs alter the scene. Take dated photographs and videos of roof damage, leaks, damaged belongings, and surrounding conditions. When practical, keep damaged materials, and don’t discard items until you’ve recorded their condition. This Evidence preservation can help connect the loss to the storm and show its extent.
Save receipts for temporary repairs, lodging, and other reasonable expenses. Keep contractor records, including inspection reports, estimates, invoices, and written communications. Note when you discovered damage and whom you contacted. We can organize these materials into a clear record that supports your account and helps others understand the property’s condition without relying solely on memory.
Claim Resolution Steps
With your evidence organized, we can guide you through the steps of a Largo storm damage property claim. We’ll review your policy, identify applicable deadlines, and submit a complete claim to your insurer. After inspection, we’ll compare the insurer’s estimate with your documented repair costs and explain any differences. During Claim negotiation, we’ll present supporting records, address disputed items, and seek a fair resolution while keeping you informed. If the insurer’s valuation remains contested, we can explain the appraisal process and help you assess whether it fits your situation. We’ll also review any settlement offer before you decide whether to accept it. Throughout the process, we’ll protect your interests, answer your questions, and help you pursue the funds you need to restore your property and keep a safe place for those who depend on you.
Compensation for Largo Property Claim Storm & Weather Damage Injury Damages
When a storm damages your Largo property, you may seek compensation for covered losses, including repairs, damaged belongings, and certain additional expenses. We can help you review your policy, document damage, and present a clear claim so your insurer can assess each covered item. Keep photographs, receipts, repair estimates, and communications organized; organized records help establish the scope and value of your loss.
Personal property valuation may depend on the item’s age, condition, and whether your policy pays actual cash value or replacement cost. We’ll help you understand the applicable terms and provide supporting evidence for belongings affected by wind, rain, or flooding, subject to policy exclusions and limits.
If damage makes your home temporarily unlivable, Additional living expenses may cover reasonable costs such as lodging and meals, when your policy provides that benefit. Save receipts and confirm expense requirements with your insurer before incurring substantial costs. We can help you pursue benefits fairly, while keeping your claim focused on documented, policy-covered property losses.
Don’t Wait. Call Our Florida Personal Injury Lawyers Now!
Economic vs Non-Economic Damages in Largo Property Claim Storm & Weather Damage Cases
We distinguish economic losses, such as repair costs and temporary housing expenses, from non-economic harm, including disruption and loss of use. You’ll need clear evidence to show how the storm affected your property and daily life. We can help you document both types of damages to support your claim.
Economic Losses
Economic losses in a Largo storm or weather damage claim are measurable financial costs from property damage, such as repair expenses, temporary housing, and lost rental income. We can help you identify each expense and connect it to the covered damage. Keep invoices, receipts, estimates, and payment records so we can document your claim accurately. If the damage makes a rental property unusable, you may recover lost rental income when supported by lease terms and reliable financial records. A business owner may also face business interruption losses, including reduced revenue and necessary operating costs during repairs. We’ll review the policy, assess the evidence, and present a clear accounting of your financial harm. Careful documentation helps us pursue the compensation you need to restore your property and continue serving tenants, customers, or the community.
Non-Economic Harm
Storm damage can cause stress and disruption beyond the measurable costs of repairs, temporary housing, or lost income. These effects may qualify as non-economic harm, which differs from economic losses tied to specific financial expenses. You may experience emotional anguish when damage leaves your home unsafe, disrupts family routines, or creates uncertainty about recovery. You may also enjoy less of your home when storm-related conditions limit privacy, comfort, or your ability to welcome others. We recognize that these impacts matter, especially when you’re working to care for your family or support others who depend on you. Florida law and the facts of a claim determine whether non-economic harm is recoverable. We can explain how these damages differ from repair costs and other measurable losses, and discuss the options available for your situation.
Documenting Damages
When storm damage affects your Largo property, clear records can help show both the financial losses and the personal harm you’ve experienced. We can help you distinguish economic damages, such as repair costs, cleanup, and Temporary housing, from non-economic harm, including stress and disruption to daily life. Save receipts, invoices, contractor estimates, and insurer correspondence, and photograph damage before making non-emergency repairs. Create an inventory of damaged Personal belongings, noting each item’s age, condition, and replacement cost. Keep records of extra expenses and explain how the loss has affected your household’s routines and well-being. These details help present a complete, credible account of your claim. By organizing evidence promptly and accurately, we can support a fair review and help guarantee your losses—and the people affected—receive careful consideration.
When a Largo Property Claim Storm & Weather Damage Injury Case Goes to Trial vs. Settlement
A Largo storm and weather damage claim may settle through negotiation, but a trial may be necessary if the insurer disputes coverage, the extent of the damage, or the value of your losses. We’ll review your records, repair estimates, and expert assessments to identify the evidence that supports your position. A settlement can provide a more predictable resolution and avoid the time and uncertainty of court. However, we won’t recommend accepting an offer that fails to account for documented losses or needed repairs.
Settlement Negotiation Timing matters. We’ll consider whether further evidence, inspections, or discussions could improve the insurer’s offer before deciding how to proceed. If negotiations stall, we can prepare your case for trial and explain the process, likely challenges, and available options. Our Jury Trial Strategy will focus on presenting clear evidence and credible testimony about the damage and its impact on your property. We’ll help you weigh each path carefully, so you can make informed decisions while protecting the resources your household or organization needs to serve others.
Florida Laws That May Affect Your Largo Property Claim Storm & Weather Damage Case
Florida law sets deadlines and requirements that can affect how we pursue your Largo property claim for storm or weather damage. We’ll review your policy, document your losses, and help you meet each applicable obligation while protecting your household’s and community’s interests.
Florida claim deadlines matter. We’ll review your policy, document your Largo storm damage, and help protect your household’s interests.
- Prompt notice: Your policy may require timely notice of damage. We’ll help you report the loss accurately and preserve supporting records.
- Proof of loss: Insurers may request a signed statement or other documentation. We’ll organize estimates, photographs, receipts, and repair records.
- Florida matching law: Florida law may affect whether an insurer must replace undamaged materials to achieve a reasonably uniform appearance. We’ll assess how this applies to your repairs.
- Appraisal deadlines: Policies can set procedures and deadlines for invoking appraisal when you and the insurer disagree about the amount of loss. We’ll review those terms before you act.
Requirements vary by policy and claim circumstances. We’ll explain the rules relevant to your case and help you make informed decisions as you seek a fair resolution.
The Statute of Limitations for Largo Property Claim Storm & Weather Damage Injury Cases
The deadline to file a storm or weather damage lawsuit depends on the type of claim and the date the loss occurred. Florida law sets different limits for property damage, personal injury, and claims involving government entities. Missing the applicable deadline may prevent you from recovering compensation, even when the damage is well documented.
Filing deadlines can also depend on when the damage became apparent and whether an insurance policy imposes separate notice or proof-of-loss requirements. These contractual requirements may arrive much sooner than a lawsuit deadline, so we shouldn’t treat them as interchangeable. Review your policy and preserve records of the storm, resulting damage, repair costs, and communications with your insurer.
Some limitations exceptions may pause or extend a deadline in specific circumstances, but they’re narrow and fact-dependent. The date of loss, the parties involved, and the claim’s legal basis can all matter. Acting promptly helps protect your rights and supports a fair resolution, especially when others depend on your property’s safety and stability.
How a Largo Property Claim Storm & Weather Damage Lawyer Can Help You
Meeting a filing deadline is only one part of protecting a storm damage claim; we can also help you assess the loss, interpret policy requirements, and organize evidence. Our work can give you a clearer path forward while you focus on your family, employees, or neighbors who depend on you. We review the policy, damage records, repair estimates, and insurer communications to identify disputed issues and support a well-documented claim.
- We compare the reported damage with policy terms and exclusions.
- We organize photographs, invoices, inspection reports, and repair documentation.
- We communicate with the insurer and respond to requests for information.
- We assess whether a claim denial appeal may be appropriate.
An Attorney case evaluation can clarify your claim’s strengths and challenges, explain your options, and help you understand the next steps. We can also identify evidence gaps and recommend practical ways to address them. We tailor our guidance to your circumstances, with careful attention to accurate records and fair treatment.
When to Contact a Largo Property Claim Storm & Weather Damage Lawyer
Contact a Largo property claim storm and weather damage lawyer as soon as an insurer disputes your loss, delays its decision, or requests information you’re unsure how to provide. Early guidance can help us identify the issue and respond with clear, organized records while preserving your ability to pursue the claim.
You should also seek advice if the insurer offers less than the documented repair cost, attributes damage to an excluded cause, or asks you to sign a release. We can review the policy language, estimates, photographs, and correspondence to clarify what remains unresolved. A Policy deadline review can help us identify notice, proof-of-loss, and appeal dates so you don’t miss important requirements while assisting your family, tenants, or neighbors.
If the coverage decision seems inconsistent with the policy or available evidence, request an independent coverage opinion. Contact us promptly after discovering storm damage, especially when repairs are urgent, so we can help you understand your options and next steps.
Why You Need an Experienced Largo Property Claim Storm & Weather Damage Lawyer
When a storm damages your Largo property, an experienced lawyer can help us identify coverage issues, document the loss, and respond effectively to the insurer. We can review your policy, explain what protection applies, and identify Policy exclusions that may affect your claim. This guidance helps you make informed decisions while preserving resources needed to restore your home or business.
Insurers may question the cause, scope, or value of damage. We can organize repair estimates, photographs, inspection findings, and other evidence to support your account. If the insurer delays, underpays, or disputes covered damage, we can challenge its position and pursue a fair resolution. Our knowledge of appraisal disputes and claim procedures can help prevent avoidable setbacks and clarify available options.
How to Choose the Right Largo Property Claim Storm & Weather Damage Lawyer for Your Case
Choosing the right Largo property claim storm and weather damage lawyer requires more than comparing fees or promises. We should assess whether a lawyer regularly handles property insurance disputes involving wind, hail, flooding, or other storm damage. Ask how the firm investigates losses, documents repairs, and responds when an insurer delays or undervalues a claim. Clear answers can help us understand whether the lawyer’s approach fits our circumstances.
During Attorney Selection, we can review relevant experience, communication practices, and the lawyer’s willingness to explain risks and next steps. We should also ask who will manage our case and how often we’ll receive updates. A dependable professional listens carefully and treats our concerns with respect, especially when a claim affects our family or community.
Before signing, discuss Fee Structures and any costs we may owe. Request a written agreement that explains fees, expenses, and payment responsibilities. Comparing these details helps us make an informed choice and focus on pursuing a fair resolution.
About The Law Offices of Anidjar & Levine
The Law Offices of Anidjar & Levine represents clients in a range of legal matters, including property insurance claim disputes. We work to help Largo property owners understand their options after storms or other weather events damage their homes or businesses. When an insurer delays, underpays, or denies a claim, we can review the circumstances and explain potential next steps.
Our firm’s history reflects a commitment to representing people facing difficult legal challenges. We approach each matter with attention to the client’s concerns, clear communication, and careful preparation. Property damage can disrupt a family’s stability or a business’s ability to serve its community, so we take those practical effects seriously.
Attorney recognition may offer useful context when you evaluate legal counsel, but it should not replace a direct discussion of your needs. We encourage you to ask about relevant experience, case strategy, and communication. We’ll explain how we may assist and what to expect throughout the process.
Frequently Asked Questions
Does Homeowners Insurance Cover Hurricane Damage to My Largo Property?
Yes, homeowners insurance may cover hurricane damage to your Largo property, but coverage depends on your policy and the source of the loss. We recommend checking whether your policy includes windstorm coverage and reviewing its hurricane deductible, which may be separate from your standard deductible. Flood damage is generally excluded and may require separate insurance. We can help you examine policy terms, document damage, and pursue covered benefits so you can restore your property and support those who depend on you.
Are Flood Losses Covered by a Standard Homeowners Insurance Policy?
No, standard homeowners insurance generally doesn’t cover flood losses caused by rising water or storm surge. We recommend reviewing your policy’s Flood insurance exclusions and considering separate flood insurance, especially if your property faces water risks. Coverage may depend on the flood’s cause and your policy terms. We can also help you check whether sewer backup coverage applies, since backup losses may be covered only through an endorsement or separate limit.
Can I File a Claim for Damage Caused by a Fallen Tree?
Yes, you can file a claim for property damage caused by a fallen tree, but coverage depends on your policy and what caused the tree to fall. Homeowners insurance often covers damage from storms or other covered events, but exclusions may apply for neglect or flooding. We can help you review your policy, document the damage, and communicate clearly with your insurer so you can pursue a fair decision and protect your household.
What if My Insurer Says My Roof Damage Resulted From Wear and Tear?
If your insurer attributes roof damage to wear and tear, we can help you review the decision and identify evidence that supports your claim. Ask for the specific policy language and inspection findings, then document the damage with dated photographs, repair records, and a qualified contractor’s assessment. Roof maintenance records may clarify prior conditions, while policy exclusions can limit coverage. We can help you challenge an unsupported denial and meet appeal deadlines.
Can I Hire a Public Adjuster to Assess My Storm Damage?
Yes, you can hire a public adjuster to assess storm damage and help prepare or negotiate your insurance claim. We recommend confirming the adjuster’s licensing requirements with your state regulator and reviewing the written contract before you sign. Ask about Public adjuster fee structures, including how fees are calculated, when payment is due, and whether any limits apply. We can also help you compare the adjuster’s findings with your insurer’s assessment and protect your interests.
—————————
Storm damage can leave you facing costly repairs, disputed coverage, and uncertainty about what to do next. We can review your policy, document the damage, communicate with the insurer, and pursue the benefits you’re entitled to under your coverage. If your property claim has been delayed, underpaid, or denied, contact The Law Offices of Anidjar and Levine to discuss your options. We’ll explain the next steps and work to protect your interests throughout the claims process. Learn more about a Largo Personal Injury Lawyer.