The Law Offices of Anidjar and Levine can help Immokalee property owners understand storm and weather damage coverage disputes, organize evidence, and communicate with an insurer. Claims may involve disagreements about the cause, extent, or repair cost of damage, and outcomes depend on policy language and supporting records. Dated photographs, inspection findings, estimates, receipts, and weather reports may help document a loss. Legal counsel can explain deadlines and dispute options. Learn more about the firm’s services as an Immokalee Personal Injury Lawyer.
Main Takeaways
- An Immokalee property claim lawyer can review your policy, storm damage evidence, and the insurer’s coverage decision.
- Document damage with dated photographs, inspection findings, repair estimates, invoices, and relevant weather records.
- Ask the insurer for written explanations of claim denials, delays, exclusions, or limits.
- Policy terms determine coverage, deadlines, deductibles, repair requirements, and whether appraisal may address disputes over repair costs.
- Preserve claim communications and emergency repair records; consult an attorney about dispute options and applicable deadlines.
How We Can Help With Your Immokalee Property Claim Storm & Weather Damage Injury Claim
Storms and severe weather can damage an Immokalee property, disrupt daily life, and create disputes over repair costs and scope. A property claim lawyer can help owners address these challenges with careful preparation and clear communication. The lawyer reviews available records, organizes photographs, repair estimates, receipts, and relevant correspondence, then identifies information that may support the claim. This Claim preparation helps present the property damage and requested compensation in a structured, consistent manner.
Policy interpretation is another important service. Insurance provisions can be difficult to apply, particularly when coverage limits, exclusions, deadlines, or repair requirements affect a claim. Counsel can explain relevant terms, assess the insurer’s stated position, and help the owner understand available options. The lawyer may also communicate with the insurance company, respond to requests, and seek clarification when information is incomplete. By providing attentive guidance, counsel helps property owners pursue a fair review while keeping the process organized and focused on documented damage and policy obligations.
Understanding Immokalee Property Claim Storm & Weather Damage Injury Cases
When severe weather damages a home or business in Immokalee, a property claim may involve disputes about the cause, extent, and repair cost of the damage. These cases generally concern whether an insurance policy covers the reported loss and whether the insurer has assessed the evidence fairly. Policy interpretation can determine how specific terms apply to the property, the claimed damage, and the requested benefits. Coverage exclusions may also affect the outcome, but their application depends on the policy language and the facts documented in the claim.
OUR CONSULTATIONSARE FREE
START YOUR FREE CASE REVIEW
A careful review may include the policy, inspection findings, photographs, repair estimates, and communications with the insurer. Clear records help establish the property’s condition and explain the scope of necessary work. When disagreements arise, a property owner may seek legal guidance to understand available options and deadlines. Resolving a claim accurately can help owners restore safe, functional spaces for families, employees, tenants, and others who depend on the property. Each case turns on its own evidence and policy terms.
Don’t Wait. Call Our Florida Personal Injury Lawyers Now!
Common Causes of Immokalee Property Claim Storm & Weather Damage
Storm and weather damage in Immokalee commonly results from hurricane winds that tear roofing, break windows, or damage exterior structures. Hail, flooding, and storm surge can also harm buildings and personal property, with the extent of loss depending on the storm’s severity and the property’s location. Lightning strikes may cause fires or damage electrical systems, creating additional losses that can require careful assessment.
Hurricane Winds
Hurricane winds can damage Immokalee properties by tearing off roofing materials, breaking windows, and letting rain into the building. Roof uplift occurs when strong gusts create pressure beneath roof edges or coverings, loosening shingles, tiles, and structural connections. Once the protective surface is compromised, wind-driven rain may damage ceilings, insulation, electrical systems, and personal belongings. Windborne debris, including branches and unsecured objects, can strike siding, doors, and windows, creating openings that expose interiors to further weather damage. The extent of loss may depend on wind speed, building condition, and the quality of prior repairs. Property owners can help protect occupants and support a clear claim by documenting visible damage, taking reasonable steps to prevent additional loss, and preserving repair records. A thorough assessment can identify covered damage and necessary restoration.
Hail Damage
Hail can damage Immokalee properties by denting metal surfaces, cracking roof tiles, and bruising shingles in ways that may not be immediately visible. Damage severity often depends on hail size, wind direction, and storm duration. Roof shingle damage may include granule loss, fractures, or weakened areas that allow later deterioration. Even when a roof appears intact from the ground, a careful inspection can reveal defects that affect its service life and the property’s protection.
Documenting hail impact patterns across roofing, siding, gutters, vents, and other exterior features can help establish the storm’s effects. Photographs, inspection notes, and repair estimates provide useful records for evaluating a property claim. Timely assessment helps owners identify necessary repairs and preserve accurate information for insurers and others involved in resolving the claim.
Flooding and Storm Surge
When heavy rainfall or coastal storm surge overwhelms drainage systems, floodwater can enter Immokalee properties and damage flooring, walls, electrical systems, and personal belongings. Although Immokalee is inland, intense storms can bring prolonged rainfall, while water pushed inland may contribute to Coastal inundation in vulnerable areas. Flooding can also weaken foundations, contaminate interiors, and create conditions that require extensive cleanup and repairs. Property owners should document visible damage, keep receipts, and take reasonable steps to limit further loss when it is safe. Photographs, repair estimates, and timely notice to the insurer can help clarify the scope and cause of damage. Surge barriers and drainage improvements may reduce exposure, but they cannot eliminate every risk. Carefully reviewing policy terms can help determine whether flood-related losses are covered.
Lightning Strikes
Beyond flood damage, lightning strikes can cause sudden and costly losses to Immokalee properties. A direct strike may ignite roofing, attic materials, trees, or nearby structures, creating a serious Lightning fire risk even when flames are not immediately visible. Heat and impact can also damage siding, windows, and other exterior components. Lightning may travel through wiring, plumbing, or connected equipment, causing electrical surge damage to appliances, security systems, and vital building systems. Such losses can affect homes, farms, and businesses that support local residents and services. After a storm, property owners may need to document visible damage, arrange qualified inspections, and preserve receipts for emergency work. A careful assessment can identify hidden hazards and help establish the scope of a property insurance claim for appropriate review and resolution.
Legal Rights of Immokalee Property Claim Storm & Weather Damage Injury Victims
Storm and severe weather can leave Immokalee property owners facing structural damage, lost belongings, and disputes over insurance coverage. Florida policyholders have rights under their insurance contracts and applicable law, including the right to receive a timely, fair review of covered losses.
Understanding those rights can help owners protect household stability and support others who depend on them.
- Policyholders may request a written explanation when an insurer denies, limits, or delays a claim. Policy exclusions must be applied according to the policy language and relevant facts, not assumed to bar every weather-related loss.
- Owners may document damage, submit supporting records, and seek clarification about coverage decisions. Accurate records can help establish the scope and value of a claim.
- When disagreements concern the amount of loss, appraisal rights may be available under the policy. An attorney can explain deadlines, dispute options, and potential remedies, allowing property owners to make informed decisions while meeting responsibilities to family and community.
Why Do Immokalee Property Claims for Storm & Weather Damage Happen?
Why do storm and severe weather injuries occur during property damage events in Immokalee? Strong winds, heavy rain, lightning, and flooding can turn homes, businesses, and shared spaces into hazardous environments. Residents, visitors, workers, and volunteers may be exposed while buildings sustain damage or vital services are disrupted.
Roof collapse can occur when wind pressure, weakened supports, or water accumulation compromise a structure. Falling debris, including shingles, branches, broken glass, and damaged building materials, may injure people nearby. Floodwater can conceal sharp objects, open drains, unstable surfaces, or electrical hazards, while lightning and downed power lines create additional risks. Poor visibility and sudden weather changes can make these dangers harder to spot.
Some injuries arise from unsafe property conditions that existed before the storm, while others result from inadequate maintenance or vulnerable construction. The effects may include cuts, fractures, burns, head injuries, or respiratory problems. Understanding these causes helps communities recognize how severe weather can endanger people who live, work, or provide assistance in Immokalee.
What Should You Do After an Immokalee Property Claim Storm & Weather Damage Injury?
After a storm-related injury, the affected person should seek prompt medical attention and follow the recommended treatment. Photographs, repair estimates, and records of damaged belongings can help document the property loss. The policyholder should then contact the insurer promptly to report the damage and ask about the claims process.
Seek Medical Attention
Anyone injured by storm or weather damage at an Immokalee property should seek prompt medical attention, even if symptoms initially appear minor. Urgent evaluation can identify injuries that may not be immediately apparent, including head trauma, fractures, or breathing problems caused by dust and debris. Emergency services should be contacted for severe pain, difficulty breathing, confusion, heavy bleeding, or loss of consciousness. For less urgent concerns, a qualified healthcare provider can assess the injury and recommend appropriate care. Following medical instructions and attending scheduled appointments can support recovery and help prevent complications. Symptom monitoring is also important because some conditions develop or worsen over time. The injured person should report new or changing symptoms to a medical professional without delay. Timely care protects health and supports responsible recovery after a property-related injury.
Document the Damage
Promptly documenting storm and weather damage can preserve important evidence for an Immokalee property claim. Once the area is safe, the property owner should photograph and video each affected room, exterior surface, and damaged item before cleanup or repairs begin. Images should show both close details and the wider setting, with dates recorded when possible. A written account can describe when the owner discovered the damage, the observed conditions, and any changes over time. A Contents inventory should list damaged belongings, their approximate age, purchase details, and estimated value; receipts or other supporting records can strengthen the account. The owner should also keep relevant estimates, repair invoices, and expenses for temporary protection. Careful document retention, including secure copies of photographs and written records, helps maintain an organized, accurate record for later review and supports those assisting with recovery.
Contact Your Insurer
Once the property is safe and the owner has documented the damage, they should promptly notify the insurer and report the storm-related loss. The initial report should include the event date, a concise description of the damage, and any immediate steps taken to prevent further harm. The owner should request Policy confirmation, including applicable coverage, deductibles, deadlines, and required forms. A representative’s instructions should be recorded, along with the report date and any assigned claim number. The insurer should acknowledge the claim and explain next steps, including inspection procedures and documentation requirements. Retain copies of all communications, and address questions promptly. Clear, accurate communication helps the insurer assess the loss and handle it promptly, while enabling the owner to protect the property and meet policy obligations.
Critical Evidence in an Immokalee Property Claim Storm & Weather Damage Injury Case
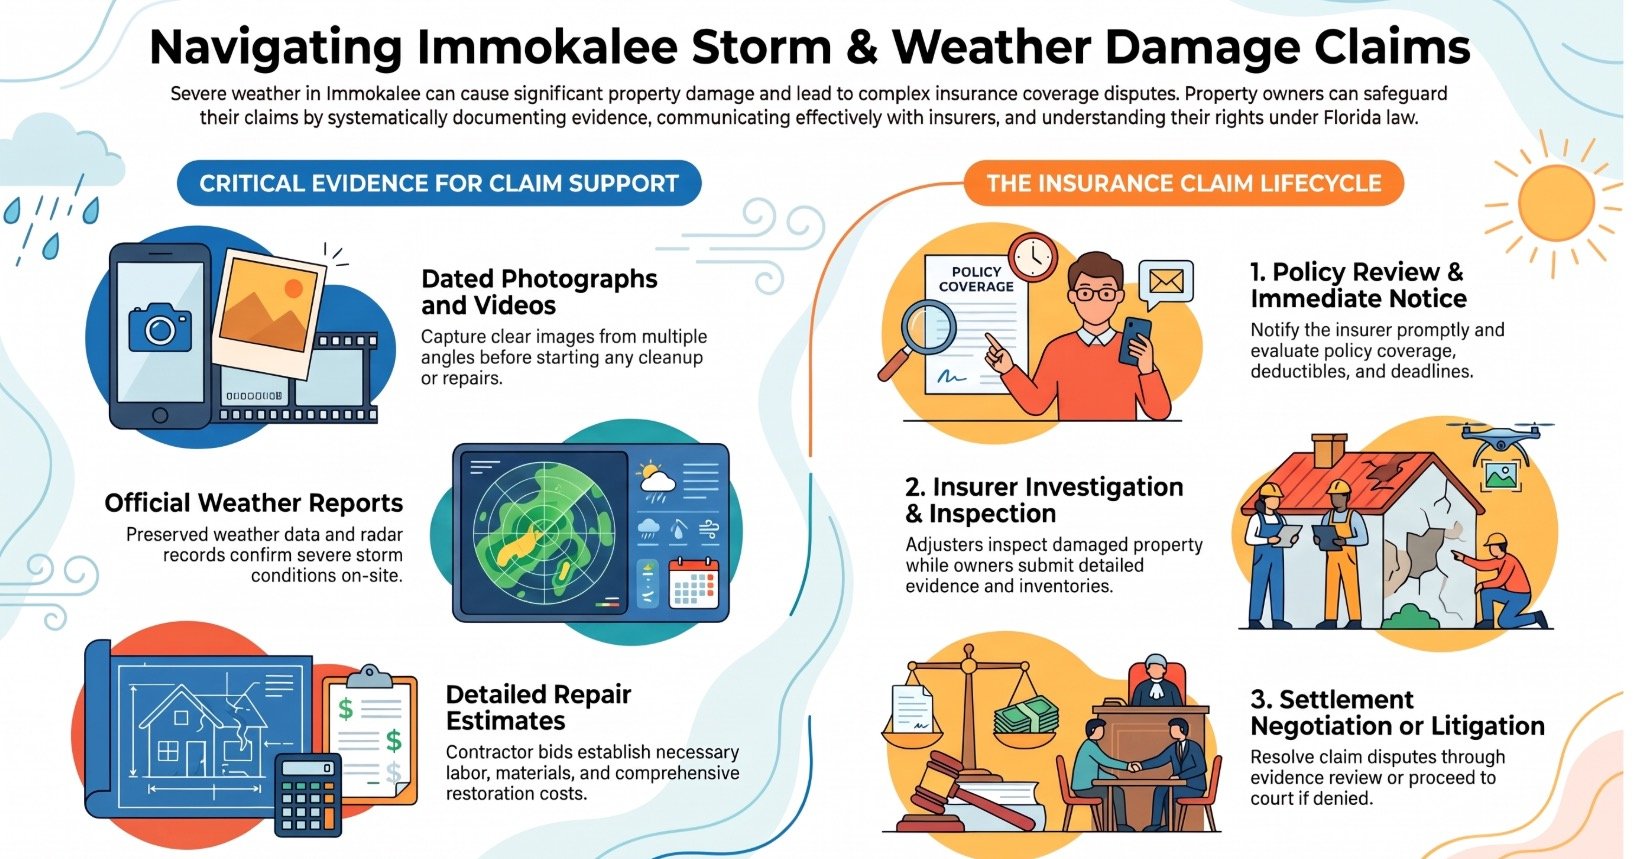
A well-supported storm damage claim relies on evidence that documents the loss, establishes the weather event, and supports the cost of repairs.
Essential records include:
- Dated photographs showing the damage and how it progressed.
- Weather reports confirming storm conditions at the property.
- Repair estimates and witness statements that help substantiate the scope and circumstances of the loss.
Dated Damage Photographs
When storm or weather damage affects an Immokalee property, dated photographs can help establish the building’s condition and the timing of the loss. Images taken soon after the event may document roof openings, water intrusion, damaged contents, and other visible conditions before repairs or cleanup alter the scene. Clear photographs from multiple angles can help insurers, property owners, and professionals assess the reported damage and plan appropriate repairs. Photo metadata may preserve details such as capture dates, but it can be incomplete or changed when images are copied or edited. As a result, image authentication may involve retaining original files and documenting who took each photograph and when. Organized, accurate records can support a fair claim review and help property owners restore safe spaces for families, employees, and community members.
Weather Reports
Weather reports can help establish the conditions surrounding a storm-related property loss in Immokalee. Official records from the National Weather Service and other reliable sources may document rainfall, wind speeds, hail, and the storm’s timing. Weather radar can show a storm’s path and intensity near a property, helping clarify whether reported damage aligns with the event. Storm forecasts may also indicate what conditions were expected, although forecasts alone do not prove that a particular loss occurred. Property owners can preserve dated alerts, radar images, local station reports, and agency summaries for review. These materials may assist insurers, adjusters, and legal professionals in evaluating a claim. Careful documentation supports a fair assessment and helps those assisting affected residents explain the event’s circumstances accurately and respectfully.
Repair Estimates
Repair estimates can provide important evidence in an Immokalee property claim involving storm or weather damage. They document the anticipated work and costs needed to restore damaged property, helping show the financial effect of a covered event. Detailed estimates should identify affected areas, materials, labor, and proposed repairs. Contractor bids may offer useful comparisons, especially when multiple professionals assess the same damage. Differences between estimates can reveal scope discrepancies, such as omitted repairs, differing material assumptions, or incomplete measurements. Clear documentation helps the insurer evaluate the claim and supports a fair assessment of necessary work. Property owners can preserve dated estimates, photographs, invoices, and related records to maintain an organized claim file. Accurate repair information may assist those seeking to protect their households and communities while pursuing a responsible resolution to property damage.
Witness Statements
Witness statements can provide valuable evidence in an Immokalee property claim involving storm or weather damage and related injuries. Neighbors, visitors, contractors, and first responders may have observed the storm, property conditions, or events leading to an injury. Their accounts can help establish when damage occurred, identify hazards, and clarify how the incident affected occupants or others who needed assistance.
Witness credibility depends on factors such as firsthand knowledge, consistency, and the ability to recall events accurately. Statements should distinguish direct observations from assumptions and avoid speculation about technical causes. Promptly preserving statements can protect details that may fade over time. Recording the witness’s contact information, the date, and the circumstances of the observation can support later review. With appropriate consent, written or recorded accounts may help insurers and decision-makers assess the claim fairly and understand the needs of those affected.
Long-Term Effects of Immokalee Property Claim Storm & Weather Damage Injuries
Storm- and weather-related injuries may persist long after the immediate damage is addressed. Some individuals experience chronic pain and lasting mobility issues that interfere with daily activities and work. Emotional distress may also continue, making appropriate medical care and documentation important.
Chronic Pain
Chronic pain can persist long after storm or weather damage is repaired, especially when an injury goes unrecognized or isn’t treated promptly. For Immokalee residents affected by unsafe property conditions, ongoing pain may follow falls, impact injuries, or exposure to debris and hazardous materials. Symptoms can interfere with concentration, daily responsibilities, and the ability to care for family members or serve the wider community. Sleep disruption may further affect mood and overall health, making consistent medical care important. A qualified provider can assess the source of pain, recommend appropriate treatment, and document its progression. Pain management may involve medication, therapy, or other clinically supported approaches tailored to the individual. Keeping records of symptoms, appointments, and related expenses can help clarify the injury’s effects when an insurance claim is evaluated. Each person’s recovery and treatment needs differ.
Lasting Mobility Issues
When severe weather causes property damage and injury, lasting mobility issues may continue after the immediate hazards are addressed. Damage to joints, bones, or soft tissue can limit walking, standing, climbing stairs, or completing routine tasks. These restrictions may affect a person’s ability to return to work, attend medical appointments, and contribute to family or community responsibilities. Recovery can require ongoing rehabilitation, home modifications, or Assistive devices such as braces, walkers, or wheelchairs. Accessible transportation may also be necessary when injuries prevent safe driving or make public transit difficult to use. Documenting these limitations, treatment needs, and related expenses can help clarify the injury’s long-term effects during a property claim. Medical assessments and consistent records provide useful evidence of functional changes and support planning for future care and daily access.
Emotional Distress
Even after physical injuries begin to heal, severe weather-related property damage can cause lasting emotional distress. Displacement, financial uncertainty, and reminders of the storm may lead to persistent anxiety, sleep disruption, or difficulty concentrating. These effects can affect work, family responsibilities, and a person’s ability to assist others in the community. Recognizing emotional symptoms is an important part of recovery, not a sign of weakness. Qualified mental health professionals can help individuals develop practical coping strategies and support emotional resilience over time. Anxiety management may include counseling, structured routines, and appropriate medical care. Property claim documentation should also reflect relevant treatment expenses and the impact of distress on daily functioning. Clear records can help explain the full consequences of storm-related harm when an insurer evaluates a claim, while timely support may reduce longer-term effects.
Don’t Wait. Call Our Florida Personal Injury Lawyers Now!
Proving Liability in Immokalee Property Claim Storm & Weather Damage Injury Cases
Proving liability in an Immokalee storm or weather damage injury case requires more than showing that severe conditions caused harm; the injured person must establish that a property owner or another responsible party failed to take reasonable steps to address a foreseeable hazard. Duty standards depend on the relationship between the parties and the circumstances, including whether the responsible party knew or reasonably should have known about a dangerous condition. Evidence may include maintenance records, inspection practices, repair requests, photographs, weather reports, and witness accounts. These materials can show whether the responsible party took reasonable precautions, such as securing loose structures, clearing blocked drainage, or warning visitors about unsafe areas. A causation analysis must also connect the alleged failure to the injury, rather than to the storm alone or another independent cause. Medical documentation and timely scene evidence can clarify that connection. Careful fact gathering supports accountability and helps protect others from preventable hazards during future severe weather events.
Dealing With Insurance Companies After an Immokalee Property Claim Storm & Weather Damage Injury
After a storm-related injury on another person’s property in Immokalee, insurance companies may investigate the incident and assess whether the policy covers the loss. Their review may include photographs, incident reports, medical records, and statements about the hazardous condition. Policy interpretation matters because coverage can depend on the policy’s terms, exclusions, and the circumstances surrounding the injury. A property owner’s insurer may also evaluate whether the owner had notice of the danger and took reasonable steps to address it.
Clear communication with adjusters can help keep information accurate and focused. Injured visitors may be asked to provide statements or authorize access to records; they should understand what is being requested before responding. Inconsistent descriptions or incomplete documentation may complicate the insurer’s assessment. To seek fair treatment, preserve relevant records, avoid speculation, and communicate respectfully. When coverage questions or settlement discussions become difficult, legal guidance may help clarify rights and support an informed response without disrupting the injured person’s recovery.
What to Expect During an Immokalee Property Claim Storm & Weather Damage Injury Claim Process
A storm and weather damage claim typically begins with an initial review of the policy, reported losses, and relevant deadlines. The claimant then documents the damage while the insurer investigates, which may include inspections and requests for supporting records. Based on the findings, the claim may resolve through a settlement or proceed to litigation if the parties cannot agree.
Initial Claim Review
During the initial review, an Immokalee property claim lawyer typically examines the insurance policy, damage records, and communications with the insurer to assess how the storm or weather event affected the property. Policy review identifies notice requirements, deadlines, exclusions, and duties the policyholder must follow. Coverage analysis considers whether the reported event and resulting property conditions may fall within the policy’s terms. The lawyer may also compare the insurer’s position with the policy language and determine whether additional information is needed to clarify disputed issues. This early assessment helps the property owner understand available options and make informed decisions while meeting contractual obligations. For households and organizations seeking to protect those who depend on their property, a careful review can support a clear, responsible response. It also establishes priorities for communication and claim handling without promising a particular outcome.
Damage Documentation
Clear damage documentation can help establish how a storm or other weather event affected an Immokalee property. During this stage, the property owner or representative may photograph damaged areas, record the date of discovery, and describe visible conditions before cleanup or repairs begin. Moisture mapping can identify damp materials and show how water has spread through walls, flooring, or other building components. A detailed contents inventory can list affected belongings, their condition, and information on available purchases or repairs. Receipts, maintenance records, and contractor estimates may also help explain the property’s condition and the work required. Organized records can support accurate communication about the loss and help those responsible for the property make informed decisions. Preserve documentation in a secure format, and keep copies for future reference and any necessary follow-up.
Insurance Investigation
After a storm-related property claim is reported, the insurer typically investigates to assess the reported damage, determine its cause, and evaluate coverage under the policy. During this claim investigation, the insurer may review the policy, inspect the property, and request photographs, repair estimates, receipts, or other supporting records. An adjuster may visit the site, ask questions about when the damage occurred, and document visible conditions. The property owner should provide accurate information and identify areas that may be unsafe or inaccessible. Clear records of communications and inspection dates help keep the claim file organized. Adjusters should remain professional, and inspections should address the reported damage fairly. If the investigation overlooks relevant evidence or raises questions about the cause or extent of loss, the owner may submit additional documentation and seek clarification about the insurer’s findings.
Settlement Or Litigation
Once the insurer completes its investigation, the claim may proceed to settlement discussions or, if the parties cannot resolve their disagreement, litigation. Settlement negotiations typically involve reviewing repair estimates, policy terms, photographs, and other evidence of storm or weather damage. The insurer may offer payment, request additional documentation, or dispute some portion of the claimed loss. A property owner should assess any proposed agreement carefully, including whether it addresses covered damage and future repair costs. If negotiations do not produce a fair resolution, litigation may allow the parties to present evidence before a court. Counsel can develop a litigation strategy based on the policy, investigation findings, and applicable deadlines. Throughout either path, clear records and timely communication help protect the claim and support an informed decision about pursuing recovery for necessary property repairs.
Compensation for Immokalee Property Claim Storm & Weather Damage Injury Damages
Storm and weather damage claims in Immokalee may cover losses to a home, personal property, and related expenses, depending on the insurance policy and the cause of the damage. Available benefits depend on policy limits, exclusions, deductibles, and the evidence supporting the claim. Homeowners may seek payment for repairs to roofs, walls, windows, and other insured structures, as well as replacement or repair of damaged belongings. When a residence becomes unsafe or uninhabitable, coverage may provide Temporary housing and certain additional living expenses, subject to policy terms and limits. Affected businesses may have coverage for business interruption when a covered event disrupts operations, though eligibility and duration depend on the policy. Insurers generally require prompt notice, documentation of damage, and reasonable steps to prevent further loss. Photographs, receipts, repair estimates, and records of related expenses can help substantiate requested benefits. Carefully review the policy and the claim decision to clarify what compensation may be available.
Economic vs. Non-Economic Damages in Immokalee Property Claim Storm & Weather Damage Cases
Storm and weather damage claims may include economic losses, such as repair costs, damaged belongings, and temporary housing expenses. They may also involve non-economic harm, including disruption to daily life or loss of use of the property. Clear records, photographs, receipts, and repair estimates can help document the damages being claimed.
Economic Losses
In Immokalee property claims involving storm or weather damage, economic losses are the measurable financial costs caused by the covered event, such as repair expenses, damaged belongings, and temporary housing. These costs may also include emergency mitigation, debris removal, and reasonable expenses for protecting property from further damage. Owners should preserve invoices, receipts, contractor estimates, photographs, and payment records to support the amount claimed. When a storm forces a business to close or operate at reduced capacity, Lost revenue and business interruption expenses may also apply, subject to policy terms and proof of loss. Accurate documentation helps insurers assess the claim and can clarify which expenses are directly connected to the event. A careful review of coverage limits, exclusions, and deadlines can help property owners pursue payment while maintaining resources for employees, tenants, and community needs.
Non-Economic Harm
Although property damage can create substantial personal strain, non-economic harm is generally distinct from the financial losses covered by a property insurance claim. Economic damages may include repair costs, temporary housing, or damaged belongings. Non-economic harm concerns personal effects that do not have a direct price, such as disruption, stress, or reduced comfort after a storm or weather event. Quality-of-life changes may arise when a damaged home limits privacy, disrupts routines, or reduces a resident’s ability to use familiar spaces. Loss of enjoyment impacts may also occur when property conditions prevent ordinary family activities or community gatherings. These experiences can matter deeply to affected households, particularly when residents depend on their homes for stability and connection. However, their significance does not automatically make them recoverable under a property insurance policy.
Documenting Damages
When storm or weather damage affects a property in Immokalee, clear records help distinguish measurable financial losses from personal effects that may not be covered by insurance. Economic damages may include repair estimates, temporary housing costs, cleanup expenses, and lost rental income. Receipts, invoices, contractor reports, and dated photographs can support these amounts and help claim reviewers assess the loss. Moisture meter readings may document water intrusion and changing conditions, while inspection notes can identify affected materials and necessary work. A Personal property inventory should list damaged belongings, their age, condition, purchase details, and estimated replacement cost. Non-economic effects, such as disruption, stress, or loss of use, should be recorded separately, with dates and specific examples. Organized documentation helps property owners present accurate claims and enables professionals to evaluate disputed damages responsibly.
When an Immokalee Property Claim Storm & Weather Damage Injury Case Goes to Trial vs Settlement
The decision to resolve an Immokalee storm or weather damage property claim through settlement or trial depends on the strength of the evidence, the scope of the loss, and the insurer’s willingness to offer fair compensation. A settlement may provide a more timely, predictable resolution and reduce the expense and uncertainty of court proceedings. It can also let property owners focus on repairs and their families’ or community’s needs.
If negotiations do not produce an adequate offer, you may consider trial. A judge or jury then evaluates the evidence and determines the outcome, but the process can take longer and carries no guaranteed result. Careful trial preparation includes organizing inspection records, repair estimates, photographs, and relevant communications to clearly present the claimed losses.
Settlement leverage may improve when the claim is supported by consistent documentation and a credible assessment of damages. Legal counsel can explain the practical differences between both options, assess available evidence, and help property owners choose a path that serves their interests responsibly.
Florida Laws That May Affect Your Immokalee Property Claim Storm & Weather Damage Case
A settlement or trial decision in an Immokalee storm damage claim may depend on Florida laws governing insurance coverage, claim deadlines, and dispute procedures. These rules can shape what evidence matters and how policyholders pursue recovery while protecting the interests of households and communities affected by severe weather.
Florida insurance laws and policy terms can shape how Immokalee storm claims are evaluated and resolved.
- Policy language controls coverage. Insurers and courts may examine exclusions, deductibles, notice requirements, and duties to document damage. Clear photographs, repair records, and prompt communication can help establish the claim’s factual basis.
- Florida notice deadlines may require a policyholder to report a loss within a specified period. The applicable deadline depends on current law and policy terms, so delay may complicate review or reduce available options.
- Concurrent causation rules may affect losses involving both covered storm damage and excluded causes, such as flooding or wear. Policy wording and evidence linking each cause to the damage can affect coverage.
Florida law also provides procedures for addressing claim disputes. Careful compliance and reliable documentation support fair evaluation and responsible resolution for everyone affected.
Don’t Wait. Call Our Florida Personal Injury Lawyers Now!
The Statute of Limitations for Immokalee Property Claim Storm & Weather Damage Injury Cases
After storm or weather damage in Immokalee, the deadline to file a property insurance lawsuit may depend on Florida law, the policy, and the circumstances of the claim. Florida law sets time limits for certain insurance disputes, and legislation may change those limits. The applicable period can depend on the type of claim and when the loss occurred, so older damage should not be assumed to fall under current rules.
Policy deadlines also matter. A policy may require prompt notice, documentation, or other steps before you can file a lawsuit. These requirements are distinct from the statutory limitation period, and missing one may affect coverage even when a lawsuit remains timely. Contract provisions can establish additional duties or conditions, subject to Florida law and the policy’s wording.
Property owners seeking to preserve resources for their families, tenants, or community should keep claim records and note all dates. Timely attention to both legal and policy requirements can protect the opportunity to seek compensation for covered damage.
How an Immokalee Property Claim Storm & Weather Damage Lawyer Can Help You
When storm damage raises questions about policy duties, deadlines, or the value of a loss, an Immokalee property claim lawyer can help assess the claim and explain available options. The lawyer may organize records, clarify insurer communications, and identify issues affecting recovery. This support helps property owners make informed decisions while preserving resources for family, employees, tenants, or community responsibilities.
- Policy Review: Counsel examines relevant provisions, exclusions, deductibles, and notice requirements, then explains how they may apply to documented storm damage.
- Evidence Assessment: The lawyer reviews photographs, repair estimates, inspection findings, and other records to evaluate whether the claimed loss is adequately supported.
- Coverage Disputes: If the insurer questions responsibility or valuation, counsel can present relevant documentation, address the stated concerns, and pursue available procedures under the policy.
Through organized advocacy, a lawyer can help keep the claim focused on verifiable facts and contractual obligations. The process also provides a clearer basis for evaluating proposed resolutions and planning necessary repairs.
When to Contact an Immokalee Property Claim Storm & Weather Damage Lawyer
Prompt legal guidance may help when storm damage is substantial, the insurer delays its response, or the coverage decision doesn’t reflect the available evidence. A property owner may also want to contact counsel when the insurer repeatedly requests documentation, disputes the cause or extent of damage, or offers payment that seems inconsistent with repair estimates.
Early attention can help preserve photographs, inspection reports, receipts, correspondence, and other records relevant to a claim. Policy deadlines may apply to reporting damage, submitting required materials, or pursuing further review, so claimants should check the policy and promptly clarify any uncertainty. Waiting until a deadline is near can limit available options.
Claimants may consult a lawyer when coverage disputes remain unresolved after direct communication with the insurer, or when the claim’s status is unclear. Timely advice can help property owners understand procedural requirements and make informed decisions while protecting resources needed for household recovery and community responsibilities. Each situation depends on its facts and policy terms.
Why You Need an Experienced Immokalee Property Claim Storm & Weather Damage Lawyer
An experienced Immokalee property claim storm and weather damage lawyer can help property owners assess a disputed claim and understand how the policy applies to the documented damage. This guidance can be especially valuable when a damaged home or business affects the safety and stability of residents, employees, or community services.
Policy Knowledge helps counsel interpret coverage terms, exclusions, deadlines, and insurer obligations. A lawyer can compare the policy language with inspection findings, repair estimates, photographs, and other evidence, then identify gaps in the insurer’s explanation. This review may clarify whether the insurer undervalued, delayed, or denied the claim without adequate support.
A sound Claim Strategy can organize the evidence and present a clear response to the insurer. Counsel may communicate with adjusters, address requests for information, and explain the basis for seeking additional payment. With informed assistance, property owners can focus on recovery and supporting those who depend on them while pursuing a fair resolution through the proper channels.
How to Choose the Right Immokalee Property Claim Storm & Weather Damage Lawyer for Your Case
Choosing the right Immokalee property claim storm and weather damage lawyer requires careful attention to the attorney’s experience, communication, and approach to disputed claims. A suitable lawyer should understand Florida property insurance practices and have experience handling storm-related losses, including denied, delayed, or underpaid claims. Reviewing an Attorney’s credentials can confirm licensing, relevant practice areas, and disciplinary history.
The attorney should explain the claim process clearly, identify potential challenges, and set realistic expectations without promising a specific outcome. Effective representation also depends on responsiveness and careful review of photographs, repair estimates, policy documents, and insurer correspondence. These qualities matter when a property owner seeks to protect a home or business and maintain stability for family members, employees, or neighbors who rely on it.
Before signing an agreement, the claimant should review the Fee structure, including how legal fees and case expenses are handled. Comparing these details and asking focused questions can help property owners make an informed choice suited to their circumstances.
About The Law Offices of Anidjar & Levine
The Law Offices of Anidjar & Levine represents clients in property insurance disputes, including claims involving storm and weather damage. The firm helps property owners understand policy requirements, document losses, and respond to insurance company decisions. Its work may include reviewing claim records, communicating with insurers, and pursuing available legal remedies when a covered loss is disputed or underpaid.
The firm’s history provides context for how it has developed its approach to client service. The firm handles a range of injury and insurance matters and serves people facing significant disruptions to their homes and daily lives. Its attorneys assess each claim based on the policy language, the reported damage, and the insurer’s handling of the matter.
Attorney credentials, including education, licensing, and relevant experience, can help property owners evaluate legal representation. Clients may ask about an attorney’s background with property claims, case strategy, fees, and communication practices. Clear answers support informed decisions and help clients pursue fair treatment while restoring their property.
Frequently Asked Questions
Does Homeowners Insurance Cover Temporary Housing After Storm Damage in Immokalee?
Homeowners insurance may cover temporary housing after storm damage in Immokalee if covered damage makes the home uninhabitable. This protection is commonly called Additional Living Expenses or Loss of Use. It may reimburse reasonable costs, such as lodging and increased meal expenses, while repairs are completed, subject to policy limits, deductibles, and exclusions. The homeowner should review the policy, document expenses, and contact the insurer promptly to confirm eligibility and required approval.
Can I Hire a Public Adjuster for My Immokalee Property Damage Claim?
Yes, a property owner may hire a licensed public adjuster to represent them in an Immokalee property damage claim. The adjuster can document losses, review policy terms, and communicate with the insurer, but cannot guarantee payment or replace legal counsel. Before hiring, verify the license and experience, review the written contract, and understand Public adjuster fees in Florida. Choosing a qualified adjuster carefully helps protect the owner’s interests and supports a fair, well-documented claim.
What if My Storm Damage Was Caused by Flooding Rather Than Wind?
If storm damage resulted from flooding, coverage may depend on a separate Flood insurance policy rather than standard homeowners insurance. Many homeowners policies contain a water exclusion that limits coverage for rising water, though they may cover certain sudden plumbing leaks or wind-driven rain. The policyholder should document damage, prevent further loss when safe, and promptly notify each relevant insurer. A qualified adjuster can help assess the cause and clarify what coverage is available.
Can I Reopen a Property Insurance Claim After Discovering Hidden Storm Damage?
You may reopen a property insurance claim after discovering hidden storm damage, but approval depends on the policy, claim status, and applicable deadlines. The policyholder should promptly notify the insurer and preserve Hidden Damage Documentation, including dated photographs, repair estimates, inspection reports, and records of when the damage became apparent. Reopening Claim Deadlines vary, so timely review of policy terms and consultation with a qualified professional can help protect the claim and support a fair resolution.
Will Filing a Storm Damage Claim Increase My Homeowners Insurance Premiums?
Filing a storm damage claim can increase homeowners insurance premiums, but an increase is not automatic. The premium impact depends on the insurer’s underwriting rules, the claim’s size, local storm losses, and claim frequency. Some insurers may raise rates after a paid claim, while others may not surcharge weather-related losses. Policyholders should review coverage and deductibles, document damage carefully, and ask their insurer how a claim could affect renewal pricing before deciding how to proceed.
—————————
Storm and weather damage claims can involve intricate policy terms, strict deadlines, and disputes over the cause or value of property losses. An experienced Immokalee property claim lawyer can review the evidence, explain a policyholder’s rights, and address insurer challenges. The Law Offices of Anidjar and Levine represent property owners seeking a fair resolution. Prompt legal guidance can help protect important documentation and clarify the steps available after storm damage. Learn more about an Immokalee Personal Injury Lawyer.