The Law Offices of Anidjar and Levine can help Stuart property owners review storm and weather damage policy terms, assess reported losses, and respond to insurer disputes. Coverage depends on the policy language, the cause and timing of the damage, and supporting evidence. Owners should report losses promptly, preserve photographs, estimates, receipts, and communications, and take reasonable steps to prevent further damage. Legal guidance may clarify deadlines, exclusions, coverage limits, and options when payment is delayed or denied. For other legal assistance, see the Stuart Personal Injury Lawyer page. The following sections explain these issues and related claim steps.
Main Takeaways
- A Stuart property claim lawyer can review your policy, storm damage, and insurer communications to assess potential coverage.
- Coverage depends on policy wording, the storm’s cause and timing, documented damage, exclusions, and applicable Florida requirements.
- Photograph damage before cleanup, preserve repair estimates and receipts, and keep copies of all claim communications.
- Report damage promptly, meet policy deadlines, provide requested records, and take reasonable steps to prevent further loss.
- If payment is delayed, damage is undervalued, or coverage is denied, legal guidance may help with negotiation, appeal, or court options.
Don’t Wait. Call Our Florida Personal Injury Lawyers Now!
How We Can Help With Your Stuart Property Claim Storm & Weather Damage Injury Claim
A Stuart property claim storm and weather damage lawyer can help policyholders document losses, interpret insurance requirements, and respond to disputes over coverage or payment. The lawyer’s role may include reviewing policy terms, organizing claim records, and explaining available options in clear language. Careful policy interpretation can help a property owner understand notice deadlines, documentation duties, exclusions, and limits that may affect a claim.
Support may begin with an assessment of Claim eligibility based on the policy, reported damage, and relevant claim materials. The lawyer can identify missing records, help prepare communications with the insurer, and address requests for additional information. When an insurer delays payment, disputes the scope of covered damage, or denies a claim, counsel can explain the reasons given and outline possible responses.
This assistance can reduce confusion during a demanding process and help policyholders make informed decisions. By approaching each matter with diligence and respect, legal counsel can support fair claim consideration while keeping clients’ practical needs in view.
Understanding Stuart Property Claim Storm & Weather Damage Injury Cases
Storm and weather damage claims involve more than identifying visible harm to a property; they also require understanding how the policy applies to the cause, timing, and extent of the loss. In Stuart, a claim may depend on the policy’s coverage terms, exclusions, deadlines, and documentation requirements. Insurers generally assess the reported damage against these provisions and the evidence submitted by the property owner.
OUR CONSULTATIONSARE FREE
START YOUR FREE CASE REVIEW
A careful review can help clarify which losses may be covered, what proof is needed, and how disputed assessments may be addressed. Records such as photographs, repair estimates, inspection reports, and communications with the insurer can support an accurate evaluation. Prompt steps to protect people and property may also matter, as long as they do not compromise evidence or violate policy conditions.
Reliable claim guidance can help property owners make informed decisions while supporting Neighborhood recovery. Clear information also strengthens emergency preparedness by helping residents understand their responsibilities before a future loss occurs. Each case requires attention to its specific policy language, facts, and applicable Florida requirements.
Common Causes of Stuart Property Claim Storm & Weather Damage
Storm and weather damage in Stuart often results from hurricane-force winds, heavy rainfall, and hail. These conditions can damage roofs, siding, windows, and other parts of a property. Flooding and storm surge may also cause significant water damage, particularly in low-lying or coastal areas.
Hurricane-Force Winds
When hurricane-force winds strike Stuart, they can tear roofing materials loose, break windows, damage exterior walls, and allow rain to enter the property. Windborne debris, including branches and unsecured objects, may puncture roofs or shatter glass, creating openings that expose interior finishes and belongings. Roof uplift can loosen shingles, tiles, or structural connections, even when damage is not immediately visible from the ground. Property owners may need to arrange prompt inspections, document affected areas, and take reasonable steps to protect the building from further harm. These measures can support a clear record of the loss and help contractors identify necessary repairs. Carefully review the insurance policy, photographs, repair estimates, and communications with the insurer to determine whether the reported wind damage is covered.
Heavy Rainfall
Heavy rainfall in Stuart can overwhelm drainage systems, flood low-lying areas, and allow water to enter buildings through roofs, windows, doors, or foundation openings. Rainfall intensity and duration influence how quickly water accumulates and whether gutters, drains, and nearby waterways can carry it away. When drainage failures occur, water may pool beside structures, seep into crawl spaces, or damage interior finishes and personal property. Saturated soil can also place pressure on foundations and contribute to leaks or structural concerns. Property owners serving tenants, customers, or community members should document visible damage, take reasonable steps to limit further loss, and preserve receipts for emergency work. Photographs, inspection records, and weather reports may help establish the event’s effects. Reviewing policy terms promptly can clarify notice requirements and available coverage.
Hail Impact
Hail can damage Stuart properties by bruising roof shingles, cracking tiles, denting metal surfaces, and breaking windows or exterior fixtures. Hailstone formation begins when strong storm updrafts carry water droplets into freezing air, allowing layers of ice to build before stones fall. Their size, density, and wind-driven speed affect the severity of damage to roofs, siding, vehicles, and outdoor equipment. Documented impact patterns can help distinguish hail damage from ordinary wear, especially when dents or fractures appear across exposed surfaces. A careful inspection may identify concealed damage, such as loosened shingles or compromised protective coatings, that is not immediately visible from the ground. Timely records, photographs, and professional assessments can support accurate property claim reviews and help owners address hazards that could affect occupants, neighbors, or future repairs.
Flooding and Storm Surge
Beyond hail impacts, flooding and storm surge can cause extensive damage to Stuart properties, particularly in low-lying areas and locations near waterways. Heavy rainfall may overwhelm drainage systems, while rising tides and powerful coastal winds can push water inland. These events can damage foundations, roofs, electrical systems, and personal belongings, and may leave behind contamination that requires careful cleanup.
Property owners can review flood zone mapping to understand local exposure, though mapped risk does not guarantee protection from unusual weather. Storm surge barriers and other protective measures may reduce some hazards, but their effectiveness depends on design, maintenance, and storm conditions. After a flood, prompt documentation of damage and reasonable steps to prevent further loss can support a clear insurance claim. A qualified professional can help assess coverage, exclusions, and required evidence.
Legal Rights of Stuart Property Claim Storm & Weather Damage Injury Victims
When a storm or severe weather damages a home or business in Stuart, property owners may have legal rights under their insurance policies and Florida law. Those rights may include requesting a prompt, fair review of a covered loss and challenging an inadequate denial or payment. Policy language, deadlines, and supporting records can affect available remedies. A careful review may help owners protect their households, employees, tenants, and community resources.
- Policyholders may report damage promptly and provide requested information.
- Insurers generally must handle claims in accordance with applicable Florida requirements.
- Coverage disputes may involve damage assessments, valuation, or interpreting policy terms.
- Policy exclusions may limit recovery, but their application depends on the wording and circumstances.
- Owners may seek legal guidance about appeals, negotiation, or available court action.
Photographs, repair estimates, inspection records, and written communications can help document a claim. Owners should preserve relevant materials and avoid unsupported statements about the cause or value of damage. Legal counsel can explain options without guaranteeing a particular outcome.
Why Do Stuart Property Claim Storm & Weather Damage Injuries Happen?
Storm and weather damage claims in Stuart often arise from powerful winds, heavy rain, flooding, lightning, or falling trees that harm roofs, structures, and personal property. Injuries may occur when damaged buildings become unsafe or when hazards develop during severe conditions. Structural failures, such as a weakened roof, collapsing ceiling, or unstable wall, can strike occupants, workers, or visitors. Water intrusion may also create slippery floors, conceal holes, or expose electrical systems, increasing the risk of falls and shocks.
Debris hazards present another common source of harm. Broken glass, roofing materials, branches, and displaced household items can obstruct walkways or cause cuts and impact injuries. Floodwater may carry contaminants or hide sharp objects, while fallen trees can damage vehicles and block access routes. In some cases, inadequate maintenance or delayed repairs leave a property more vulnerable to foreseeable weather impacts. These circumstances can affect residents, guests, and others who enter to provide assistance, making safe property conditions important to the wider community.
What Should You Do After a Stuart Property Claim Storm & Weather Damage Injury?
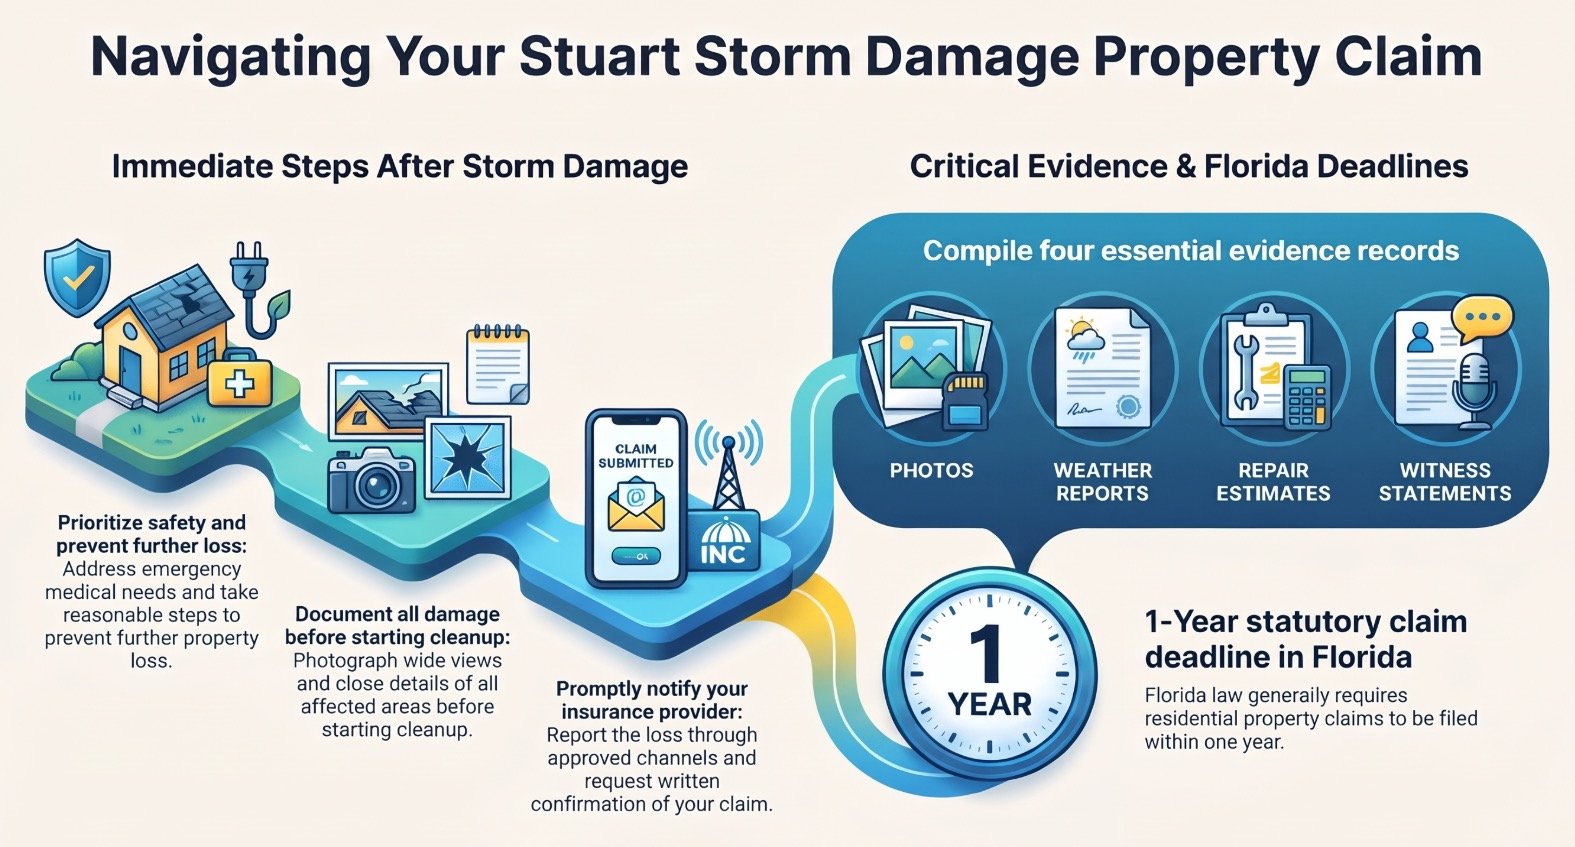
After storm or weather damage, occupants should first move away from hazards and seek emergency assistance when needed. They should photograph and record visible damage and preserve receipts and other relevant records. Notifying the insurer promptly can start the claim review and clarify the next steps.
Prioritize Immediate Safety
Anyone injured during severe weather or while responding to property damage should move to a safer location if possible and call 911 for urgent medical help. If conditions remain dangerous, others nearby should avoid entering damaged areas and contact emergency responders rather than attempting a risky rescue. Downed power lines, unstable structures, floodwater, and gas odors require distance and prompt notification to the appropriate authorities. Once immediate medical needs are addressed, occupants should follow official instructions and leave the property if evacuation is advised. Evacuation planning can help households identify safe routes, account for vulnerable residents, and arrange transportation before conditions worsen. If displacement becomes necessary, an emergency shelter or another secure location can provide temporary protection. A designated person may coordinate assistance for neighbors while ensuring responders can work safely and without interference.
Document All Damage
Once immediate safety concerns are addressed, a clear record of the property damage can help support a storm or weather claim. The property owner should photograph and video each affected area before cleanup or repairs begin, capturing wide views and close details. Images should include damaged roofing, broken windows, fallen trees, standing water, and affected personal belongings. An Inventory checklist can identify damaged items, their approximate age, purchase date, and replacement cost. Receipts, warranties, and maintenance records may help establish ownership and prior condition. Notes should record when you discovered the damage and any changes you observed afterward. If water intrusion is present, a qualified professional can do moisture mapping to document damp areas that may not be visible. Organized, dated records can help others assess the loss accurately and preserve useful evidence for later review.
Contact Your Insurer
Contacting the insurer promptly can help begin the review of storm-related property damage. The property owner should report the loss through an approved channel and request confirmation that the insurer received the claim notice. A clear account of when the storm occurred, what areas were affected, and whether temporary repairs were necessary can help the insurer open its file. Organize photographs, repair estimates, and records of damaged belongings for submission when requested.
The owner should review the policy deadlines for reporting damage and providing supporting documents. These requirements may vary by policy, so prompt attention can help prevent avoidable disputes about late notice. Communications with the insurer should remain factual, and the owner should retain copies of forms, emails, and call notes. If the insurer requests an inspection, the owner should coordinate access while continuing reasonable steps to protect the property from further damage.
Critical Evidence in a Stuart Property Claim Storm & Weather Damage Injury Case
A well-supported storm damage claim depends on evidence that documents the property’s condition, the weather event, and resulting losses.
Relevant records may include:
- Photographs of storm damage
- Weather reports and alerts
- Repair estimates and receipts
- Witness statements
- A timeline of events and communications
Together, these materials can help establish the cause and extent of the damage.
Storm Damage Photographs
Photographs taken soon after a storm can help establish the condition of a Stuart property and document damage before repairs or further weather exposure alter the evidence. Images should show the full exterior and interior, then provide clear close-ups of damaged roofs, windows, ceilings, flooring, and personal property. A consistent sequence can help reviewers understand where each condition occurred and how separate areas relate to one another. Photo Metadata, including capture dates and times, may support the chronology when files remain intact. An Image Backup stored separately can reduce the risk that original photographs are lost or altered. Property owners should preserve unedited files and keep copies of any images shared with insurers or contractors. Careful documentation can assist a fair evaluation and help those affected communicate the scope of loss accurately.
Weather Reports And Alerts
Weather reports and alerts can help establish the conditions surrounding storm damage to a Stuart property and support the timing of a claim. Official records from the National Weather Service or other reliable sources may document rainfall, wind speeds, hail, flooding, and severe-weather warnings near the property. These details can help connect observed damage to a particular event and distinguish storm-related conditions from unrelated causes. Property owners can preserve dated forecasts, alert messages, and local advisories, noting when each was issued and received. Alert delivery records may show whether warnings reached residents before the storm, while forecast accuracy can help explain how closely predicted conditions matched what occurred. This documentation may also help insurers, adjusters, and community representatives evaluate the event fairly and respond responsibly to affected property owners.
Repair Estimates And Receipts
Repair estimates and receipts provide important evidence of the cost and scope of storm damage to a Stuart property. Detailed estimates can identify affected areas, necessary repairs, labor charges, and proposed materials, helping show whether a claim payment reflects the work required to restore the property. Contractor bids offer useful comparisons, particularly when repair methods or pricing differ. Material invoices document purchases and support the claimed cost of replacement items. Receipts for emergency services, temporary protection, and completed repairs can further establish expenses incurred to limit damage and restore safe conditions. Property owners serving their families, tenants, or community members benefit from keeping these records organized and legible. Retain copies with photographs and claim correspondence, and clearly distinguish storm-related repairs from unrelated maintenance or upgrades.
Witness Statements And Timelines
Witness statements and a clear timeline can help establish how a storm affected a Stuart property and when damage or related injuries occurred. Neighbors, tenants, contractors, and first responders may describe conditions before, during, and after the event. Their observations can clarify when water entered, roofing materials failed, or unsafe areas became apparent. Witness credibility depends on firsthand knowledge, consistent accounts, and accurate details, so statements should distinguish direct observations from assumptions. Timeline reconstruction can compare these accounts with weather reports, photographs, repair records, and medical documentation. This evidence may help explain whether damage developed suddenly or worsened over time and whether an injury followed a hazardous condition. Promptly recording names, contact information, and recollections can preserve useful details and support a fair, well-documented claim for the property owner and affected individuals.
Long-Term Effects of Stuart Property Claim Storm & Weather Damage Injuries
Storm and weather-related injuries may have lasting effects, including chronic pain that interferes with daily activities. Some individuals experience mobility limits that persist after initial treatment and require ongoing care. Emotional effects, such as anxiety or distress, may also continue and affect overall well-being.
Chronic Pain
Although storm and weather damage claims often focus on visible property losses, injuries sustained during severe conditions can lead to chronic pain that persists long after the immediate danger has passed. Falls, flying debris, and emergency cleanup may cause injuries whose symptoms continue after initial treatment. Persistent discomfort can interfere with work, household responsibilities, and a person’s ability to support family or community commitments. Sleep disruption may also affect concentration, mood, and recovery, adding strain to daily life. Appropriate Pain management can involve medical evaluation, prescribed treatment, and consistent follow-up to document symptoms and assess progress. Keeping records of appointments, expenses, and reported limitations may help clarify the injury’s continuing effects. When a storm-related injury causes lasting pain, careful documentation and timely professional guidance can support informed decisions about recovery and a property damage claim.
Lasting Mobility Limits
When storm-related injuries affect joints, bones, or the nervous system, mobility limits may persist after the immediate damage has been treated. A person may struggle to stand, walk across uneven ground, climb stairs, or return to work and household responsibilities. These restrictions can result from fractures, ligament damage, nerve impairment, or complications during recovery. Gait adaptations may develop as the injured person shifts weight to avoid discomfort or instability, sometimes placing added strain on other areas of the body. Physical therapy, follow-up care, and assistive devices can support safer movement and help preserve independence. However, progress may be gradual, and some limitations may remain permanent. Documented medical evaluations and treatment plans can clarify how an injury affects daily function and what support may be needed over time.
Ongoing Emotional Effects
Emotional effects can persist long after storm-related injuries have been treated, particularly when pain, reduced independence, or uncertainty about recovery disrupt daily life. For some Stuart residents, Sleep disruption may follow ongoing discomfort, medication changes, or concern about another severe weather event. Fatigue can then make work, family responsibilities, and rehabilitation more difficult. Anxiety triggers may include heavy rain, emergency alerts, damaged buildings, or reminders of the injury. These reactions can affect concentration, confidence, and willingness to return to familiar activities. Family members and caregivers may also observe withdrawal or increased distress, though symptoms differ among individuals. When emotional changes continue, a health professional can assess their effects and recommend appropriate support. Clear records of treatment and daily limitations may help explain how storm-related injuries have affected a person’s overall well-being and recovery.
Don’t Wait. Call Our Florida Personal Injury Lawyers Now!
Proving Liability in Stuart Property Claim Storm & Weather Damage Injury Cases
Proving liability in a Stuart property claim involving storm or weather damage requires evidence that connects the loss to a covered event and establishes the insurer’s obligations under the policy. Relevant records may include dated photographs, repair estimates, weather reports, maintenance documents, and statements from people who observed the damage. These materials can help show when the loss occurred, how it developed, and whether an existing condition contributed.
Policy interpretation is central to determining which losses are covered, what exclusions apply, and whether notice or documentation requirements were met. Causation standards may require distinguishing storm damage from wear, deterioration, or prior defects. A qualified inspector or engineer can assess the property and explain the likely source and extent of the harm.
Accurate, organized evidence supports a fair review and helps property owners protect homes and businesses that serve their families, employees, and communities. When facts are incomplete or disputed, careful documentation can clarify responsibility and preserve a reliable account of the loss.
Dealing With Insurance Companies After a Stuart Property Claim Storm & Weather Damage Injury
After a storm damages a home or business in Stuart, clear and consistent communication with the insurance company can help keep the claim review organized. Property owners who also face injury concerns may need to address both physical losses and related expenses. Claim communication should remain factual, timely, and supported by records such as photographs, repair estimates, medical bills, and written correspondence. Keeping copies of submissions and noting conversations can reduce misunderstandings and help make sure important details are not overlooked.
Insurers may request inspections, statements, or additional documentation. A careful response can clarify the damage while avoiding unsupported assumptions about its cause or value. When an offer does not reflect documented losses, settlement negotiation may involve presenting evidence and explaining why the proposed amount is inadequate. Legal guidance can help property owners understand policy terms, evaluate communications, and protect their interests while seeking fair treatment. This measured approach can also support families and businesses working to restore safe, stable conditions.
What to Expect During a Stuart Property Claim Storm & Weather Damage Injury Claim Process
A storm or weather damage claim typically begins with prompt reporting to the insurer and clear documentation of the property damage and related losses. The insurer then reviews the evidence and policy terms to determine what coverage may apply. If disagreements arise over the damage, valuation, or coverage, the parties may pursue further review or dispute resolution.
Reporting the Damage
Prompt reporting is important after a storm or severe weather event damages a Stuart property. The policyholder should contact the insurer as soon as it is safe, using the designated claims number or online portal. The initial notice should identify the property, describe the general type of damage, and state when the event occurred. The insurer typically assigns a claim number and adjuster, then explains required procedures, deadlines, and next steps. Prompt communication can help the insurer arrange an inspection and assess urgent needs. If the property is unsafe or uninhabitable, the policyholder should ask whether Temporary housing benefits may apply. Emergency repairs may be necessary to prevent further harm, but the insurer should be notified beforehand when circumstances permit. Clear, timely reporting supports an orderly claim process and helps protect occupants.
Documenting Your Losses
Careful documentation helps establish the extent and cause of storm damage to a Stuart property. Owners can photograph and video affected rooms, exterior features, and damaged belongings before cleanup, provided it is safe to do so. Images should show both close details and the overall condition of each area. A dated Personal property inventory can identify damaged or missing items, including descriptions, approximate purchase dates, and available receipts or warranty records. Keeping damaged items until they are documented may also help preserve evidence, unless removal is necessary for safety or sanitation. Owners displaced by unsafe conditions should maintain temporary housing records, such as lodging receipts, meal expenses, and transportation costs. Organized files, repair estimates, and communications with contractors can create a clear account of losses and support those assisting the household.
Reviewing the Claim
Once you document and report losses, the insurer begins reviewing the storm damage claim. An adjuster may inspect the property, examine photographs and repair estimates, and compare the reported damage with policy terms. The review can consider when the damage occurred, whether it resulted from a covered weather event, and whether exclusions or deductibles apply. Coverage interpretation is central because policy language determines which repairs may qualify for payment and what documentation is required. The property owner should provide complete, accurate records and respond promptly to reasonable requests. The insurer may also explain appraisal options if an independent assessment is appropriate under the policy. At this stage, careful review helps ensure the claim reflects the documented loss and applicable coverage. A written decision should identify the insurer’s findings and calculations.
Resolving Disputes
When a storm damage claim is disputed, the property owner may need to address disagreements over coverage, repair costs, or the cause of the loss. The insurer may request records, inspections, or statements to evaluate the evidence. Organized photographs, contractor estimates, policy documents, and dated communications can help clarify the issues and support a complete review.
If direct discussions do not resolve the dispute, Mediation Options may provide a structured setting for the parties to seek agreement with help from a neutral facilitator. The Appraisal Process may address disagreements about the amount of loss when the policy permits it, though it generally does not decide coverage questions. A property owner may consult a qualified attorney to understand applicable deadlines, policy terms, and available procedures. Timely, careful action can help protect the claim and support a fair resolution.
Compensation for Stuart Property Claim Storm & Weather Damage Injury Damages
Compensation for storm and weather damage to property in Stuart may cover reasonable repair or replacement costs, related expenses, and other losses allowed under the insurance policy and Florida law. The available amount depends on the policy’s terms, the cause and extent of damage, and the evidence supporting the claim. Covered losses may include damage to roofs, windows, interiors, and personal property, as well as necessary costs to prevent further harm or arrange temporary housing when the policy provides for it.
Policyholders should review Coverage limits, exclusions, deductibles, and deadlines before accepting a payment. Estimates, photographs, invoices, and professional assessments can help establish the scope and value of repairs. If the insurer’s valuation differs from the owner’s documented estimate, appraisal clauses may provide a process for resolving disagreements about the amount of loss, subject to the policy’s requirements. A careful review can help ensure payments reflect covered damage and that funds support safe, complete restoration of the property.
Economic vs. Non-Economic Damages in Stuart Property Claim Storm & Weather Damage Cases
Storm and weather claims may involve economic damages, such as repair costs, temporary housing expenses, and losses to personal property. Non-economic losses may also arise, though their availability depends on the claim and applicable law. Clear records and supporting evidence help establish the nature and value of the damages sought.
Economic Damage Costs
In Stuart property claims involving storm or weather damage, economic damages are the measurable financial losses caused by covered damage, while non-economic damages generally concern personal harm rather than repair costs. These costs may include reasonable expenses to repair or replace damaged roofs, walls, flooring, equipment, and personal property. Owners may also document Temporary housing expenses when covered damage makes a residence unsafe or uninhabitable. For commercial properties, business interruption losses may include reduced revenue and necessary operating expenses during repairs, subject to policy terms and proof. Receipts, estimates, invoices, photographs, and financial records can help establish the amount and cause of each claimed loss. A careful accounting supports accurate review and helps property owners pursue benefits available under their insurance contracts while preserving resources needed for household stability and community service.
Non-Economic Losses
Beyond repair bills and other measurable expenses, non-economic losses refer to personal harm rather than financial costs. After a storm damages a home, residents may experience Emotional distress, disruption, and uncertainty that affect daily life. The loss of familiar surroundings can interfere with rest, privacy, and a sense of security, particularly while repairs or temporary relocation continue. Loss of enjoyment may arise when damaged property prevents residents from using living spaces, gardens, or other areas as they ordinarily would. These effects differ from economic damages, which concern expenses such as repairs, replacement items, or additional housing costs. Non-economic harm is personal and does not have a simple price tag. In property claims, whether such losses are recoverable depends on the policy, applicable law, and circumstances of the claim. Each situation requires individual consideration.
Proving Your Damages
A well-supported property claim connects each reported loss to the storm damage and documents its value. Economic damages may include repair costs, damaged belongings, temporary housing, and other event-related expenses. A detailed Damage inventory should identify each item, its condition, age, and replacement or repair cost. Photographs, contractor estimates, receipts, and proof of payment can help establish both the damage and its financial impact.
Insurers may subtract depreciation from the initial payment, making depreciation recovery important when the policy allows withheld amounts to be claimed after repairs or replacement. Records showing completed work and actual costs can support that request. Non-economic losses, such as disruption and stress, are generally distinct from property expenses and may not be covered under a standard policy. Clear, organized evidence helps adjusters assess the claim fairly and enables policyholders to pursue benefits that support their households and communities.
Don’t Wait. Call Our Florida Personal Injury Lawyers Now!
When a Stuart Property Claim Storm & Weather Damage Injury Case Goes to Trial vs. Settlement
Whether a storm-damage property claim is resolved through settlement or proceeds to trial depends on the evidence, the insurer’s position, and the disputed value of the loss. Settlement Negotiations may provide a practical way to address disagreements over repair costs, covered damage, or payment timing. The parties can compare estimates and supporting records, then decide whether an agreed amount fairly reflects the documented loss. A settlement can avoid the uncertainty, expense, and delay associated with a courtroom proceeding.
If negotiations do not produce an acceptable resolution, the property owner may pursue the claim at trial. Each side presents evidence and arguments, and a judge or jury evaluates the disputed issues. Jury Deliberations follow the presentation of evidence and determine the outcome when a jury hears the case. Trial preparation can require substantial time and careful organization of inspections, photographs, invoices, and expert opinions. The appropriate path depends on the claim’s circumstances and whether a fair agreement can be reached. Both approaches aim to resolve the dispute responsibly.
Florida Laws That May Affect Your Stuart Property Claim Storm & Weather Damage Case
Florida law can shape how a Stuart property owner reports, documents, and pursues a storm or weather damage claim. The applicable policy and state requirements may affect notice, proof, inspections, and dispute resolution. Careful compliance can help owners protect their property while limiting disruption to household members, tenants, and others who rely on the premises.
Relevant considerations may include:
- Prompt notice: Policy terms may require timely reporting and cooperation with the insurer.
- Evidence preservation: Photographs, repair records, and damaged materials can support an accurate assessment.
- Mitigation duties: Reasonable steps to prevent further damage may be required, without risking personal safety.
- Florida claim deadlines: Statutory and policy deadlines can govern claim submissions and supplemental information.
- Policy appraisal rights: Appraisal provisions may offer a process for resolving disagreements about the amount of loss.
Requirements vary by policy, loss date, and circumstances. A qualified professional can review applicable rules, explain available options, and help the owner communicate clearly with insurers while considering the needs of everyone affected by the damage.
The Statute of Limitations for Stuart Property Claim Storm & Weather Damage Injury Cases
When must a storm-related injury claim be filed? For a Florida property damage claim, the applicable deadline depends on the policy, the date of loss, and the type of dispute. Florida law generally requires filing a residential property insurance claim within one year of the date of loss, with limited exceptions. A supplemental claim generally must be filed within 18 months. These statutory periods are separate from any Policy deadline stated in the insurance contract, including requirements to give prompt notice, document damage, or submit proof of loss.
A dispute over the amount of covered damage may involve an appraisal clause, but invoking appraisal does not necessarily pause every legal deadline. The applicable limitation period can also depend on whether the case concerns breach of contract or another claim. Missing a filing deadline may prevent recovery, even when storm damage is well documented. Property owners should preserve records and promptly confirm the dates and requirements that govern their claim, so resources remain available to support household recovery and community needs.
How a Stuart Property Claim Storm & Weather Damage Lawyer Can Help You
After a storm damages a home or business, a Stuart property claim storm and weather damage lawyer can help the owner understand policy requirements, organize supporting evidence, and communicate with the insurer. This support can help ensure a fair review while helping property owners protect the safety and stability of their households, employees, and communities.
A lawyer may provide practical guidance by:
- Reviewing policy language and explaining Policy interpretation in clear terms.
- Identifying coverage exclusions that may affect the reported loss.
- Organizing photographs, repair estimates, receipts, and other claim records.
- Preparing written responses to insurer questions and requests.
- Evaluating whether the insurer’s assessment reflects the documented damage.
Careful documentation can help distinguish storm-related damage from preexisting conditions and clarify the scope of necessary repairs. Counsel may also compare estimates, explain disputed claim decisions, and outline available options under the policy. By presenting information accurately and consistently, a lawyer can help the owner pursue a claim without losing sight of responsibilities to family members, tenants, customers, or neighbors affected by the damage.
When to Contact a Stuart Property Claim Storm & Weather Damage Lawyer
Prompt legal guidance may be valuable when storm damage is extensive, the insurer delays its review, or the claim is denied or underpaid. A property owner may also contact counsel when the scope of repairs is disputed, payment does not reflect documented losses, or the insurer requests information that is difficult to assemble. Early consultation can help clarify available options while the owner continues protecting occupants and preventing further damage.
A Policy review may be useful before filing, after receiving a reservation of rights letter, or when coverage terms are unclear. Counsel can assess whether the reported damage and requested benefits align with the policy language and claim record. Property owners should also ask about coverage deadlines, including notice requirements, proof-of-loss dates, and any applicable appeal or lawsuit time limits. These periods can differ by policy and circumstances, so prompt attention matters. Keeping photographs, repair estimates, receipts, and insurer communications organized can support an informed discussion and help the owner make timely decisions for the property and those who depend on it.
Why You Need an Experienced Stuart Property Claim Storm & Weather Damage Lawyer
An experienced Stuart property claim storm and weather damage lawyer can help property owners manage disputes that require careful interpretation of policy terms and claim evidence. Storm losses may involve roof damage, flooding, wind, or other conditions, and insurers may question the cause, scope, or value of repairs. Skilled counsel can organize documentation, assess damage evidence, and explain how coverage provisions apply to the reported loss.
Policy interpretation is central when exclusions, deductibles, deadlines, or duties after a loss affect a claim. An attorney can identify relevant terms and address disputes with clear, evidence-based communication. Attorney experience also helps counsel recognize common claim issues, evaluate insurer explanations, and determine whether additional inspections or records may clarify the loss.
For property owners seeking a fair resolution, informed legal support can reduce confusion and help protect resources needed for repairs. Counsel can explain available options and represent the owner’s interests while keeping the process focused on accurate facts, policy obligations, and a practical outcome.
How to Choose the Right Stuart Property Claim Storm & Weather Damage Lawyer for Your Case
Choosing the right Stuart property claim storm and weather damage lawyer requires careful consideration of the attorney’s experience with insurance disputes, familiarity with relevant policy terms, and ability to assess claim evidence. A careful selection can help property owners pursue fair treatment while protecting the resources their families, employees, or communities depend on.
Prospective clients can review Attorney credentials, including bar admission, relevant training, and experience handling storm-related property claims. They may also ask how the lawyer evaluates damage documentation, communicates with insurers, and explains available options. Clear answers can indicate whether the attorney’s approach aligns with the client’s needs and priorities.
Discuss fee structures before representation begins. The lawyer should explain how fees and case expenses are calculated, when payment is due, and what costs may arise if the claim does not succeed. Comparing these terms alongside experience and communication practices can support an informed decision. A suitable attorney should provide realistic expectations and a clear process for moving the claim forward.
About The Law Offices of Anidjar & Levine
For property owners evaluating legal representation, The Law Offices of Anidjar & Levine provides legal services to clients dealing with storm and weather damage claims in Florida. The firm represents individuals and families seeking assistance after property losses, helping them understand claim procedures and communicate with insurers. Its work may include reviewing policy terms, reviewing claim documentation, and pursuing disputes when coverage or payment is contested.
Firm history offers context for evaluating a law office, but prospective clients should also consider how its services align with their circumstances. The firm handles matters across Florida and can explain available legal options during an initial consultation. Attorney credentials, including relevant experience and professional standing, are important factors for clients to review when selecting counsel. Property owners can ask about the attorney responsible for their case, expected communication, and potential costs before proceeding. For those who value service to others, clear guidance can help families make informed decisions while addressing repairs, financial pressures, and the practical demands that follow severe weather damage.
Frequently Asked Questions
Does Homeowners Insurance Cover Flood Damage in Stuart?
Homeowners insurance in Stuart generally does not cover flood damage caused by rising water, heavy rainfall, or storm surge. You may need separate flood insurance, often through the National Flood Insurance Program or a private insurer. Flood insurance requirements may apply when a property is in a high-risk flood zone and has a federally backed mortgage. Storm surge coverage depends on the policy’s definitions and exclusions, so policyholders should review terms promptly.
Can I File a Claim if My Roof Was Damaged by a Named Storm?
A homeowner may file an insurance claim if a named storm damaged the roof, subject to the policy’s coverage, exclusions, and reporting requirements. The insurer will assess whether wind or another covered peril caused the damage, rather than wear, neglect, or an excluded flood. Prompt roof damage documentation, including dated photographs, repair estimates, and records of temporary protective measures, can support review. The homeowner should also confirm named storm deadlines and follow the policy’s notice procedures.
What if My Insurer Says the Damage Was Caused by Wear and Tear?
An insurer’s wear-and-tear decision may be challenged if storm damage contributed to the loss or the evidence does not support the denial. A careful Policy language review can clarify coverage, exclusions, and deadlines. The property owner should preserve photographs, inspection reports, repair estimates, and maintenance documentation, then request the insurer’s written findings. An independent inspection may help distinguish gradual deterioration from sudden storm damage and support a timely appeal or further claim review.
Can I Hire a Public Adjuster to Inspect My Storm-Damaged Property?
Yes, a property owner may hire a public adjuster to inspect storm damage and help document a claim. The adjuster can assess visible conditions, review policy terms, and prepare an estimate, but cannot guarantee coverage or payment. Confirm public adjuster inspection costs and fee arrangements in writing before work begins. The owner should verify the adjuster’s licensing requirements with the relevant state regulator and retain copies of inspection findings.
Will Filing a Storm Damage Claim Affect My Homeowners Insurance Premiums?
Filing a storm damage claim may affect homeowners insurance premiums, but an increase is not automatic. Insurers consider claim frequency, the severity and cause of damage, prior claims, and regional loss trends when setting rates. A premium may rise at renewal, while some weather-related losses are treated differently under state rules or policy terms. The homeowner should review coverage, document damage carefully, and ask the insurer how a claim could affect future rates.
—————————
Storm and weather damage claims can involve disputed coverage, delayed payments, and costly repairs. Property owners in Stuart should document the damage, review their policy, and observe all notice and filing deadlines. When an insurer questions a claim or offers inadequate compensation, experienced legal counsel can assess the evidence and explain the owner’s options. The Law Offices of Anidjar and Levine assists clients with property insurance disputes and works to pursue fair outcomes under their policies. Learn more about a Stuart Personal Injury Lawyer.