A Port St. Lucie property claim storm and weather damage lawyer can review policy terms, assess disputed damage, and help property owners pursue benefits for covered losses. The Law Offices of Anidjar and Levine can assist when severe winds, rain, hail, or falling debris damage roofs, interiors, or critical systems. Because hidden moisture may cause further problems, dated photographs, repair estimates, weather records, and insurer communications can help document a claim. Legal counsel may also address delays, inadequate payments, or denials. Learn more about a Port St. Lucie Personal Injury Lawyer. The following sections explain important steps and considerations.
Main Takeaways
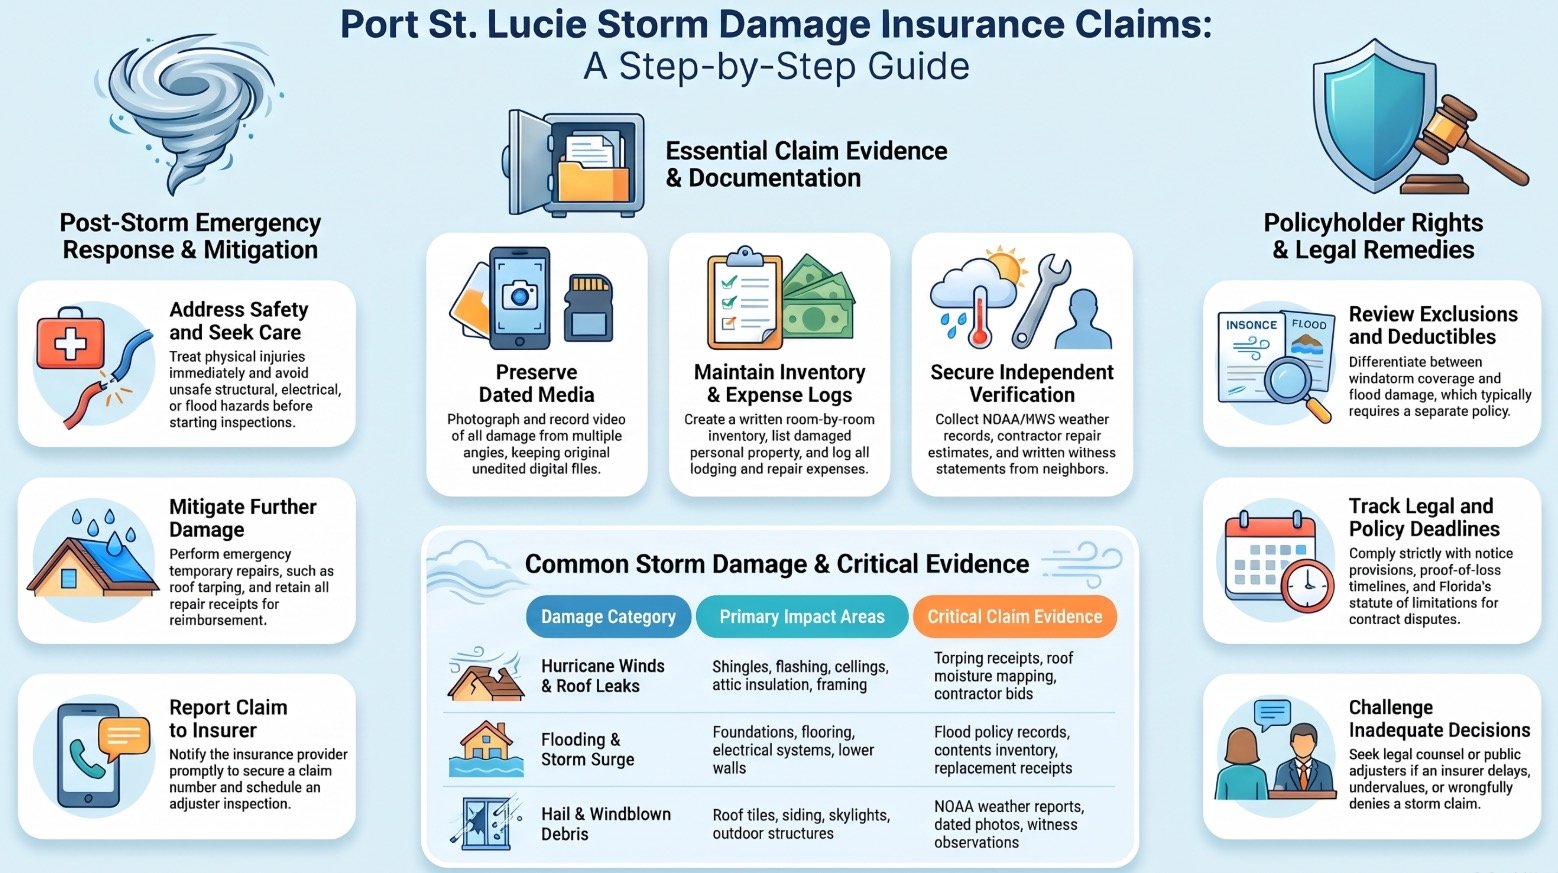
- A Port St. Lucie property-claim lawyer can review your policy, storm-damage evidence, and the insurer’s coverage decision.
- Photograph damage, preserve original files, and keep repair estimates, invoices, receipts, and weather records.
- Arrange a qualified inspection to identify roof leaks, hidden structural damage, and moisture-related concerns.
- Take reasonable steps to prevent further damage, such as emergency tarping, and retain related receipts.
- Coverage depends on policy terms and evidence; consult a Florida attorney about claim deadlines and dispute options.
How We Can Help With Your Port St. Lucie Property Claim Storm & Weather Damage Injury Claim
After a storm damages a home or business in Port St. Lucie, property owners may face urgent repairs, disrupted operations, and uncertainty about insurance coverage. A property damage lawyer can help organize the claim process and protect the owner’s interests while keeping practical needs in view. The lawyer may review the policy, assess the insurer’s decision, and explain available options through careful policy interpretation. This guidance can help identify covered losses, applicable deadlines, and documentation needed to support a claim.
When an insurer disputes damage, delays payment, or offers less than the documented loss, counsel can communicate with the company and present evidence supporting the owner’s position. Claim denial appeals may be prepared when a denial appears inconsistent with the policy or the available records. The lawyer can also help obtain estimates, repair records, photographs, and other relevant materials. By addressing these tasks methodically, legal counsel can reduce confusion and help property owners pursue a fair resolution without losing sight of recovery and community responsibilities.
Don’t Wait. Call Our Florida Personal Injury Lawyers Now!
Understanding Port St. Lucie Property Claim Storm & Weather Damage Injury Cases
Storm and weather damage claims in Port St. Lucie may involve more than documenting visible harm to a home or other property. Each case depends on the policy language, the evidence available, and the insurer’s handling of the reported loss. A careful review can clarify which repairs may be covered and what steps are required to support a claim.
OUR CONSULTATIONSARE FREE
START YOUR FREE CASE REVIEW
Policyholders generally benefit from preserving photographs, repair estimates, receipts, and communications with the insurer. These records can help establish the property’s condition, the scope of the damage, and the expenses incurred. Coverage exclusions may limit payment for certain losses, so the specific policy terms require close attention. Claim deadlines also matter; delayed notice or incomplete submissions may affect a policyholder’s ability to obtain benefits.
A qualified legal review can help identify disputed coverage issues, assess whether the insurer followed its obligations, and explain available options. Clear guidance may help property owners make informed decisions while protecting their interests and restoring safe, functional spaces for those who depend on them.
Common Causes of Port St. Lucie Property Claim Storm & Weather Damage
Storm and weather claims in Port St. Lucie commonly arise from hurricane-force winds that damage roofs, siding, and other parts of a property. Roof leaks and flooding, including storm surge, may cause significant interior damage and complicate insurance claims. Hail and falling debris can also damage structures and belongings, making accurate documentation important.
Hurricane Wind Damage
When a hurricane brings sustained winds and powerful gusts to Port St. Lucie, buildings and surrounding property can face significant stress. Hurricane wind patterns may shift rapidly, creating pressure differences that affect walls, windows, doors, and exterior structures. Flying branches, signs, and other debris can strike surfaces, while falling trees may damage fences, vehicles, and outdoor equipment. These impacts can disrupt homes, businesses, and community services that residents rely on after a storm.
Property owners may reduce some risks through regular maintenance, securing outdoor items, and wind-resistant landscaping suited to local conditions. After a hurricane, carefully document visible damage and report it promptly to the insurer to clarify the scope of a claim. A qualified property claim professional can assess evidence, review policy terms, and support a fair evaluation for affected owners.
Roof Leak Claims
Heavy rain and strong winds can expose roof weaknesses, allowing water to enter through damaged shingles, loose flashing, worn sealants, or blocked drainage systems. Once inside, moisture may stain ceilings, damage insulation, and weaken interior materials. A prompt inspection can help identify the entry point and limit further deterioration. Roof Leak Detection may involve examining roof surfaces, attic spaces, and areas around vents or chimneys for signs of moisture. Property owners should document visible damage and take reasonable steps to protect belongings without creating safety risks. Emergency Tarping can temporarily cover an exposed section until qualified repairs are completed. Accurate records of repair estimates, photographs, and communications with the insurer can support a claim. A property damage attorney may help clarify coverage and address disputes about the cause or extent of roof damage.
Flooding And Storm Surge
Flooding and storm surge can cause extensive property damage in Port St. Lucie, especially when heavy rain coincides with high tides or tropical weather. Stormwater drainage systems may become overwhelmed, allowing water to collect in streets, yards, and buildings. Coastal inundation can also push water inland, damaging foundations, flooring, electrical systems, and personal belongings. Even shallow flooding may leave hidden moisture that contributes to mold growth and structural deterioration. Property owners should document visible damage, take reasonable steps to limit further loss, and retain receipts for temporary repairs. Insurers may dispute whether damage resulted from flooding, wind-driven rain, or another covered event, making clear records important. Carefully review policy terms, exclusions, and claim evidence to help affected owners pursue benefits and support timely repairs for their households and communities.
Hail And Falling Debris
Hail and windblown debris can damage Port St. Lucie homes and businesses during severe storms. Hail impact may crack roof tiles, puncture shingles, dent metal panels, and break windows or skylights. Even when damage appears minor, water can enter through weakened areas and affect insulation, ceilings, electrical systems, or personal property. Prompt inspection helps identify concealed problems before they worsen.
Debris hazards include branches, roofing materials, and other objects carried by strong winds. These may strike structures, block drainage, or damage fences, vehicles, and outdoor equipment. Property owners who document visible damage, preserve relevant records, and arrange reasonable temporary protection can support a clear claim review. A qualified professional can assess the affected areas and explain available options. Careful attention to safety and accurate reporting can help property owners pursue repairs while protecting occupants and neighbors.
Legal Rights of Port St. Lucie Property Claim Storm & Weather Damage Injury Victims
When a storm or other severe weather damages property in Port St. Lucie, policyholders have rights under their insurance contracts and Florida law. They may report covered losses, submit supporting evidence, and expect the insurer to investigate and communicate its decision fairly and promptly. Policyholder rights also include reviewing the policy, requesting explanations for claim decisions, and challenging inadequate denials or payments.
Port St. Lucie policyholders can document storm damage, seek clear claim decisions, and challenge inadequate denials or payments.
Important protections and responsibilities include:
- Providing timely notice and reasonable documentation of the damage.
- Receiving a clear explanation of covered benefits and claim determinations.
- Reviewing Coverage exclusions and policy limits before accepting a settlement.
- Seeking legal guidance when disputes arise over coverage or payment.
A policyholder should preserve relevant records, photographs, repair estimates, and communications. The insurer must assess the claim according to the policy terms and applicable requirements, rather than dismissing it without a reasonable review. When disagreements persist, a qualified attorney can explain available remedies and help the claimant pursue a fair resolution. This process can also help households restore safe, stable homes for their families and neighbors.
Why Do Port St. Lucie Property Claim Storm & Weather Damage Injuries Happen?
Why do storm-related property claims arise in Port St. Lucie? Severe winds, heavy rain, flooding, and lightning can damage roofs, windows, siding, and vital systems. These conditions may also create hazards for occupants, visitors, and workers, including falling debris, electrical exposure, and slippery surfaces. The resulting losses often involve both physical damage and disruption to daily life.
Some damage stems from vulnerabilities that existed before a storm. Aging materials, inadequate maintenance, or poor drainage can leave a property less able to withstand intense weather. Building code compliance also matters because construction that fails to meet applicable standards may offer insufficient protection against wind or water intrusion. In other cases, contractor negligence, such as improper installation or repairs, can contribute to structural failures or worsen storm damage. Carefully assessing these factors can help clarify how a loss occurred and identify measures that support safer properties and stronger protection for the wider community.
What Should You Do After a Port St. Lucie Property Claim Storm & Weather Damage Injury?
After a storm-related injury, the affected person should seek prompt medical care and follow the provider’s recommendations. They should document the damage with photos, records, and receipts, and avoid unsafe areas. Once they address immediate needs, they should contact their insurer to report the loss and ask about the claims process.
Seek Medical Care
Anyone injured by storm-related property damage in Port St. Lucie should seek medical care promptly, even when symptoms appear minor. Falling debris, broken glass, flooding, and structural failures can cause injuries that worsen without timely assessment. A medical professional can identify hidden trauma, recommend appropriate treatment, and explain follow-up care. In a life-threatening emergency, the injured person or a nearby helper should call 911 and avoid moving the person unless immediate danger requires it. After addressing urgent needs, individuals should follow clinicians’ instructions and attend recommended appointments. Those displaced by unsafe conditions may need an Emergency shelter while recovering, and family members or neighbors can help arrange transportation and emotional support. Prompt care protects health and helps prevent complications, while allowing injured people to focus on recovery and their families’ immediate needs.
Document the Damage
Once immediate medical needs are addressed, documenting storm damage can help preserve an accurate record of the incident and resulting losses. The property owner should photograph and video affected areas before cleanup or repairs, when conditions permit. Images should show damage from several angles and include identifying details, such as room locations and damaged materials. A written Room inventory can list each affected space, describe visible damage, and note the date it was observed. Personal belongings should be recorded individually, with photographs, purchase receipts, or other available proof of value. The owner should also keep copies of repair estimates, cleanup expenses, and temporary lodging costs. Store records securely, with backups kept separately. Careful documentation can help clarify the scope of loss and support accurate decisions while the property is restored.
Contact Your Insurer
Once immediate safety concerns are addressed and damage is documented, the property owner should promptly notify the insurer of the storm-related loss. Early notice can help prevent delays and maintain a clear claim record. The owner should provide the storm date, describe the observed damage, and share photographs or other available documentation without speculating about the cause or cost of repairs. During the call, the owner should request a claim number, confirm required forms, and ask when an adjuster may inspect the property. A careful Policy review can clarify reporting duties, exclusions, and coverage limits relevant to the loss. The owner should keep copies of all communications and record names, dates, and instructions. Accurate, timely cooperation supports fair evaluation and helps protect resources needed for recovery.
Critical Evidence in a Port St. Lucie Property Claim Storm & Weather Damage Injury Case
A well-supported storm damage claim depends on evidence that documents the loss, its timing, and its impact.
Relevant materials may include:
- Dated photographs of the damage
- Records of the weather event
- Repair estimates
- Witness statements
Together, these records can help clarify the cause and extent of the property damage.
Dated Damage Photographs
Dated photographs can provide vital evidence in a Port St. Lucie property damage claim by showing the condition of a home or business after a storm. Images may document roof openings, fallen branches, water intrusion, damaged belongings, and safety hazards. A clear sequence can help establish when you observed the damage and how it changed during cleanup or repairs. Photo metadata may record capture dates and other details, but preserve and review those details rather than assuming they prove every fact. Image preservation includes keeping original files, maintaining backups, and avoiding edits that could obscure relevant conditions. Take photographs from safe locations, and don’t delay urgent measures to protect occupants or prevent further loss. Organized, accurate images can help property owners, insurers, and professionals assess damage and support a fair claim.
Weather Event Records
After a storm, weather event records can help establish the conditions that may have caused property damage in Port St. Lucie. These records can identify when severe weather occurred and document reported wind speeds, rainfall, hail, or other relevant conditions. The National Weather Service archives may provide forecasts, warnings, and observations that help place the event in context. NOAA storm reports can offer additional accounts of storm impacts, including reports from trained observers and the public. Collectively, these sources may support a timeline connecting a weather event to observed damage. Their value depends on accuracy, location, and timing, so compare records with dated photographs and other available evidence. Careful documentation can help property owners present a clearer account of what occurred and help reviewers evaluate relevant circumstances.
Repair Estimates
When storm damage requires repairs, written estimates can help show the work needed to restore a property and the likely cost. Detailed estimates may identify damaged materials, proposed repairs, labor, and expected expenses. These records can help clarify whether a claim accounts for the full extent of covered damage. Contractor bids from qualified professionals may provide useful support, particularly when they explain the basis for recommended work and pricing. Scope comparisons can reveal differences between a contractor’s proposed repairs and an insurer’s assessment, including items that may have been overlooked or valued differently. Keeping estimates, invoices, and related documentation organized supports a fair review and helps property owners make informed decisions. Clear repair records also support those seeking to protect homes, businesses, and the people who depend on them during recovery.
Witness Statements
Repair estimates document the proposed scope and cost of restoring storm-damaged property, while witness statements can provide an independent account of what happened and when. Neighbors may describe the storm’s timing, visible damage, or conditions before and after the event. These Neighbor observations can help establish whether damage appeared suddenly or developed over time. Contractors who inspected the property may explain what they found, which repairs were necessary, and whether the damage was consistent with reported weather conditions. Contractor testimony can clarify technical findings in accessible terms and connect them to the proposed work. Statements are most useful when recorded promptly, with dates, contact information, and specific observations. A consistent, factual account may help insurers, adjusters, and legal professionals evaluate a claim fairly and understand the property owner’s circumstances.
Don’t Wait. Call Our Florida Personal Injury Lawyers Now!
Long-Term Effects of Port St. Lucie Property Claim Storm & Weather Damage Injuries
Storm and weather damage can leave persistent structural problems that remain hidden after initial repairs. Lingering moisture may contribute to mold growth and related health effects, while recurring damage can increase repair costs over time. These long-term consequences may affect both the property’s safety and the owner’s financial recovery.
Persistent Structural Damage
Persistent structural damage can continue long after a storm has passed, particularly when water intrusion, wind pressure, or falling debris weakens a property’s foundation, framing, roof, or load-bearing walls. Foundation settlement may cause sloping floors, widening cracks, or doors and windows that no longer close properly. Load-bearing deterioration can reduce a building’s stability and create risks for residents, workers, and visitors. These conditions may worsen when repairs are delayed or limited to visible surfaces rather than underlying damage. A qualified inspection can document affected components, identify necessary repairs, and help determine whether the property remains safe to occupy. Clear records, photographs, and professional assessments may also support a property claim. Timely attention protects occupants and helps preserve the building for those who depend on it.
Mold-Related Health Effects
Structural damage can also trap moisture in walls, flooring, and insulation, creating conditions for mold growth after severe weather. If you don’t identify and address damp materials, mold may spread into occupied areas and affect indoor air quality. Exposure can cause Respiratory symptoms, including coughing, wheezing, nasal congestion, or throat irritation. Mold spores may also trigger allergies, worsening symptoms for people with asthma, allergies, or other sensitivities. Effects can persist as long as exposure continues, and some individuals may experience more serious reactions than others. Property owners should take reports of musty odors, visible growth, or recurring symptoms seriously and arrange appropriate inspection. Prompt attention can help protect residents, visitors, and workers, especially children and people with existing respiratory conditions, from avoidable exposure and lasting health concerns.
Ongoing Repair Costs
When storm or weather damage is not fully repaired, costs can continue long after the initial event. Delayed repairs may allow water intrusion, structural deterioration, or electrical problems to worsen, increasing the work and materials needed to restore a property. Owners may also face Temporary housing expenses when unsafe conditions prevent them from returning home. Utility bills can rise if damaged systems operate inefficiently or if equipment must run longer to control moisture and maintain safe conditions. For households already managing disruption, these added costs can strain budgets and affect their ability to support family members or others who depend on them. Careful records of invoices, repair estimates, lodging, and utility expenses can help document the continuing financial impact. Prompt assessment may limit further damage and clarify the scope of necessary repairs.
Proving Liability in Port St. Lucie Property Claim Storm & Weather Damage Injury Cases
Proving liability in a Port St. Lucie property damage case begins with establishing what caused the loss and whether the policy covers it. Storm evidence, dated photographs, repair records, weather reports, and qualified inspections can help distinguish sudden damage from prior deterioration or maintenance issues. A clear timeline may show when damage occurred and how it affected the property.
The policy’s terms also matter. Policy exclusions may limit coverage for particular causes, while endorsements can change the scope of protection. The policyholder generally must support the claim with evidence of covered damage, but burden allocation can vary by policy language and the specific issue in dispute. Careful review helps identify which party must establish whether an exclusion applies.
Accurate documentation serves more than a financial purpose; it can help restore safe, usable housing and protect residents from continuing hazards. Independent assessments and preserved records can clarify disputed facts without speculation. Each claim depends on its evidence, policy wording, and applicable Florida law.
Dealing With Insurance Companies After a Port St. Lucie Property Claim Storm & Weather Damage Injury
After documenting the cause and extent of storm damage, a property owner must communicate with the insurer in a way that preserves an accurate claim record. Clear claim communication helps ensure reports, photographs, repair estimates, and relevant dates are considered together. The owner should provide complete, factual information and keep copies of submitted materials, correspondence, and call notes. Prompt responses can prevent avoidable misunderstandings, while carefully reviewing insurer questions can reduce the risk of inaccurate statements.
Policy exclusions and coverage limits may affect whether particular damage is covered. The owner should compare the insurer’s explanation with the policy language and request clarification when a decision appears inconsistent with the documented conditions. If the property serves tenants, customers, or community members, timely updates and reasonable safety measures can help protect others while repairs are assessed. A qualified attorney may review disputed coverage issues and explain available options. Consistent records and measured communication support a fair evaluation without overstating the claim.
What to Expect During a Port St. Lucie Property Claim Storm & Weather Damage Injury Claim Process
A storm or weather damage claim typically begins with an initial review of the policy, reported losses, and available evidence. The property owner may need to document damage while the insurer investigates the cause and extent of the loss. The process may conclude with a settlement or proceed to litigation if the parties cannot resolve the dispute.
Initial Claim Review
During the initial claim review, the insurer evaluates the reported storm damage, the policy terms, and the available evidence to determine how the Port St. Lucie property claim should proceed. This stage generally includes a Policy review to identify applicable provisions, exclusions, deductibles, notice requirements, and deadlines. A coverage analysis then considers whether the reported cause of loss falls within the policy’s protection and whether any limits or conditions may affect payment. The insurer may request clarification about the claim or explain what information is needed before reaching a decision. Property owners can review correspondence carefully and respond within stated timeframes to help keep the process moving. When questions arise about policy language or claim handling, a qualified professional may explain available options and support informed decisions that protect the property and those who depend on it.
Damage Documentation
Clear damage documentation helps establish the scope and cause of storm-related losses as the Port St. Lucie property claim process moves forward. The property owner or representative can record affected areas with dated photographs, video, and written notes before cleanup or repairs alter the evidence. Records should identify visible damage, the date it was discovered, and any steps taken to prevent further loss. Moisture mapping can show where water has spread and help distinguish damp areas from unaffected spaces. A detailed contents inventory should list damaged belongings, their approximate age, purchase information when available, and condition. Receipts, repair estimates, and maintenance records may provide additional support for reported losses. Organized documentation can help ensure claim materials accurately reflect the property’s condition and the practical needs of those affected.
Insurer Investigation
Once a storm-related property claim is filed, the insurer typically investigates to assess the reported damage and determine whether the policy covers the loss. An adjuster may contact the property owner to arrange an inspection and review the damage documentation, photographs, repair estimates, and other relevant records. During the Adjuster inspection, the adjuster may examine affected areas, ask questions about when the damage occurred, and note conditions that could affect the claim. The property owner may identify visible damage and provide access to relevant parts of the building. The insurer then conducts a coverage analysis, comparing the reported loss with policy terms, exclusions, limits, and applicable deductibles. The insurer may request additional information or expert assessments when the damage is complex or the cause remains uncertain. Clear, timely cooperation can help the insurer evaluate the claim accurately.
Settlement Or Litigation
After the insurer completes its investigation and evaluates coverage, the claim may proceed to settlement or, if the parties disagree, litigation. During settlement discussions, the property owner may present repair estimates, photographs, expert assessments, and records of related expenses. The insurer may make an offer, request further documentation, or dispute the scope and value of the damage. Careful preparation can strengthen Settlement leverage and support a resolution that reflects documented losses. If negotiations fail, litigation may allow a court to assess the evidence and determine the parties’ obligations. A sound litigation strategy considers deadlines, available evidence, potential costs, and the owner’s practical objectives. Throughout either path, clear communication helps the owner make informed decisions while preserving resources needed to restore the property and serve household or community needs.
Compensation for Port St. Lucie Property Claim Storm & Weather Damage Injury Damages
Storm and weather damage claims may cover more than the cost of repairing a home or replacing belongings. Depending on the policy and the circumstances, compensation may include reasonable expenses for temporary housing, debris removal, emergency protection, and repairs needed to prevent additional damage. A claim may also address damaged personal property and other losses directly connected to a covered storm event.
The amount available depends on policy limits, deductibles, exclusions, and the insurer’s assessment of the loss. Policy exclusions may restrict recovery for certain causes or types of damage, while appraisal disputes can arise when the insurer and property owner disagree about repair costs or the extent of covered damage. Documentation, including photographs, repair estimates, receipts, and inspection reports, can help clarify the claim and support a fair review. Property owners who assist family members, neighbors, or other affected residents may benefit from understanding these requirements before making decisions on their behalf. A qualified professional can review the policy and explain available options.
Economic vs. Non-Economic Damages in Port St. Lucie Property Claim Storm & Weather Damage Cases
Storm and weather damage claims may include economic losses, such as repair costs, damaged belongings, and temporary housing expenses. They may also include non-economic impacts, such as disruption to daily life and loss of use of the property. Clear documentation helps establish the nature and extent of both categories of damages.
Economic Property Losses
Economic property losses are the measurable financial costs caused by storm or weather damage to a home or other property in Port St. Lucie. They may include reasonable repair or rebuilding expenses, the cost to replace damaged belongings, and payments for temporary housing while the property is unsafe or uninhabitable. Owners may also document Lost rental income when storm damage prevents tenants from occupying a rental property. For commercial properties, business interruption losses may include reduced revenue and necessary operating expenses during repairs. Claims generally require records that connect each requested amount to the covered damage, such as contractor estimates, invoices, receipts, lease agreements, tax documents, and financial statements. A careful review can help property owners present complete information to insurers and pursue compensation for verified, policy-covered financial losses.
Non-Economic Impacts
Beyond repair bills and other measurable costs, property damage can disrupt daily routines, create uncertainty, and place strain on occupants. In Port St. Lucie, storm-related damage may make rooms unsafe, interrupt access to necessary belongings, or require temporary relocation. These conditions can affect sleep, privacy, and a household’s ability to care for children, older adults, or others who depend on consistent support. Emotional distress may arise from the sudden loss of security and the prolonged uncertainty surrounding repairs. Such effects differ from economic losses, which are generally tied to expenses or reduced property value. Non-economic impacts concern the personal consequences of living through damage and displacement. Their recognition can help describe the full scope of a claim, while any available recovery depends on the policy, applicable law, and circumstances.
Proving Your Damages
A property damage claim is stronger when clear, organized evidence supports each loss. In Port St. Lucie storm and weather cases, records can help distinguish economic losses from non-economic effects. Repair estimates, invoices, photographs, inspection reports, and receipts may document property damage, temporary housing, and related expenses. Damage valuation should account for the reasonable cost to repair or replace affected property, supported by consistent documentation.
Causation analysis connects the reported damage to the covered storm event, not wear, maintenance issues, or another cause. Weather records, contractor findings, and timely photographs may help establish that link. Non-economic impacts, such as disruption to household routines or loss of use, should also be described with specific, credible details. Organized evidence enables insurers and decision-makers to assess the claim fairly and understand the full extent of the loss.
Don’t Wait. Call Our Florida Personal Injury Lawyers Now!
When a Port St. Lucie Property Claim Storm & Weather Damage Injury Case Goes to Trial vs. Settlement
When a storm or other weather event damages property in Port St. Lucie, a claim may settle or proceed to trial. Settlement can provide a more predictable outcome and avoid the time, expense, and uncertainty of courtroom proceedings. It may also allow property owners to focus sooner on repairs and community responsibilities. However, an offer should be assessed against documented losses and the practical costs of continuing the dispute.
A trial may be considered when the parties disagree about the cause or extent of damage, or when negotiations do not produce a fair resolution. Trial preparation can involve organizing repair estimates, photographs, expert assessments, and communications with the insurer. The process requires careful attention and may take substantial time. A judge or jury evaluates the evidence, and jury verdicts may not match either party’s expectations. A property owner can weigh these options with counsel, considering the strength of the evidence, likely expenses, and the benefits of a timely resolution.
Florida Laws That May Affect Your Port St. Lucie Property Claim Storm & Weather Damage Case
Whether a storm-damage claim settles or proceeds to trial, Florida law may shape the deadlines, coverage issues, and evidence that affect its outcome. Policy language and state requirements can influence how an insurer evaluates damage, communicates its decision, and handles disagreements. Understanding these rules can help property owners make informed choices while protecting the resources needed to support their households and communities.
- Policy exclusions: Exclusions may limit coverage for certain causes, such as flooding, wear, or maintenance problems. The policy’s wording and the facts surrounding the loss matter.
- Notice and cooperation: Policyholders generally must report damage promptly and provide requested information. Accurate records, photographs, repair estimates, and receipts can help document the claim.
- Appraisal deadlines: A policy may provide an appraisal process for disputes over the amount of loss. Review its procedures and deadlines carefully before making a demand.
- Claim handling: Florida law regulates insurer conduct and may provide remedies for improper claim practices. Applicable requirements depend on the circumstances and current law.
Legal review can clarify coverage obligations and support fair resolution.
The Statute of Limitations for Port St. Lucie Property Claim Storm & Weather Damage Injury Cases
Florida law sets deadlines for filing property damage lawsuits, and missing the applicable statute of limitations can prevent a claim from proceeding in court. For many property insurance disputes, the deadline depends on the date of loss and the type of legal action involved. Florida law generally provides five years to bring a breach-of-contract action, but statutory changes and policy terms may affect claims arising from particular storms. Confirm the governing deadline for the specific loss rather than assume it.
A Policy deadline is separate from the statute of limitations. Insurance policies may require prompt notice, proof of loss, or other steps within specified periods. An appraisal clause may provide a process for resolving disagreement about the amount of damage, but invoking appraisal does not necessarily extend a lawsuit filing deadline. These requirements can affect a policyholder’s ability to pursue recovery, even when damage is substantial. Timely attention to both legal and contractual deadlines helps preserve resources that may support household stability and community recovery after severe weather.
How a Port St. Lucie Property Claim Storm & Weather Damage Lawyer Can Help You
A Port St. Lucie property claim storm and weather damage lawyer can help property owners pursue fair treatment while protecting the homes and businesses that support their families and communities. The lawyer reviews the insurance policy, evaluates the reported damage, and explains available options in clear terms. This guidance can help clients make informed decisions and focus on restoring safe, functional spaces for those who depend on them.
Legal assistance may include:
- Policy interpretation: Clarifying coverage provisions, deadlines, and duties required under the policy.
- Damage documentation: Organizing photographs, repair estimates, inspection reports, and other evidence relevant to the loss.
- Coverage disputes: Evaluating an insurer’s position, including its reliance on coverage exclusions, and identifying support for the claim.
- Claim communications: Preparing responses and presenting documented information to the insurer in an orderly manner.
When to Contact a Port St. Lucie Property Claim Storm & Weather Damage Lawyer
After a storm or severe weather event, prompt legal guidance can help property owners address claim issues before missed deadlines or incomplete documentation complicate recovery. You may want to contact a lawyer as soon as you discover damage, especially if the insurer delays inspection, requests extensive records, or questions the cause or scope of loss. Early advice can help owners understand Policy deadlines and preserve photographs, repair estimates, receipts, and communications relevant to the claim.
Legal guidance may also be appropriate after a partial denial, a settlement offer that appears insufficient, or repeated requests for information that leave the claim unresolved. Property owners assisting family members, tenants, or community organizations should seek timely clarification before authorizing permanent repairs, while taking reasonable steps to prevent further damage. If the policy offers appraisal options, a lawyer can explain when that process is available and what it entails. Contact is especially important when severe weather affects multiple structures or creates uncertainty about coverage and next steps.
Why You Need an Experienced Port St. Lucie Property Claim Storm & Weather Damage Lawyer
When storm or weather damage leads to a disputed property claim, an experienced Port St. Lucie property claim storm and weather damage lawyer can help a policyholder understand available options and respond with reliable evidence. Severe weather may damage roofs, interiors, and personal property, while insurers may question the cause, extent, or timing of the loss. A lawyer can review the policy, assess inspection findings, and explain how Policy interpretation affects the claim. This review may clarify whether coverage exclusions apply or whether the policy covers necessary repairs.
Legal guidance can also help organize photographs, estimates, repair records, and communications with the insurer. If the insurer delays, undervalues, or denies a claim, counsel can identify potential issues and explain appropriate steps toward resolution. By addressing procedural requirements and clearly presenting the documented loss, an experienced lawyer can help property owners protect their interests and pursue a fair outcome while they focus on restoring their homes and supporting their families and community.
How to Choose the Right Port St. Lucie Property Claim Storm & Weather Damage Lawyer for Your Case
Selecting the right Port St. Lucie property claim storm and weather damage lawyer requires careful comparison. A property owner should seek counsel experienced in storm-related insurance disputes, including denied, delayed, or undervalued claims. Reviewing Attorney credentials can help confirm licensing, relevant practice experience, and a record of representing policyholders in property damage matters. The lawyer should also understand Florida insurance requirements and local conditions that may affect a claim.
A prospective client can ask how the attorney evaluates damage, documents losses, and responds to insurer requests. Clear answers help reveal whether the lawyer can explain the process and identify practical next steps. Communication style matters throughout a stressful claim, particularly when families or community organizations need timely updates and dependable guidance. The attorney should listen carefully, address questions directly, and set realistic expectations without promising a particular outcome.
Before choosing counsel, the property owner should review the fee agreement and confirm who will handle routine communications and case decisions.
About The Law Offices of Anidjar & Levine
The Law Offices of Anidjar & Levine represents individuals and businesses in property damage disputes, including claims involving storm and severe weather losses. The firm assists property owners seeking a fair review of damage, coverage, and insurer decisions after disruptive events.
The firm’s history provides context for its work on behalf of people facing difficult legal and financial circumstances. Its attorneys handle insurance claims and related disputes, explain available options, and help clients understand the steps involved. This approach can support property owners who need to focus on restoring their homes or businesses and serving their families, employees, and communities.
Attorney recognition may reflect professional contributions, but it does not guarantee a particular result. Prospective clients can consider an attorney’s experience, communication practices, and familiarity with property insurance issues when evaluating representation. The firm assesses each claim based on its facts, applicable policy language, and relevant law, then pursues an appropriate resolution through negotiation or litigation when warranted.
Frequently Asked Questions
Does Homeowners Insurance Cover Damage From Hurricanes and Tropical Storms in Port St. Lucie?
Homeowners insurance may cover hurricane and tropical-storm damage in Port St. Lucie, but coverage depends on the policy and the cause of loss. Wind damage is often covered, subject to separate hurricane deductibles, while flooding generally requires a separate flood policy. Some policies contain windstorm exclusions or other limits that restrict protection. Policyholders should review their coverage, document damage promptly, and report claims without delay to support a fair assessment and timely assistance.
What Should I Do if My Insurer Denies My Storm Damage Claim?
After a storm damage claim is denied, the policyholder should review the denial letter carefully and identify the insurer’s stated reasons. They should compare those reasons with policy terms, gather photographs, repair estimates, inspection records, and relevant correspondence, then submit a written appeal before applicable appeal deadlines. If the decision remains disputed, a licensed public adjuster or qualified attorney can assess the evidence and explain available options, helping the policyholder pursue a fair resolution.
Can I File a Claim for Damage Caused by a Fallen Tree?
A property owner can generally file an insurance claim for damage caused by a fallen tree, subject to policy terms, exclusions, and the cause of the fall. The owner should photograph the damage, protect people from hazards, and notify the insurer promptly. Tree removal may be covered when necessary to address insured damage, but coverage varies. Neighbor liability may apply if a neighbor’s negligence caused the tree to fall; evidence and local law matter.
Will Filing a Storm Damage Claim Increase My Insurance Premiums?
Filing a storm damage claim may increase insurance premiums, but an increase is not automatic. The insurer may consider the claim’s cause, cost, frequency, policy terms, and applicable state rules when setting future rates. A policyholder could also lose claim-free discounts, even when the damage resulted from severe weather beyond their control. Before filing, the insured should review coverage, deductibles, and potential consequences, then consult the insurer or a qualified adviser.
Can I Hire a Public Adjuster to Inspect My Property Damage?
Yes, a property owner may hire a public adjuster to inspect storm damage and assist with an insurance claim. The adjuster can document visible losses, review policy terms, and prepare an estimate on the owner’s behalf. Adjuster inspection authority is limited to the policyholder’s interests; the insurer retains its own inspection rights. Public adjuster inspection costs and fee arrangements vary, so the owner should review the written agreement before authorizing services.
—————————
Storm and weather damage claims can involve complicated policy terms, disputed causes, and strict deadlines. Property owners in Port St. Lucie should document the damage, preserve relevant records, and seek qualified legal guidance before accepting a settlement or signing claim documents. The Law Offices of Anidjar and Levine can review the available evidence, explain potential options, and communicate with the insurer. Learn more about a Port St. Lucie Personal Injury Lawyer. Prompt, informed action can help protect a claimant’s rights and support a fair evaluation of covered losses.