The Law Offices of Anidjar and Levine can help policyholders document storm and weather damage, review policy terms, and challenge an insurer’s unsupported decision. Storm claims may involve wind, hail, heavy rain, flooding, or damage to roofs, interiors, and belongings. Dated photographs, repair estimates, receipts, and insurer communications can help clarify the cause and extent of loss. Coverage and available remedies depend on the policy and circumstances. Learn more about a Sebastian Personal Injury Lawyer. The following sections explain important claim issues and options.
Main Takeaways
- A Sebastian storm-damage lawyer can review your policy, reported losses, and the insurer’s decision.
- Document storm damage with dated photos, videos, repair estimates, receipts, and a detailed property inventory.
- Notify your insurer promptly and keep records of claim numbers, communications, and submitted documents.
- A lawyer can challenge incomplete or unsupported claim decisions and explain what your policy may cover.
- Take reasonable steps to prevent further damage, but document conditions and keep receipts for temporary repairs.
How We Can Help With Your Sebastian Property Claim Storm & Weather Damage Injury Claim
When a storm or severe weather damages a property in Sebastian, an attorney can help the owner assess the claim, document losses, and address disputes with the insurer. An attorney can organize photographs, repair estimates, receipts, and relevant communications into a clear record of the damage. This preparation helps the owner present accurate information and avoid unnecessary delays.
A Policy review can identify notice requirements, deadlines, exclusions, and duties that may affect the claim. Through coverage analysis, counsel can compare the policy language with the reported damage and explain which losses may qualify for payment. The attorney can also communicate with the insurer, respond to information requests, and challenge an incomplete or unsupported decision.
For property owners focused on protecting their households and restoring safe conditions, practical guidance can make the process more manageable. Counsel can clarify available options, help prioritize next steps, and support informed decisions while keeping the claim organized and focused on documented losses.
Don’t Wait. Call Our Florida Personal Injury Lawyers Now!
Understanding Sebastian Property Claim Storm & Weather Damage Injury Cases
OUR CONSULTATIONSARE FREE
START YOUR FREE CASE REVIEW
Understanding a Sebastian storm or weather damage property claim begins with identifying the cause, scope, and timing of the loss. A careful review establishes what property was affected, when damage occurred, and whether the claimed repairs relate to the reported event. This information helps property owners present a clear account to insurers and supports a fair claim evaluation.
Policy interpretation is central to determining what protection applies. The policy’s terms, endorsements, limits, and post-loss duties may affect whether particular repairs are covered and what documentation is required. Coverage exclusions also require close review because their wording and application can influence the insurer’s decision. A denial or reduced payment should be assessed against the policy language and the evidence supporting the claimed damage.
For households and organizations serving others, timely attention to property damage can protect safe, usable spaces. Organized records, professional assessments, and clear communication can help resolve disputes and clarify the policy’s available remedies.
Common Causes of Sebastian Property Claim Storm & Weather Damage
Property damage in Sebastian commonly results from hurricanes and tropical storms, which can bring destructive winds and intense rainfall. Wind and tornadoes, hail, and heavy rain may damage roofs, windows, and other structures. Flooding and storm surge can also cause extensive damage, particularly in low-lying areas.
Hurricane And Tropical Storms
Hurricanes and tropical storms can cause extensive property damage in Sebastian through high winds, wind-driven rain, flooding, and flying debris. Heavy rainfall may overwhelm drainage systems, while storm surge can push water into homes and businesses near the coast or waterways. Roof leaks, damaged windows, soaked interiors, and ruined belongings may result, creating urgent safety and recovery needs for residents and local organizations.
Hurricane preparedness can reduce exposure before a storm arrives. Property owners can secure outdoor items, protect openings, move valuables to higher levels, and document building conditions. Monitoring tropical storm forecasts helps residents and community groups make timely decisions about evacuation, shelter, and resource distribution. After conditions are safe, prompt damage documentation and review of insurance requirements can support a clear claim. Accurate records also help insurers assess losses and direct assistance to affected households.
Wind And Tornado Damage
When severe winds or tornadoes move through Sebastian, they can damage roofs, break windows, dislodge siding, and send debris into homes and businesses. These forces may also topple trees, damage fences, and compromise garages or other structures. Even when a building remains standing, sudden pressure changes and flying debris can create openings that expose interior property to further damage. After an event, owners may need to document visible damage, protect affected areas from further harm, and promptly notify their insurer. Photographs, repair estimates, and records of damaged belongings can help support a claim. Tornado preparedness, including a reliable shelter plan and secured outdoor items, can reduce risks to occupants. Wind mitigation measures, such as reinforced roof connections and impact-resistant openings, may limit damage. A qualified professional can assess disputed losses and explain available claim options.
Hail And Heavy Rain
Hail and heavy rain can cause significant property damage in Sebastian, even during storms without extreme winds. Hail formation begins when water droplets freeze and grow inside storm clouds, sometimes producing stones large enough to crack roof tiles, dent metal panels, break windows, and damage exterior finishes. Severity depends on hail size, density, and the property’s condition before the storm. Rain intensity also matters. Prolonged or heavy rainfall can overwhelm roof drainage, seep through damaged shingles, and stain ceilings or walls. Moisture may affect insulation, flooring, and personal belongings, while hidden leaks can worsen if repairs are delayed. Property owners who document visible damage, keep receipts, and arrange prompt inspections can support accurate claim reviews and help ensure affected homes receive timely, responsible attention from insurers and repair professionals.
Flooding And Storm Surge
Beyond hail and heavy rain damage, flooding and storm surge can threaten Sebastian properties near the coast, waterways, and low-lying areas. Rising water may enter homes and businesses, damage foundations, ruin flooring, and destroy electrical systems. Storm surge can push saltwater inland with force, while drainage backups and overflowing canals may worsen flooding during prolonged rain. Even after water recedes, Floodwater Contamination from sewage, chemicals, and debris can create health hazards and complicate cleanup. Property owners may document visible damage, keep repair records, and take reasonable steps to limit further loss, as long as those actions are safe. Surge Barriers and other protective measures may reduce exposure, but they cannot eliminate risk during severe storms. A careful assessment can help clarify the damage, policy requirements, and available claim options.
Legal Rights of Sebastian Property Claim Storm & Weather Damage Injury Victims
Sebastian property owners whose homes or businesses are damaged by storms may have legal rights under their insurance policies and Florida law. Policyholders can review coverage terms, submit documented claims, and challenge decisions they believe conflict with the policy. Policy exclusions and appraisal clauses may affect available remedies, so their wording and application require careful review.
Three practical rights may help owners protect their interests while restoring property and supporting affected occupants:
- A fair claim review: Insurers must assess covered losses according to policy terms and applicable law. Owners may request written explanations for denials, delays, or reduced payments.
- Access to dispute procedures: Depending on the policy, appraisal clauses, mediation, or other processes may help resolve disagreements about the amount of loss.
- Legal representation: An attorney can explain deadlines, evaluate insurer conduct, and identify options for pursuing benefits or contesting an improper decision.
Prompt recordkeeping and timely communication can preserve important evidence. Owners seeking to serve tenants, employees, or neighbors should also understand that claim rights and responsibilities depend on the policy and circumstances.
Why Do Storm & Weather-Related Injuries Happen at Sebastian Properties?
Storm and weather-related injuries on Sebastian properties often occur when severe conditions damage buildings, create hidden hazards, or disrupt safe access. High winds and heavy rain can expose roof vulnerabilities, loosen shingles, and let water weaken ceilings or floors. These failures can cause materials to fall or surfaces to become unstable, endangering residents, visitors, and workers.
Tree hazards also contribute to storm-related injuries. Saturated soil and strong gusts can uproot trees or break limbs, damaging structures, blocking walkways, and creating risks for anyone nearby. Flooding may conceal holes, debris, or uneven ground, while standing water can make entrances and interior flooring slippery. Lightning, flying debris, and damaged electrical systems present additional dangers, particularly when power lines or equipment are affected.
Some injuries result from hazards that persist after the weather clears. Delayed repairs, inadequate inspections, or poor property maintenance can leave damaged areas unsafe. These conditions may affect people seeking shelter, delivering assistance, or performing necessary work on the property.
What Should You Do After a Sebastian Property Claim Storm & Weather Damage Injury?
After a storm-related injury, the affected person should seek prompt medical care and follow the provider’s recommendations. Document property damage with clear photographs, repair estimates, and records of related expenses. Notify the insurer promptly, and keep copies of relevant evidence for the claim.
Seek Medical Care
Even when storm damage appears to be the primary concern, anyone injured during a weather event should seek prompt medical care. Emergency evaluation is important after falls, impact injuries, electrical exposure, or contact with contaminated floodwater. Severe bleeding, difficulty breathing, confusion, loss of consciousness, or suspected fractures require immediate emergency services. Less obvious injuries may also need assessment, since pain and other symptoms can develop or worsen hours later.
A medical professional can identify injuries, recommend treatment, and explain appropriate follow-up care. The injured person should describe how the event occurred, report all symptoms, and disclose relevant medical conditions or medications. Following clinical instructions supports recovery and helps prevent complications. Symptom monitoring is also important after the initial visit; report new or worsening concerns promptly to a qualified provider. Timely care protects health and helps injured household members return safely to their responsibilities.
Document the Damage
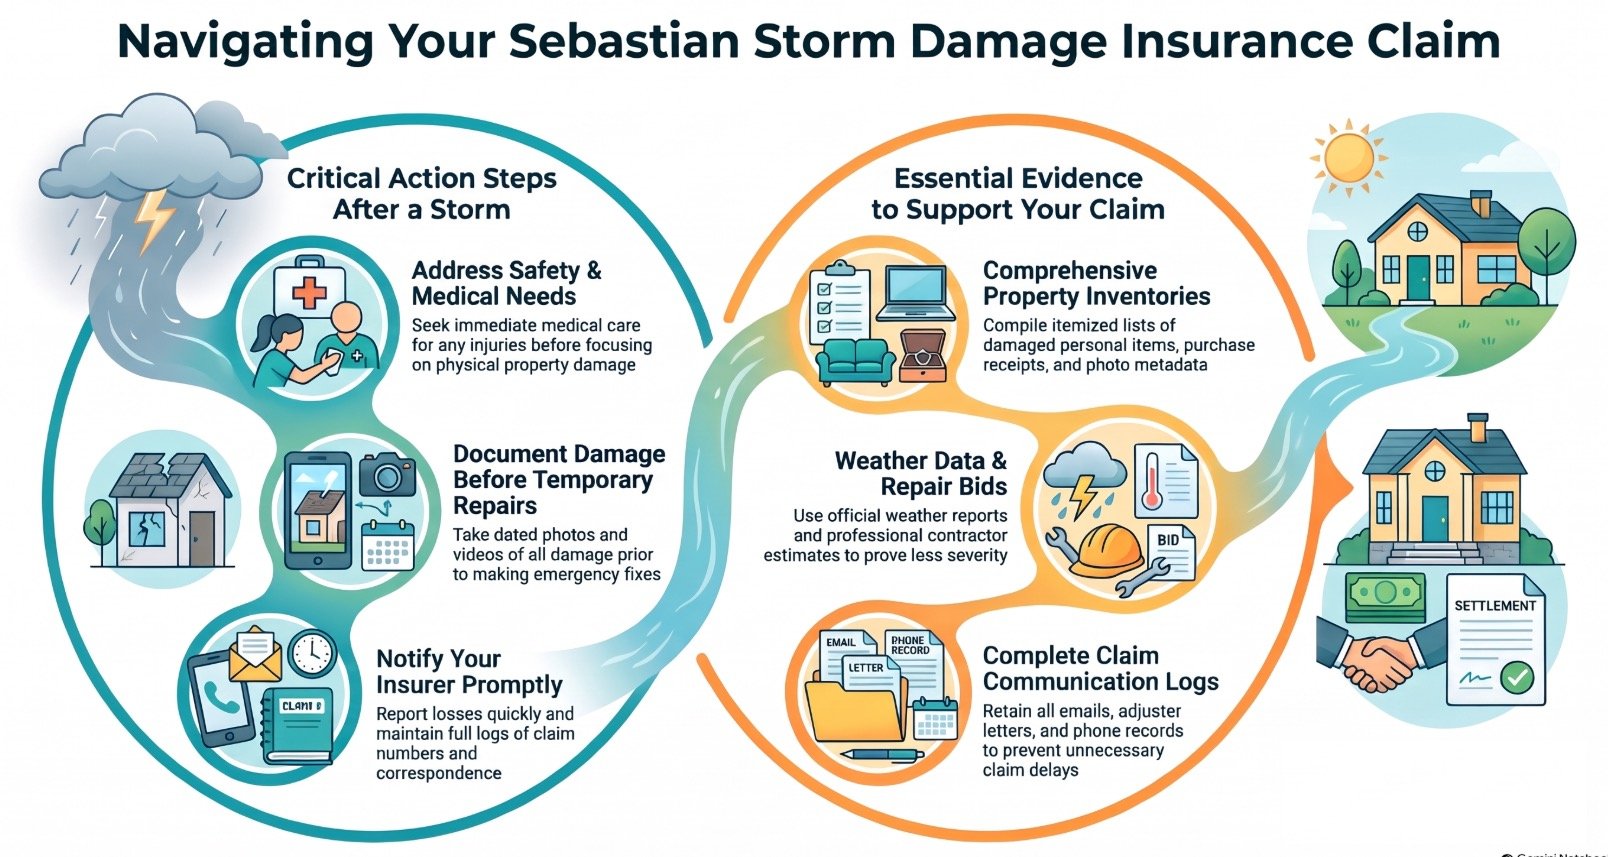
Once the property owner has addressed immediate medical needs, they should document visible damage as soon as conditions are safe. Photographs and videos can show affected rooms, structural problems, standing water, and damaged belongings from several angles. The owner should date and locate each image and create a written inventory of Personal Property, including descriptions, approximate purchase dates, and estimated values. Receipts, warranties, and other records may help substantiate those estimates. If conditions require Temporary Repairs to prevent further harm, the owner should photograph the area beforehand when feasible and keep receipts for materials and labor. Do not discard damaged items until they are thoroughly documented, unless retaining them creates a safety risk. Organized records can support an accurate assessment and help protect the interests of everyone affected by the loss.
Notify Your Insurer
When it is safe to do so, the property owner should promptly notify the insurer of the storm or weather damage and follow the policy’s reporting requirements. Deadlines may apply, so the owner should review the policy and contact the insurer promptly. The initial policy notice should identify the affected property, describe the event and observed damage, and, if known, provide the date it occurred. The owner should keep a record of the call or submission, including confirmation numbers, names, dates, and copies of all correspondence. Photographs, repair estimates, and prior damage records can help support the report, but should not delay notice. The owner should answer questions accurately and avoid speculation about cause or cost. Timely, clear communication helps the insurer assess the claim and supports a fair review for everyone affected.
Critical Evidence in a Sebastian Property Claim Storm & Weather Damage Injury Case
Strong evidence can clarify the extent of storm damage and support a property claim.
Essential records include:
- Dated photographs documenting damage and affected areas.
- Local weather reports and itemized repair estimates.
- Claim communications with the insurer, including letters and emails.
Damage Photographs
How clearly you document a storm-damaged property can affect how an insurer evaluates a claim. Prompt photographs can preserve the condition of a home, business, or other property before cleanup or repairs change the scene. Images should show both broad views and close details, including damaged roofing, broken windows, water intrusion, affected belongings, and any visible safety hazards. A consistent record can help explain the extent of loss and support fair consideration of the people affected.
Photo metadata, such as capture dates and times, may help establish when images were taken. Image organization also matters: files can be labeled by location, room, and damage type, then stored securely with original versions intact. Clear, truthful photographs should not be altered or staged. A lawyer can help assess whether the images adequately document the claimed damage.
Weather Reports
Weather reports can help establish the conditions surrounding a storm-related property claim in Sebastian. Official records from the National Weather Service and other reliable sources may document wind speeds, rainfall, hail, lightning, and the timing of severe conditions. Weather bulletins issued before and during an event can also show what warnings were available and when they reached the area. These details may help explain how a property was exposed to the storm and whether reported damage is consistent with local conditions. Because observations can vary by location, nearby station data and radar records may provide useful context. Forecast accuracy is also relevant when evaluating advance warnings, but a forecast does not prove that damage occurred. Preserving dated reports and identifying their sources can support a clear, evidence-based claim and help those responsible evaluate it fairly.
Repair Estimates
After weather records establish the conditions surrounding a storm, repair estimates can help document the resulting property damage and the anticipated cost of restoring the affected areas. A detailed estimate should identify damaged components, describe necessary work, and distinguish emergency measures from permanent repairs. Photographs, inspection findings, and itemized Contractor bids can support the estimate by showing the scope and basis of proposed costs. Accurate material pricing is also important, particularly when replacement products must meet existing building standards or are not readily available. Comparisons among qualified contractors may reveal differences in labor assumptions, repair methods, and projected timelines. These records can help property owners present a clear account of the loss and support fair evaluation of restoration needs. Careful documentation also helps prevent overlooked damage from being excluded from the repair plan.
Claim Communications
Clear claim communications can be vital evidence in a Sebastian property storm and weather damage case. Adjuster correspondence may show when the insurer received notice, what information it requested, and how it explained coverage decisions. Emails, letters, claim portal messages, and documented phone calls can help establish whether the policyholder responded promptly and provided requested materials. These communication records may also reveal delays, changing explanations, or unresolved questions about the damage and repair estimates. A careful record helps the insurer assess the claim accurately and supports a fair resolution. Policyholders can preserve original messages, note call dates and participants, and keep copies of submitted documents. Organized communications may assist attorneys, adjusters, and others working to resolve the dispute, while reducing misunderstandings about what was reported, requested, or decided.
Long-Term Effects of Sebastian Property Claim Storm & Weather Damage Injuries
Storm and weather-related injuries may cause chronic pain that continues long after the initial incident. Some individuals also experience lasting mobility limitations that interfere with daily activities and independence. Emotional distress may persist alongside these physical effects, making appropriate assessment and documentation important.
Chronic Pain
Chronic pain can persist long after a storm-related injury, limiting a person’s mobility, sleep, and ability to work. When a damaged roof, falling debris, or flood exposure causes lasting harm, the effects may continue after immediate repairs and treatment. Persistent discomfort can disrupt concentration, household responsibilities, and the ability to support family or community commitments. Daily activity limitations may develop gradually, making routine tasks harder even when the original injury seemed minor. A medical professional can assess symptoms, recommend appropriate care, and document how pain affects everyday functioning. Chronic pain management may involve a coordinated plan that includes medication, therapy, and follow-up evaluations. Consistent records of treatment, expenses, and functional changes can help clarify the injury’s long-term impact when an affected property owner pursues an insurance claim or seeks legal guidance.
Lasting Mobility Issues
Lasting mobility issues may develop after storm-related injuries such as fractures, joint damage, or falls on debris-covered surfaces. Damage to roofs, walkways, and interior floors can create hazards that lead to injuries requiring extended recovery. Some people experience reduced balance, stiffness, weakness, or difficulty standing and walking, which may interfere with daily routines and responsibilities.
A medical assessment can help identify limitations and guide appropriate care. Physical therapy can improve strength, flexibility, and safe movement, while mobility aids such as canes or walkers can improve stability when needed. Recovery plans often require regular follow-up and adjustments as a person’s abilities change. When injuries arise during severe weather or property damage, records of treatment, functional limitations, and recommended assistance may help clarify the effects on daily life and the support required for continued independence.
Emotional Distress
Emotional distress may persist after storm-related injuries, particularly when pain, disrupted routines, or uncertainty about recovery continues over time. Affected residents may experience anxiety after property loss, especially when damage disrupts housing, finances, or a sense of safety. Trauma-related sleep disturbances can also interfere with concentration, energy, and the ability to manage daily responsibilities. These effects may continue even after physical injuries begin to mend, straining relationships and limiting participation in work or community life. Caregivers and service providers can help by recognizing changes in mood, sleep, and behavior without assuming a cause. Consistent support, appropriate mental health care, and clear information about recovery may help individuals regain stability. When emotional symptoms persist, documenting their duration and impact can assist clinicians and support an accurate assessment of losses.
Don’t Wait. Call Our Florida Personal Injury Lawyers Now!
Proving Liability in Sebastian Property Claim Storm & Weather Damage Injury Cases
Proving liability in a Sebastian storm or weather damage property claim requires evidence linking the loss to a party’s failure to meet a legal or contractual duty. The responsible party may be a property owner, contractor, or another person whose conduct contributed to the damage. Evidence can include dated photographs, repair records, inspection reports, witness accounts, and expert assessments of how the loss occurred.
Maintenance Negligence may be relevant when a party failed to address known roof defects, blocked drainage, or deteriorating exterior materials before severe weather. A Building Code violation may also help establish that construction or repairs fell below required safety standards, although a violation alone may not prove liability. The evidence must connect the failure to the specific damage and show that reasonable precautions could have reduced the loss.
Prompt documentation preserves details and supports a fair assessment. Carefully reviewing records, property conditions, and applicable duties helps clarify responsibility and identify practical steps to restore safe, usable spaces.
Dealing With Insurance Companies After a Sebastian Property Claim Storm & Weather Damage Injury
After a Sebastian property claim involving storm or weather damage, clear communication with the insurance company can help ensure the claim is accurate. The property owner should clearly describe the observed damage, provide requested records, and keep copies of correspondence, photographs, repair estimates, and receipts. Accurate, consistent information can help the insurer assess the reported loss and reduce misunderstandings.
Policy interpretation may affect which damage is covered, what exclusions apply, and whether specific documentation is required. If policy language is unclear, the owner may request a written explanation and consult a qualified professional before accepting an interpretation. Prompt reporting and organized records can also help address payment delays, though they cannot guarantee a particular outcome.
When communication becomes difficult, a representative may help clarify questions, correct factual errors, and keep discussions focused on the documented damage. A careful, respectful approach supports fair consideration while allowing the owner to prioritize safety, repairs, and the needs of others affected by the storm.
What to Expect During a Sebastian Property Claim Storm & Weather Damage Injury Claim Process
A storm damage claim typically begins with an initial review of the policy, reported losses, and available evidence. The property owner should document damage carefully, while the insurer investigates to assess coverage and the extent of the loss. The process may end with a settlement or become a dispute if the parties disagree about payment.
Initial Claim Review
During the initial claim review, the insurer evaluates the reported storm or weather damage, the available documentation, and the policy terms that may govern coverage. The adjuster may confirm when the loss occurred, identify the property involved, and determine whether the reported event falls within the policy’s covered causes. Policy exclusions and coverage limits can affect which repairs or losses qualify for payment, as can deductibles and claim deadlines. The insurer may request clarification about the circumstances or ask for information needed to assess the claim’s scope. A timely, organized response can help keep the review moving and support a fair decision. The policyholder should read correspondence carefully, note any requested actions, and seek qualified guidance if the insurer’s interpretation appears inconsistent with the policy language or applicable requirements.
Damage Documentation
Clear damage documentation helps establish the extent and cause of a storm-related loss during a Sebastian property claim. After addressing immediate safety concerns, the property owner can photograph affected areas, damaged materials, and visible water intrusion before cleanup alters the scene. Images should include wide views and closer details, with dates and brief notes identifying each location. Emergency stabilization, such as covering a damaged roof or preventing further water entry, may be necessary to protect occupants and limit additional loss. Receipts and records of these temporary measures should be retained. A personal property inventory can list damaged belongings, their approximate age, condition, and replacement cost, supported by photographs or purchase records when available. Organized documentation helps claimants present a clear account of losses and supports a fair, accurate review.
Insurer Investigation
After a storm-related property claim is filed, the insurer typically investigates to assess the reported damage, its cause, and the potential cost of repairs. The process may include a site visit by an adjuster, who photographs affected areas, reviews available records, and asks questions about when the damage occurred. Inspection protocols guide how the property is examined and which details are recorded. The insurer may also consult contractors or other experts when the damage requires additional assessment. Policy documents are reviewed through coverage analysis to determine which protections, limits, exclusions, and conditions may apply. Clear access to the property and organized information can help the investigation proceed efficiently. The review aims to establish relevant facts and evaluate the claim under the policy while preserving an accurate record for all involved parties.
Settlement or Dispute
Once the insurer has assessed the reported damage and applicable policy terms, the claim may proceed toward settlement or become disputed. A settlement may cover approved repairs, replacement costs, or other benefits available under the policy, subject to limits, deductibles, and exclusions. Before accepting an offer, the property owner can compare it with repair estimates and supporting records to determine whether it addresses documented losses. Settlement Options may include supplemental payments if additional damage is discovered or properly supported expenses were omitted from the initial evaluation.
If the insurer and policyholder disagree about coverage, damage estimates, or payment, Dispute Resolution may involve further documentation, negotiation, appraisal, mediation, or legal proceedings, depending on the policy and circumstances. Organized records and timely responses can help clarify the issues. A qualified attorney may explain available procedures and protect the owner’s interests.
Compensation for Sebastian Property Claim Storm & Weather Damage Injury Damages
Compensation for storm and weather damage to Sebastian property depends on the policy’s coverage, the cause and extent of the loss, and the evidence supporting the claim. A careful review of the insurance contract can identify covered repairs, exclusions, limits, and deadlines. The insured may seek payment for necessary work to restore a home or business, including repairs to roofs, windows, interiors, and damaged personal property, subject to applicable policy terms.
When a covered loss makes a residence uninhabitable, Additional living expenses may help pay reasonable costs for temporary housing and related necessities. For businesses forced to suspend or reduce operations, Business interruption coverage may address qualifying lost income and continuing expenses during the recovery period. Documentation such as photographs, repair estimates, receipts, inventories, and records of interrupted operations can help substantiate requested benefits. Insurers may evaluate damage, causation, and policy requirements before issuing payment. Prompt, organized communication supports a fair review and helps property owners plan repairs while preserving resources for their households, employees, and community.
Economic vs. Non-Economic Damages in Sebastian Property Claim Storm & Weather Damage Cases
Storm and weather claims may include economic property losses, such as repair costs, damaged belongings, and related expenses. Non-economic harm may also arise when property damage disrupts daily life or causes significant personal hardship. Proving both categories requires clear documentation linking the claimed losses to the storm and supporting their value.
Economic Property Losses
Property damage claims can involve both economic and non-economic losses, though insurance coverage and available remedies differ. Economic property losses are measurable financial costs caused by storm or weather damage. They may include reasonable repair or replacement expenses, emergency mitigation, debris removal, and costs to protect a property from further harm. Documentation such as estimates, invoices, photographs, and payment records can help establish the amount and cause of each loss.
Landlords may claim lost rental income when covered damage makes a unit uninhabitable, subject to policy terms and supporting records. Businesses may also face business interruption losses when physical damage disrupts operations. Relevant evidence can include prior financial statements, tax records, payroll information, and records of closure periods. Careful accounting helps insurers and decision-makers assess claimed losses and distinguish supported costs from unrelated expenses.
Non-Economic Harm
Although storm and weather damage can create high financial costs, the disruption and distress it causes are generally treated differently from economic losses in a property claim. Economic damages cover measurable expenses, such as repairs, while non-economic harm concerns personal effects without a direct price. Emotional suffering may arise from displacement, uncertainty, or the loss of a sense of security after a severe storm. Loss of enjoyment can occur when damaged living spaces prevent residents from using their homes or participating in ordinary routines. These effects may be especially difficult for households balancing recovery with responsibilities to family members, neighbors, or others who depend on them. Florida property insurance generally covers property damage, so non-economic harm is not automatically compensable. The policy terms and applicable law determine what relief may be available.
Proving Your Damages
A well-organized record helps show how a storm affected a property and what losses followed. In Sebastian, owners can document roof, siding, and interior damage with dated photographs, inspection reports, repair estimates, invoices, and receipts for temporary protection or alternative lodging. These records support economic damages, including reasonable repair costs and covered additional living expenses. Damage valuation should compare the insurer’s estimate with contractor assessments and applicable policy terms, while identifying work needed to restore the property.
Depreciation disputes may arise when an insurer withholds part of replacement costs or applies age-related deductions. Clear evidence of materials, condition, and completed repairs can help address those differences. Non-economic harm, such as disruption and loss of normal use, may also be relevant where recognized by law, but it should be distinguished from documented financial losses. Careful records help present a complete, credible claim.
Don’t Wait. Call Our Florida Personal Injury Lawyers Now!
When a Sebastian Property Claim Storm & Weather Damage Injury Case Goes to Trial vs. Settlement
When settlement negotiations fail to produce a fair resolution, a Sebastian storm and weather damage claim may proceed to trial, where a judge or jury evaluates the evidence and determines liability and compensation. Before trial, both sides present records, repair estimates, photographs, expert opinions, and testimony concerning the damage and the insurer’s response. Trial timelines vary with case intricacy, court schedules, and disputes over evidence, so preparation may require sustained attention and coordination.
A settlement can provide a more predictable resolution, reduce litigation expense, and spare property owners the uncertainty of a courtroom decision. However, an offer may not adequately reflect documented losses or the resources needed to restore a safe home or business. Jury considerations may include witness credibility, the quality of supporting documentation, and whether the claimed damage is connected to the storm. A trial can produce a binding decision, but its outcome is not guaranteed. Careful evaluation of the evidence, likely costs, and client priorities helps determine which path best serves the affected property owner and community.
Florida Laws That May Affect Your Sebastian Property Claim Storm & Weather Damage Case
The choice between settlement and trial is shaped in part by Florida laws governing property insurance claims. For Sebastian homeowners, understanding these rules can help protect a household’s recovery and support those who depend on it.
Three areas may influence how a storm damage claim proceeds:
- Notice and documentation: Florida law and policy terms may require prompt notice, access for inspection, and records supporting the reported damage. Photographs, repair estimates, and receipts can help establish the loss.
- Claim handling: Insurers must follow statutory standards for investigating and communicating about claims. A policyholder may request explanations for coverage decisions and preserve correspondence.
- Dispute procedures: Policy language may provide appraisal rights when the parties disagree about the amount of a covered loss. Appraisal generally addresses valuation, not every coverage dispute, so its scope matters.
Florida deadlines can apply to required claim notices and responses. Because requirements depend on the policy and circumstances, careful review can help claimants make informed decisions and avoid preventable disputes.
The Statute of Limitations for Sebastian Property Claim Storm & Weather Damage Injury Cases
How long a Sebastian homeowner has to pursue a storm damage insurance dispute depends on the claim type and the deadlines set by Florida law and the policy. Florida law generally provides five years to file a lawsuit for breach of a property insurance contract, measured from the date of loss. However, statutory changes and the specific facts may affect which deadline applies, so the loss date and governing law should be confirmed.
Separate requirements may apply before litigation. Florida law sets time limits for reporting property losses and filing supplemental or reopened claims. Policy deadlines may impose additional notice, proof-of-loss, or documentation requirements, and missing them can jeopardize coverage even when a lawsuit deadline has not passed. Appraisal clauses may also establish procedures and timing for resolving disagreements over the amount of damage, but they do not necessarily extend statutory deadlines.
Prompt review of the policy, claim correspondence, and applicable law helps preserve the homeowner’s options and supports a fair resolution for those relying on the property.
How a Sebastian Property Claim Storm & Weather Damage Lawyer Can Help You
A Sebastian property claim storm and weather damage lawyer can help homeowners protect their rights after a storm and address disputes with an insurer. The lawyer can review the policy, assess the insurer’s handling of the claim, and explain available options in clear terms. This support can help property owners pursue a fair resolution while preserving resources for their families and communities.
A lawyer may assist by:
- Policy interpretation: Explain coverage terms, limits, duties, and deadlines relevant to the reported damage.
- Evidence organization: Review inspection reports, repair estimates, photographs, and other records to clarify the scope and cause of loss.
- Dispute advocacy: Communicate with the insurer, challenge unsupported decisions, and present documented reasons for payment when appropriate.
The lawyer can also identify potential Coverage exclusions and assess whether the insurer applied them consistently with the policy language and facts. With focused guidance and organized advocacy, counsel can help homeowners make informed decisions and pursue claim treatment that reflects the policy and documented damage.
When to Contact a Sebastian Property Claim Storm & Weather Damage Lawyer
After storm or weather damage, homeowners should consider contacting a Sebastian property claim lawyer when coverage is unclear, the insurer delays its decision, or the payment does not reflect documented repair needs. Early guidance can help residents understand what information to preserve and how to communicate concerns clearly while repairs and community responsibilities continue.
Contact may also be appropriate when an insurer requests extensive records, disputes the cause or extent of damage, or issues a denial that appears inconsistent with the policy. Policy deadlines can affect notice, proof-of-loss submissions, and other claim steps, so homeowners should review applicable dates promptly. A lawyer can help clarify coverage exclusions and explain whether the insurer’s stated basis aligns with the policy language and available evidence.
Keeping photographs, estimates, receipts, inspection reports, and insurer correspondence organized can support a timely review. Homeowners who serve family members, neighbors, or local organizations may benefit from addressing claim concerns before unresolved damage creates further disruption.
Why You Need an Experienced Sebastian Property Claim Storm & Weather Damage Lawyer
An experienced Sebastian property claim storm and weather damage lawyer can help homeowners determine whether an insurer’s decision aligns with the policy terms and the documented damage. After severe weather, a clear assessment can help families protect their homes and restore safe living conditions. Legal experience supports careful Policy interpretation, including reviewing exclusions, deductibles, deadlines, and contractually required duties. A lawyer can also conduct coverage analysis by comparing the policy with inspection findings, repair estimates, photographs, and other claim records.
When an insurer disputes the cause or extent of damage, an attorney can identify gaps in the investigation and present relevant evidence in an organized manner. This assistance may help homeowners understand a partial payment, denial, or delay and determine whether further action is warranted. By explaining available rights and obligations, counsel can reduce confusion during a demanding recovery period. A well-supported claim can encourage fair consideration while helping affected households focus on repairs and community responsibilities.
How to Choose the Right Sebastian Property Claim Storm & Weather Damage Lawyer for Your Case
Choosing the right Sebastian property claim storm and weather damage lawyer requires carefully reviewing the attorney’s experience with property insurance disputes and familiarity with Florida claims practices. A suitable candidate should explain how the policy, inspection findings, and claim deadlines may affect the homeowner’s options. The attorney should also communicate clearly and respond promptly, allowing clients to make informed decisions while managing repairs and household responsibilities.
Review Lawyer Credentials, including Florida Bar membership, relevant experience, and any disciplinary history. Ask whether the lawyer has handled storm, wind, or water damage disputes similar to the current claim, and what steps may be needed to document losses. References and independent reviews can offer additional perspective, but should not replace direct questions about case strategy.
Before signing an agreement, examine the Fee Structure and clarify how costs, expenses, and payment obligations are handled. Carefully compare qualifications, communication practices, and written terms to help a property owner select counsel suited to the claim’s needs and pursue a fair resolution.
About The Law Offices of Anidjar & Levine
The Law Offices of Anidjar & Levine represents clients in a range of legal matters, including property insurance claim disputes. For Sebastian property owners, the firm can assist with questions about storm damage, policy terms, claim documentation, and insurer decisions. Its work may include reviewing relevant records, communicating with insurance companies, and pursuing available remedies when a claim is delayed, underpaid, or denied.
Firm history provides context for understanding the organization’s practice and service approach. The firm was established in Florida and represents individuals in personal injury and insurance dispute matters. Its attorneys handle cases across several practice areas, helping clients when property damage affects their homes, finances, or daily responsibilities.
Attorney recognition may reflect professional standing, but it does not guarantee a particular result. Prospective clients can review the firm’s experience, credentials, and communication practices before deciding on representation. A clear discussion of the claim, available evidence, deadlines, and potential next steps can help property owners make informed decisions while protecting their interests.
Frequently Asked Questions
Does Homeowners Insurance Cover Mold Caused by Storm-Related Water Intrusion?
Homeowners insurance may cover mold caused by storm-related water intrusion when the storm created a sudden opening and the resulting water damage is covered under the policy. Coverage may be denied if water entered through neglect, ongoing leaks, or excluded flooding. Policies often impose Mold remediation limits, and Hidden moisture damage can complicate assessment. Promptly document the intrusion, prevent further damage, and review policy terms to help homeowners pursue a fair claim and protect affected household members.
Can I File a Claim if My Storm-Damaged Property Is a Rental?
Yes, a property owner can generally file a claim for storm damage to a rental, subject to the policy’s terms, exclusions, and deadlines. Landlord policy coverage may address damage to the building and certain rental-related losses, but the owner should document the damage and notify the insurer promptly. Tenant property damage is usually handled under the tenant’s renters insurance, unless the landlord’s policy or applicable law provides otherwise. The owner should review coverage and cooperate with inspections.
What if My Insurer Says the Damage Resulted From Flooding?
A flooding determination does not automatically end a property claim; the policy language and cause of damage must be reviewed. A Flood Exclusion may bar coverage for certain water events, while wind-driven rain or plumbing failures may be treated differently. Water Classification can help identify the source and pathway, but evidence such as photographs, inspection reports, and repair records is also important. The policyholder may request the insurer’s written explanation and seek an independent assessment.
Can I Hire a Public Adjuster to Inspect My Storm Damage?
Yes, a property owner may hire a public adjuster to inspect storm damage and help document and present an insurance claim. The Public adjuster inspection process typically includes reviewing visible damage, photographs, repair estimates, and relevant policy terms. Before hiring, the owner should confirm the adjuster’s licensing and understand the public adjuster fee structure, including how fees are calculated and whether they apply to any settlement or payment received.
Should I Make Temporary Repairs Before the Insurance Inspection?
Yes. Temporary repairs should be made promptly to prevent further damage, such as covering a roof opening or boarding a broken window. Before work begins, Document storm damage with clear photographs or video, and retain damaged materials when practical. Keep receipts and records of repair costs. The policyholder should avoid permanent repairs or discarding evidence until the insurer has inspected the property, unless urgent safety concerns require immediate action.
—————————
Storm and weather damage claims can involve complex policy terms, disputed coverage, and strict deadlines. Sebastian property owners should document damage, preserve relevant records, and carefully review insurer decisions before accepting a settlement. If a claim is delayed, underpaid, or denied, an experienced property claim lawyer can review the evidence and explain your options. The Law Offices of Anidjar and Levine helps clients pursue fair treatment under their insurance policies and resolve disputes with informed legal guidance. Learn more about a Sebastian Personal Injury Lawyer.