A Hollywood property claims storm and weather damage lawyer at The Law Offices of Anidjar and Levine can review policy terms, investigate reported damage, and explain options when an insurer delays, reduces, or denies a claim. Disputes may involve exclusions, deductibles, causation, repair estimates, or missed deadlines. Photographs, inspection reports, weather records, receipts, and timely insurer notices can support a claim review. Because coverage and legal remedies depend on the policy and facts, learning how these issues are assessed can help clarify possible next steps. For other legal matters, learn more about a Hollywood Personal Injury Lawyer.
Main Takeaways
- A Hollywood property-claim lawyer can review your policy, storm-damage evidence, the insurer’s decision, and your options for challenging a denial or low offer.
- Coverage depends on policy terms, exclusions, deductibles, deadlines, and evidence about the cause and extent of damage.
- Report damage promptly, follow policy requirements, and keep insurer notices, claim records, receipts, and repair estimates.
- Photograph damage and cleanup when safe, preserve original files, and arrange qualified assessments of structural or electrical hazards.
- Address urgent safety risks and prevent further damage when possible; a lawyer can explain potential next steps, but cannot guarantee an outcome.
How We Can Help With Your Hollywood Property Claim Storm & Weather Damage Injury Claim
After a storm damages a home or business in Hollywood, a property owner may face urgent repairs, disputed coverage, and significant financial losses. A property claim lawyer can help organize the response, explain available options, and keep the insurer’s obligations in view. Counsel may review the policy, document the damage, and prepare a clear claim supported by photographs, repair estimates, receipts, and other records.
When a building cannot be safely occupied, the lawyer can help the owner address Emergency housing needs and determine whether the policy covers temporary lodging or related expenses. Assistance may also include coordinating debris removal documentation, preserving damaged materials when practical, and tracking cleanup costs. These steps can support a complete claim while reducing avoidable delays.
If the insurer questions the scope or value of the loss, counsel can communicate with adjusters, respond to requests, and seek a fair resolution. The goal is to help property owners restore safe, usable spaces and protect resources needed for recovery.
Understanding Hollywood Property Claim Storm & Weather Damage Injury Cases
OUR CONSULTATIONSARE FREE
START YOUR FREE CASE REVIEW
Understanding a Hollywood storm and weather damage property claim begins with identifying the cause and extent of the loss, then comparing the evidence with the policy’s coverage terms. A careful review may include photographs, repair estimates, inspection records, receipts, and communications with the insurer. These materials help establish when damage occurred, what property was affected, and whether the claimed costs are supported. Policy language matters because coverage limits, exclusions, deadlines, and documentation requirements can shape how a claim is evaluated.
Prompt, organized reporting can also help property owners protect occupants and preserve accurate records while repairs are considered. Emergency preparedness supports safer decisions during an active event, while mitigation planning can reduce further damage and demonstrate responsible steps after conditions permit. Document these measures, and do not let urgent work delay necessary safety precautions. When questions arise about a denial, reduced payment, or delayed review, a qualified professional can assess the insurer’s position and explain available options. Clear guidance can help owners pursue fair treatment while maintaining safe, service-oriented priorities.
Common Causes of Hollywood Property Claim Storm & Weather Damage
Hollywood properties may sustain damage from hurricanes and tropical storms, as well as severe winds and tornadoes. Heavy rain can cause flooding, while hail and lightning may damage roofs, windows, and electrical systems. Identifying the source of loss can help clarify the scope of a property claim and the evidence needed to support it.
Hurricane And Tropical Storms
Hurricanes and tropical storms can cause extensive property damage in Hollywood through powerful winds, wind-driven rain, flooding, and flying debris. Storm surge can push seawater inland, inundating homes, businesses, roads, and electrical systems. Heavy rainfall may overwhelm drainage systems and lead to roof leaks, interior water intrusion, and prolonged standing water. These conditions can damage structural components, personal belongings, and vital equipment, while creating health and safety concerns for residents and workers. Property owners may reduce some risks by maintaining roofs, clearing drainage paths, and installing hurricane shutters before a storm approaches. After an event, promptly documenting visible damage and taking reasonable steps to prevent further loss can support a clear insurance claim. Carefully reviewing policy terms, exclusions, and deadlines helps affected property owners understand available coverage and pursue necessary repairs.
Wind And Tornado Damage
Beyond hurricanes and tropical storms, severe wind events and tornadoes can cause sudden, concentrated property damage in Hollywood. Powerful gusts may lift shingles, break windows, damage exterior walls, and topple trees or utility structures. Tornadoes can produce especially intense, localized forces that displace roofing, compromise structural connections, and send debris into buildings. Even when a property remains standing, damage to doors, windows, and roof coverings can leave it exposed to further harm. Routine inspections and prompt documentation of visible damage can help property owners identify concerns and support an accurate insurance claim. Tornado shelter planning can protect occupants when warnings are issued, while wind-resistant landscaping, including properly maintained trees and secured outdoor items, may reduce hazards around a building. A qualified professional can assess damage and explain available policy options.
Flooding And Heavy Rain
When heavy rain overwhelms drainage systems or raises nearby waterways, flooding can damage Hollywood properties with little warning. Water may enter through doors, windows, foundations, or low-lying utility areas, harming flooring, walls, electrical systems, and personal belongings. Saturated ground can also weaken foundations and contribute to structural movement. Floodwater contamination presents additional concerns because runoff may carry sewage, chemicals, and debris into homes or commercial buildings. Prompt assessment helps identify safety hazards and document the full extent of damage before repairs begin. Property owners should take reasonable steps to protect occupants, preserve damaged materials when safe, and keep records of cleanup and repair costs. A qualified claims professional can review policy terms, assess evidence, and help guarantee that affected residents and businesses receive clear guidance during recovery. Proper drainage infrastructure maintenance may reduce future exposure.
Hail And Lightning Damage
Hail can dent metal roofing, crack shingles, break windows, and damage exterior equipment at Hollywood homes and businesses. Hail impact patterns across roofs, siding, and outdoor units can help document the storm’s scope and distinguish recent damage from prior wear. Prompt photographs, inspection records, and preserved damaged materials may support a clear property claim. Lightning can also cause fires, damage wiring, and disrupt appliances or building systems. Lightning surge damage may occur even when no direct strike is visible, so qualified professionals should assess electrical components and connected equipment. Property owners who serve tenants, employees, or customers should address immediate safety concerns, arrange necessary temporary protection, and promptly notify their insurer. Detailed documentation and timely repairs can help limit further loss while supporting an accurate review of covered storm damage.
Legal Rights of Hollywood Property Claim Storm & Weather Damage Injury Victims
Hollywood property owners affected by storms or severe weather may have legal rights under their insurance policies and Florida law. A policy may require prompt notice, reasonable cooperation, and documentation of covered losses. Florida law also sets deadlines and standards for certain claim decisions, although coverage depends on the policy language and facts. Owners can review their declarations, preserve correspondence, and request written explanations of claim determinations. When tenants are displaced or need support, property owners should consider applicable tenant protections and Disability accommodation obligations, while coordinating safe access and repairs.
Key rights and practical steps may include:
- Fair claim review: Insurers must handle claims according to applicable policy terms and legal requirements.
- Claim documentation: Owners may submit photographs, repair estimates, receipts, and other relevant records.
- Dispute options: A denied or underpaid claim may be challenged through available policy procedures or legal channels.
- Responsible assistance: Clear communication can help tenants, neighbors, and vulnerable residents understand next steps.
Because deadlines and remedies vary, qualified legal guidance can help owners protect their interests and serve affected occupants responsibly.
Why Do Hollywood Property Claim Storm & Weather Damage Injuries Happen?
Storm and severe weather injuries at Hollywood properties often result from structural damage, unsafe cleanup conditions, or delayed repairs after an event. High winds can loosen roofing, break windows, and send debris into walkways, while flooding may conceal hazards or weaken floors. These conditions can endanger residents, visitors, and workers who depend on property owners and managers to maintain reasonably safe premises.
Severe weather warning failures may leave occupants without adequate time to prepare for dangerous conditions or seek shelter. In other cases, warnings are issued but not communicated effectively, and emergency procedures are unclear. Climate change and storm intensity can also increase the frequency or severity of damaging events, placing added demands on building maintenance and risk planning.
Injuries may occur when inspections are incomplete, known damage remains unrepaired, or cleanup exposes people to unstable structures, electrical hazards, and slippery surfaces. Understanding these contributing factors helps clarify how preventable property conditions can compound the dangers created by severe weather.
What Should You Do After a Hollywood Property Claim Storm & Weather Damage Injury?
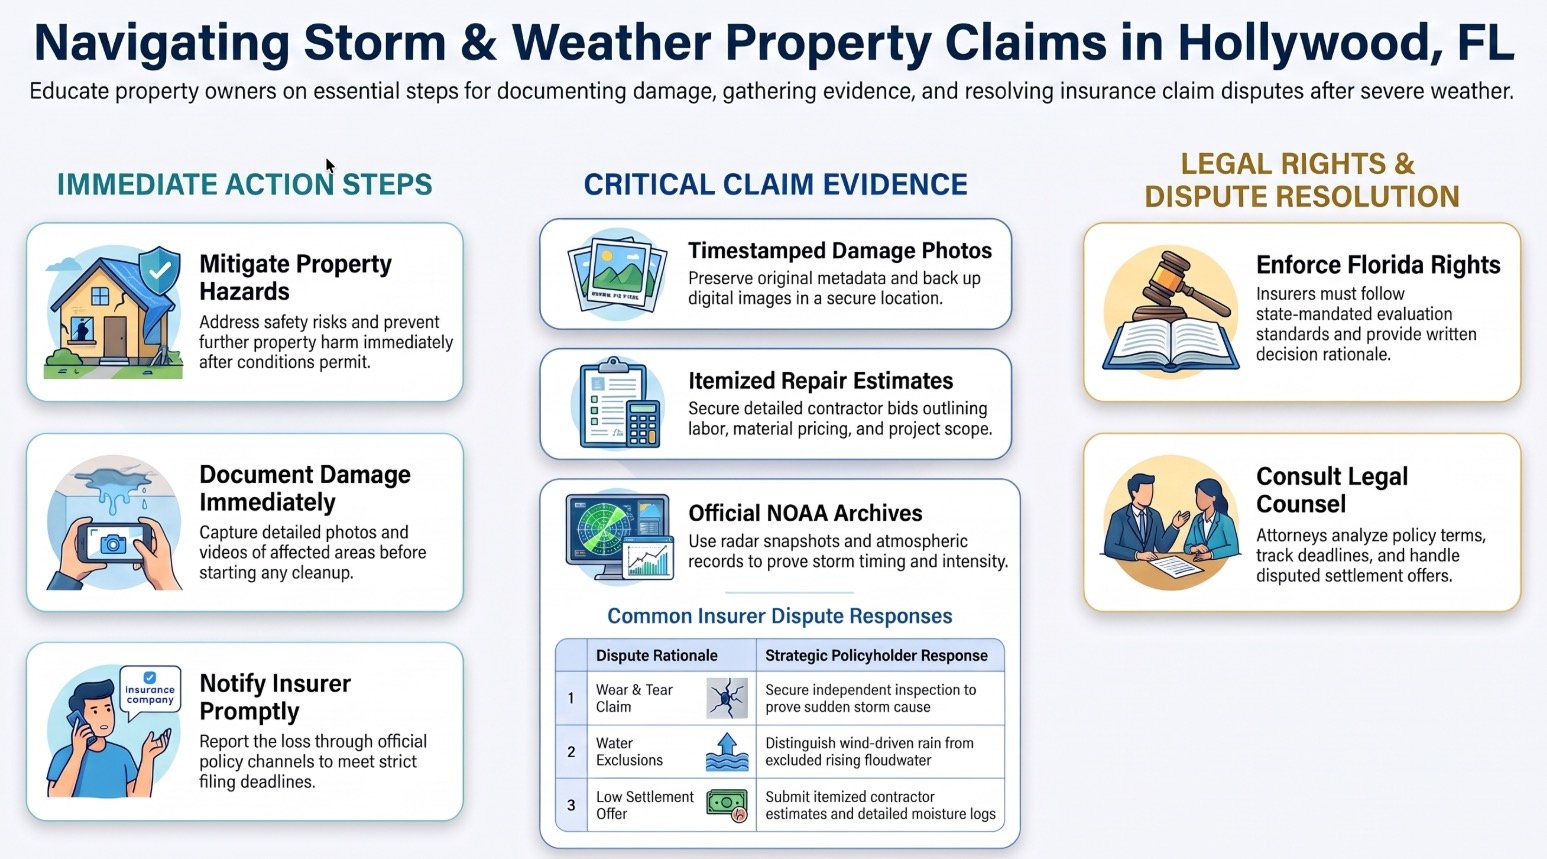
After storm or weather damage, property owners should promptly document affected areas and preserve receipts, photographs, and repair records. They should notify their insurer without delay and provide accurate information about the loss. When a claim is disputed, delayed, or undervalued, consulting a property insurance lawyer can help clarify available options.
Document the Damage
When conditions are safe, a property owner should document storm and weather damage as soon as possible. Clear records can help establish what occurred and support responsible repair decisions that protect occupants, employees, and visitors. Photographs and videos should show affected areas from multiple angles, including close views of damaged materials and wider views that establish their location. The owner should record the date, time, and observed conditions, and avoid entering unstable or contaminated spaces.
A written inventory should list damaged belongings, building components, and any visible signs of water intrusion. Inventory logging can include descriptions, approximate ages, and purchase records when available. Moisture mapping by a qualified professional may identify hidden water and help guide appropriate drying work. Store copies of images, notes, and reports securely and organize them for later reference.
Notify Your Insurer
Prompt notice can help a property owner begin the insurer’s review of storm or weather damage. The owner should promptly notify the insurance company through the method specified in the policy, such as a claims phone line or online portal. Early contact can establish a claim record and allow the insurer to explain required forms, inspections, and supporting materials. The owner should provide accurate information about when the event occurred, the affected areas, and any immediate steps taken to protect people and property. Policy deadlines may apply to reporting damage, submitting proof of loss, or completing other claim requirements, so review the policy without delay. Keeping copies of notices, claim numbers, and communications can support an orderly process and help guarantee the insurer receives consistent, complete information.
Consult a Lawyer
If storm or weather damage has led to a disputed, delayed, or denied property claim, the owner may consult a lawyer familiar with insurance disputes in Hollywood. An Attorney consultation can help clarify policy terms, deadlines, and the insurer’s stated reasons for its decision. The owner should gather the policy, claim correspondence, photographs, repair estimates, inspection reports, and records of related expenses before the meeting. These materials may help counsel assess whether the insurer handled the claim consistently with the policy and applicable requirements. Legal guidance can also explain options for responding to a low settlement offer or requesting further review. A lawyer may communicate with the insurer and help organize evidence, allowing the owner to focus on protecting household members and supporting affected neighbors. No outcome can be guaranteed.
Critical Evidence in a Hollywood Property Claim Storm & Weather Damage Injury Case
Strong evidence can clarify the cause, extent, and value of storm-related property damage. Essential records may include: 1. photographs of the damage, 2. repair estimates, 3. weather records, and 4. witness statements. Preserving these materials promptly can support a clear and well-documented claim.
Storm Damage Photos
Photographs taken soon after a storm can preserve essential evidence of property damage before cleanup or repairs alter the scene. Images should show the full property and clear details of affected areas, including roof damage, fallen branches, broken windows, and water intrusion. Wide views can establish location, while close-ups document specific conditions. A consistent sequence from several angles may help reviewers understand the extent and context of the damage. Photo Metadata, such as dates and times, can support when images were captured; original files should be retained whenever possible. Image Backups stored in a secure location can protect this record if a device is lost or damaged. Take photographs only when conditions are safe, without entering unstable structures or obstructing emergency responders. Organized, accurate images can help claim reviewers assess the reported loss.
Repair Estimates
Repair estimates can help establish the scope and cost of storm-related property damage in a Hollywood claim. A detailed estimate identifies affected areas, necessary repairs, labor, and materials, giving the insurer a clear basis for evaluating the loss. Contractor bids can provide independent assessments and show whether proposed work reflects the property’s actual condition. Comparing bids may also reveal differences in repair methods, project scope, or expected costs that require explanation.
Accurate material pricing matters because replacement costs can change based on quality or availability. Estimates should distinguish repair from replacement and account for applicable building requirements. Photographs and inspection findings can support the listed work and help prevent overlooked damage. Organized, itemized estimates allow property owners and their representatives to present a credible claim, seek a fair settlement, and direct resources toward restoring safe, usable spaces for those who depend on them.
Weather Records
Weather records can help determine whether a storm caused the damage reported at a Hollywood property and when the event occurred. Official NOAA archives may document rainfall totals, wind speeds, hail reports, and severe weather alerts for the relevant location and date. Radar snapshots can show a storm’s path, intensity, and timing, helping connect reported conditions with damage observed at the property. These records may also clarify whether conditions were sudden or developed over time. A careful review should compare the weather data with photographs, inspection findings, and repair estimates, while noting the source and date of each record. Accurate documentation can support a fair assessment of the claim and help property owners pursue repairs that protect occupants, neighbors, and others who rely on a safe building.
Witness Statements
Witness statements can provide important evidence in a Hollywood property claim involving storm damage and injuries. People who saw the storm, property conditions, or an incident may help establish when damage occurred and how an injury happened. Neighbor accounts can describe wind, flooding, falling debris, or hazards that appeared before repairs began. Their observations may also clarify whether the owner received notice of a dangerous condition.
The value of each statement depends partly on eyewitness credibility. A reliable witness should explain what was personally observed, when it occurred, and from what vantage point. Consistent details, prompt reporting, and supporting photographs or records can strengthen an account. Investigators may also compare statements with weather records and repair documents. Careful, respectful interviews preserve useful evidence and help those affected pursue a fair, well-supported claim.
Long-Term Effects of Hollywood Property Claim Storm & Weather Damage Injuries
Storm and weather damage can leave occupants with persistent respiratory problems, particularly when moisture promotes mold or other indoor contaminants. Structural damage may also worsen over time, creating ongoing safety concerns and costly repair needs. These effects can place lasting financial strain on property owners and affected residents.
Persistent Respiratory Problems
After storm or weather damage, persistent respiratory problems may develop when water intrusion, mold growth, or airborne debris affects a property. Mold exposure can irritate the airways and may worsen asthma or other existing conditions, particularly when damp materials remain untreated. Fine particles released during cleanup can also contribute to breathing complications, including coughing, wheezing, chest tightness, or shortness of breath. Symptoms may continue after the immediate weather event, especially if affected areas are not properly dried and cleaned. Residents, workers, and volunteers assisting with recovery should avoid entering contaminated spaces without appropriate protection and seek medical guidance if symptoms persist or worsen. Documenting exposure, symptoms, and cleanup conditions may help clarify the effects of the damage. Prompt professional assessment can support safer remediation and reduce ongoing respiratory risks for everyone affected.
Chronic Structural Damage
Respiratory symptoms are not the only lasting consequence of severe weather damage; a property’s structure may also weaken over time. Hidden moisture can remain inside walls, beneath flooring, or within roof assemblies after visible water has been removed. As materials stay damp, wood may decay, metal fasteners may corrode, and mold may develop, reducing the stability of affected areas. Repeated exposure to wind-driven rain can also loosen roofing, siding, and window components, allowing further water intrusion during later storms. Foundation settlement may follow soil erosion or prolonged saturation, causing cracks, uneven floors, and doors that no longer close properly. These changes can place occupants and visitors at risk, particularly in homes serving families or community members. Prompt inspection and accurate documentation help identify hazards and guide appropriate repairs before structural problems worsen.
Lasting Financial Strain
Although storm-related injuries may recover, their financial effects can continue long after the immediate emergency. In Hollywood, medical expenses, missed work, and repair costs may accumulate while residents seek to restore damaged property and maintain vital services. When insurance payments are delayed or disputed, families may rely on savings, loans, or credit cards to cover urgent needs. Prolonged borrowing can lead to Credit deterioration, limiting access to affordable financing for future housing, transportation, or recovery expenses. Reduced income and continuing costs may also contribute to household instability, particularly when a resident cannot return to work or must relocate during repairs. A property claim lawyer can review coverage, document losses, and address disputes with the insurer. Timely guidance may help residents pursue benefits and protect their longer-term financial security.
Proving Liability in Hollywood Property Claim Storm & Weather Damage Injury Cases
Proving liability in a Hollywood storm or weather damage claim requires evidence connecting the loss to a responsible party’s actions or failure to act. The assessment begins by identifying the source of the damage and determining who controlled or maintained the affected property. Relevant records may include photographs, repair histories, inspection reports, weather data, and witness statements.
Negligence standards require showing that a party owed a duty of reasonable care, failed to meet that duty, and caused a measurable loss. For example, a property owner or manager may be responsible when known drainage problems, damaged roofing, or unsafe structures are left unaddressed despite a reasonable opportunity to act. Severe weather alone does not establish fault; evidence must distinguish unavoidable conditions from preventable hazards.
Third-party liability may arise when a contractor, neighboring property owner, or maintenance provider contributed to the damage. Careful documentation and qualified inspections can clarify how the event occurred, preserve useful evidence, and support a fair determination of responsibility. These steps help affected communities seek accountability and restore safe conditions.
Dealing With Insurance Companies After a Hollywood Property Claim Storm & Weather Damage Injury
After storm or weather damage in Hollywood, insurance companies typically review the policy, investigate the cause of loss, and assess the claimed repairs. Property owners can support a fair review by providing accurate information and preserving records of damaged areas, repair estimates, photographs, and related expenses. Clear documentation helps explain how the event affected the property and what work may be needed to restore it.
Adjuster communications should remain factual, timely, and organized. Owners may request written explanations of inspection findings, estimates, and decisions, then compare those materials with contractor assessments and policy terms. If information is incomplete or inconsistent, a concise written response can identify the specific concern and provide supporting evidence. Coverage disputes may arise over exclusions, deductibles, causation, or the scope of repairs. Careful review of the policy and claim correspondence can clarify the basis for disagreement. When questions remain, qualified legal guidance may help protect the owner’s interests while supporting a responsible resolution for everyone affected.
What to Expect During a Hollywood Property Claim Storm & Weather Damage Injury Claim Process
A storm or weather damage claim typically begins with an initial review of the policy, reported losses, and available evidence. The property owner then documents the damage while the insurer investigates the cause and extent of the loss. The process may conclude with a settlement, or proceed to a dispute if the parties disagree about coverage or compensation.
Initial Claim Review
During the initial claim review, the insurer evaluates the reported storm or weather damage, the available evidence, and the policy terms that may apply. This stage helps determine whether the reported loss falls within the insured property’s coverage and what steps may follow. Coverage verification includes checking the policy period, covered locations, limits, deductibles, and any conditions relevant to the claim. The insurer may also consider policy exclusions, which can restrict coverage for particular causes or circumstances. Claimants should review notices carefully and respond to reasonable requests for information within stated deadlines. Clear communication can help prevent avoidable delays and support a fair assessment. If coverage terms are unclear or the insurer raises questions about eligibility, a qualified professional may explain the applicable provisions and available options. The initial decision does not necessarily resolve every issue.
Damage Documentation
Once the insurer has reviewed the claim and relevant policy terms, documenting the storm damage can help establish the scope and timing of the loss. Property owners may photograph affected rooms, exterior surfaces, and damaged belongings before cleanup or repairs alter their condition. Images should include dates when available and show both close details and the wider area. Written notes can record when damage appeared, which areas were affected, and steps taken to prevent further loss. Moisture mapping may help identify water intrusion and trace its spread through walls, floors, or ceilings. A contents inventory should list damaged items, their approximate age and value, and any available purchase records. Organized documentation can support accurate claim discussions and help property owners account for losses while preserving safe, usable spaces for occupants and neighbors.
Insurer Investigation
The insurer’s investigation typically begins with a review of the policy, claim details, and available damage records. An adjuster may inspect the property, photograph affected areas, and compare observed conditions with the reported storm event. The review can include repair estimates, maintenance history, weather data, and statements from people familiar with the damage. The insurer may request recorded statements from the policyholder or witnesses; answers should be accurate and limited to what they know. If questions arise about policy terms or the cause of loss, the insurer may issue coverage reservations explaining that its review continues without waiving applicable rights. The policyholder can provide requested information, retain copies of communications, and arrange reasonable access for inspections. Clear, organized cooperation helps the investigation assess the claim and the property’s documented needs.
Settlement or Dispute
If the insurer accepts the claim, settlement discussions typically focus on the covered damage, the reasonable cost of repairs, and any applicable policy limits or deductibles. The property owner should review estimates, photographs, invoices, and policy terms before evaluating Settlement Offers. A fair resolution should account for necessary repairs and documented losses without including costs excluded by the policy. If the insurer disputes the cause, scope, or value of damage, the owner may provide additional records or request a written explanation of the decision. Dispute Resolution can involve further negotiation, an appraisal process when permitted by the policy, or legal action if other efforts fail. Clear, timely communication can help prevent avoidable delays. A lawyer may assess the coverage position, explain available options, and support a resolution that protects the owner’s interests.
Compensation for Hollywood Property Claim Storm & Weather Damage Injury Damages
When a storm damages a Hollywood property, compensation may cover reasonable repair or replacement costs, damaged personal belongings, and additional living expenses when the home is temporarily uninhabitable. The available payment depends on the policy’s terms, coverage limits, deductibles, and the evidence supporting the claim.
A property owner may need to document damage promptly with photographs, inventories, receipts, repair estimates, and records of communications with the insurer. These materials can help establish the extent of covered losses and support a fair assessment. If repairs require the household to leave, eligible Temporary housing expenses may include reasonable lodging and related costs, subject to policy conditions and limits. Coverage for personal belongings may depend on whether items can be repaired, their replacement value, and applicable depreciation provisions.
Insurers may request inspections or additional documentation before issuing payment. Careful review of settlement calculations can identify omissions, disputed estimates, or overlooked expenses. Clear records and timely responses can help property owners pursue benefits while preserving resources needed to restore safe, usable living conditions.
Economic vs Non-Economic Damages in Hollywood Property Claim Storm & Weather Damage Cases
Economic losses may include repair costs, replacement expenses, and other documented financial effects of storm or weather damage. Non-economic harm can involve disruption, inconvenience, or loss of use, subject to the terms of the policy and applicable law. Establishing either category generally requires clear evidence linking the claimed damages to the covered event.
Economic Losses
Storm and weather damage can create both direct financial costs and losses that are harder to measure. Economic losses are financial amounts that can be documented and tied to property damage or interrupted operations. They may include repair expenses, replacement costs for damaged equipment or inventory, emergency mitigation, and reasonable temporary relocation expenses. For a business serving the Hollywood community, Business interruption may also result in lost profits while the property is repaired or access is limited. Records such as invoices, payroll reports, tax returns, and sales histories can help establish the amount and duration of these losses. Policy terms, coverage limits, deductibles, and exclusions may affect whether particular expenses qualify for payment. A careful claim assessment identifies supported costs and connects them to the covered storm or weather event.
Non-Economic Harm
Non-economic harm refers to personal effects that are not measured as direct financial costs, such as stress, disruption, or loss of use after storm damage to a Hollywood property. Unlike repair expenses or temporary housing costs, these effects concern how damage changes daily life and the property’s role in providing comfort, stability, or community connection. Emotional distress may arise when residents face uncertainty, displacement, or repeated interruptions to ordinary routines. Diminished enjoyment can also occur when a home or business no longer supports the activities and relationships it once accommodated. These impacts may affect residents, tenants, or owners differently, depending on the property’s use and the disruption’s duration. Recognizing non-economic harm allows a claim to reflect personal consequences alongside measurable financial losses, without treating the two categories as interchangeable.
Proving Damages
How damages are documented can shape the evaluation of a Hollywood property claim after storm or weather damage. Economic losses may include repair costs, damaged contents, temporary housing, and lost rental income. Receipts, contractor estimates, photographs, inventories, and financial records can help connect these expenses to the event. Damage valuation should distinguish covered storm-related harm from preexisting conditions and account for reasonable repair methods. Mitigation expenses, such as emergency tarping or water removal, may also be relevant when supported by invoices and evidence of prompt action. Non-economic harm may involve disruption, stress, or loss of use, although its recognition depends on the policy and applicable law. Clear, organized records allow insurers and decision-makers to assess both measurable costs and claimed personal impacts fairly, while supporting a complete and credible account of the property loss.
When a Hollywood Property Claim Storm & Weather Damage Injury Case Goes to Trial vs Settlement
Whether a Hollywood property claim involving storm or weather damage proceeds to trial or settles depends on the evidence, the extent of the loss, and the insurer’s position. A settlement may resolve the dispute without a courtroom hearing when both sides reach an acceptable agreement on coverage and compensation. Settlement negotiation can involve reviewing repair estimates, photographs, inspection findings, and other records to assess the claimed damage and address valuation differences.
If negotiations do not produce a fair resolution, the policyholder may pursue the claim in court. Trial preparation then includes organizing supporting documents, identifying relevant witnesses, and presenting evidence about the property’s condition and the loss. A judge or jury evaluates the evidence and decides disputed issues. The process can require additional time and expense, so the decision to proceed is generally based on the claim’s circumstances and available proof. Clear records and careful preparation can help policyholders pursue a resolution that supports their household and community responsibilities. Neither path guarantees a particular outcome.
Florida Laws That May Affect Your Hollywood Property Claim Storm & Weather Damage Case
Florida law can affect a Hollywood property owner’s storm damage claim by setting deadlines, defining policyholder duties, and governing coverage disputes. These requirements can influence how a claim is documented and evaluated, while helping owners pursue resources needed to restore homes and protect their households.
- Florida insurance deadlines may govern when an insurer must acknowledge, investigate, and decide a claim. Policyholders should review current requirements and retain dated communications.
- Policies commonly require prompt notice, reasonable access for inspection, and records of damage and repair costs. Accurate documentation can support a fair review.
- Hurricane deductible rules may apply when a covered loss results from a qualifying hurricane. The policy’s terms determine how the deductible is calculated and applied.
- Florida law regulates insurer conduct and provides procedures for addressing coverage disagreements. A careful review of the policy, estimates, and claim correspondence can clarify disputed issues.
Because requirements depend on policy language and circumstances, owners may seek qualified guidance before responding to an insurer or accepting a settlement offer.
The Statute of Limitations for Hollywood Property Claim Storm & Weather Damage Injury Cases
Beyond policy requirements and claim-handling rules, filing deadlines can affect a Hollywood property owner’s ability to challenge an insurer’s decision over storm or weather damage. Florida law sets time limits for certain insurance disputes, and the applicable period may depend on the claim type and when the cause of action accrued. Missing a deadline can prevent a court from considering the dispute, even when damage is substantial.
Deadline calculation can be complicated by statutory changes, policy language, and the facts surrounding the loss or denial. A property owner should distinguish deadlines for giving notice of a claim from deadlines for filing a lawsuit. These are separate requirements and may arise at different stages.
Policy exceptions or other legal circumstances may affect how a limitation period applies, but they should not be assumed. Records of the storm, discovery of damage, communications, and insurer decisions can help clarify relevant dates. Prompt attention to these timelines supports fair, timely resolution and protects resources needed for homes and communities.
How a Hollywood Property Claim Storm & Weather Damage Lawyer Can Help You
A Hollywood property claim storm and weather damage lawyer can help property owners evaluate coverage, document losses, and respond to an insurer’s decision. By explaining policy terms and available options, counsel can help clients protect homes, businesses, and resources that support employees, tenants, and local communities. Policy interpretation may clarify how the contract addresses wind, rain, flooding, or related damage, while careful review can identify coverage exclusions and disputed findings.
A weather damage lawyer can clarify coverage, document losses, and help property owners respond to disputed insurance decisions.
A lawyer may assist by:
- Reviewing the policy, endorsements, limits, and exclusions relevant to the reported loss.
- Organizing photographs, repair estimates, receipts, inspection reports, and other claim evidence.
- Comparing the insurer’s damage assessment with independent findings and applicable policy language.
- Preparing clear communications, challenging unsupported conclusions, and pursuing available resolution options.
This support can help property owners make informed decisions and present a well-documented claim. Counsel can also explain potential consequences of settlement terms, preserving the client’s ability to weigh choices that serve occupants, staff, and others who depend on the property.
When to Contact a Hollywood Property Claim Storm & Weather Damage Lawyer
When should a property owner contact a Hollywood property claim storm and weather damage lawyer? Contact can be appropriate as soon as significant storm damage appears, especially when the insurer delays an inspection, disputes the cause or scope of loss, requests extensive documentation, or issues a denial or payment that seems incomplete. Early guidance may help the owner understand deadlines and preserve relevant records while repairs and community needs are being addressed.
Before a consultation, the owner can gather the policy, claim correspondence, photographs, repair estimates, inspection reports, and a dated account of events. This consultation preparation allows counsel to assess the claim more efficiently and identify information that may still be needed. Questions about Attorney fee structures should also be raised, including how fees are calculated, whether costs are separate, and what payment obligations may arise. Prompt, organized communication can help property owners make informed decisions while coordinating recovery efforts and maintaining safe, usable spaces for residents, employees, and neighbors.
Why You Need an Experienced Hollywood Property Claim Storm & Weather Damage Lawyer
Because storm and weather claims can involve complicated policy terms, disputed damage assessments, and strict deadlines, an experienced Hollywood property claim lawyer can help property owners evaluate their options. Legal guidance can clarify coverage provisions, identify documentation gaps, and explain how an insurer’s decisions may affect recovery. This support is particularly valuable when damage threatens a home, business, or community resource that others depend on.
An attorney can organize repair records, photographs, estimates, and communications into a clear claim presentation. Careful claim strategy may help address disagreements about the cause or extent of damage and support a reasoned response to a low or delayed payment. Counsel can also track required deadlines and communicate with the insurer, reducing the risk that procedural issues will distract owners from protecting people and property.
Through Policyholder advocacy, an experienced lawyer can help ensure the claim receives a fair, evidence-based review. This guidance enables property owners to make informed decisions while pursuing recovery responsibly and preserving resources needed for household stability, business continuity, and service to others.
How to Choose the Right Hollywood Property Claim Storm & Weather Damage Lawyer for Your Case
Choosing the right Hollywood property claim storm and weather damage lawyer requires careful attention to the attorney’s experience, communication, and approach to disputed claims. A property owner can review Attorney credentials, including licensing, relevant training, and a record of handling storm-related insurance disputes. Experience with claims involving wind, flooding, roof damage, or denied coverage may help an attorney identify issues that warrant close review.
The attorney’s communication style also matters. Clear explanations of policy terms, deadlines, evidence, and possible next steps can help property owners make informed decisions and maintain realistic expectations. A prospective client may ask how often updates are provided, who will answer questions, and how the lawyer evaluates an insurer’s position.
It is also useful to discuss fees, anticipated costs, and the documents needed to assess the claim before making a decision. A careful comparison of qualifications and working practices can help a property owner select counsel suited to the claim and its circumstances.
About The Law Offices of Anidjar & Levine
The Law Offices of Anidjar & Levine represents clients in property insurance disputes, including claims involving storm and weather damage. The firm assists property owners seeking a fair review of damage claims and clear answers about available legal options. Its work may include examining policy terms, documenting losses, communicating with insurers, and addressing disputes over coverage or payment.
Firm history provides context for understanding the firm’s approach to client representation. The attorneys handle matters across several areas of law, including insurance and property loss cases. Their role is to assess the circumstances, explain relevant procedures, and help clients make informed decisions while pursuing a resolution.
Attorney values include attentive service, professional responsibility, and respect for each client’s concerns. These principles can matter to homeowners facing uncertainty after severe weather, when timely information and organized claim handling are important. The firm’s representatives can discuss a property owner’s situation, identify potential next steps, and explain what documentation may support a claim. Each matter depends on its facts, policy language, and applicable law.
Frequently Asked Questions
Does Homeowners Insurance Cover Flood Damage From a Storm in Hollywood, Florida?
Homeowners insurance generally does not cover flood damage from a storm in Hollywood, Florida. Standard policies may cover wind-driven rain or other storm damage, but rising water, coastal flooding, and storm surge are typically excluded. Separate flood insurance coverage may help pay for covered damage, subject to policy limits, deductibles, and exclusions. Residents should review their policy promptly and document losses, since coverage depends on the water’s source and the policy terms.
What Should I Do if My Insurer Says Storm Damage Was Caused by Wear and Tear?
When an insurer attributes storm damage to wear and tear, the policyholder should request the written denial and the specific policy provisions supporting it. They should preserve damaged materials, photograph conditions, and gather maintenance records and storm-date evidence. Requesting an Independent Inspection by a qualified professional can help distinguish sudden damage from gradual deterioration. Challenging the wear-and-tear denial may require submitting a detailed report and asking the insurer to reconsider its decision in writing.
Can I Reopen a Property Claim After Discovering Hidden Storm Damage?
A property claim may be reopened or supplemented when a later inspection reveals storm damage that was not reasonably visible during the initial assessment. The policyholder should promptly notify the insurer, review applicable supplemental claim deadlines, and preserve documentation of hidden damage, including dated photographs, inspection reports, repair estimates, and records of mitigation work. The insurer may reassess the loss under policy terms, but coverage is not guaranteed; timely, organized evidence can support a fair review.
Will Filing a Storm Damage Claim Increase My Homeowners Insurance Premiums?
Filing a storm damage claim may increase homeowners insurance premiums, but an increase is not automatic. Premium impact depends on the insurer’s rules, state regulations, claim details, and whether the policyholder has filed prior claims. Claim frequency can affect renewal pricing or eligibility, while severe weather events may influence rates across an area regardless of individual claims. Policyholders should review their coverage and consult their insurer before deciding how to proceed with a claim.
Can I Hire a Public Adjuster to Assess My Storm-Related Property Damage?
Yes, a property owner may hire a licensed public adjuster to assess storm-related damage and assist with an insurance claim. The Public adjuster’s inspection process typically includes documenting visible damage, reviewing relevant policy terms, and preparing an estimate for covered repairs. Before signing an agreement, the owner should understand public adjuster fee structures, which may involve a percentage of the settlement. Licensing, fees, and contract terms should be verified carefully.
—————————
Storm and weather damage claims can involve complicated policy terms, strict deadlines, and disputes over the cause or value of a loss. Property owners should document damage, preserve relevant records, and avoid assumptions about coverage before reviewing their options. An experienced Hollywood property claim lawyer can assess the circumstances, explain applicable rights, and communicate with the insurer. The Law Offices of Anidjar and Levine represents clients seeking a fair resolution and provides guidance throughout the claims process. Learn more about a Hollywood Personal Injury Lawyer.