A judge forced State Farm to unseal internal documents on hail claims. Here’s what they allegedly show, and why Florida policyholders should pay attention.
Was your roof or storm damage claim denied or underpaid? Call The Law Offices of Anidjar & Levine at 1-800-747-3733 for a free case review. We don’t charge a fee unless we recover for you.
Main Takeaways
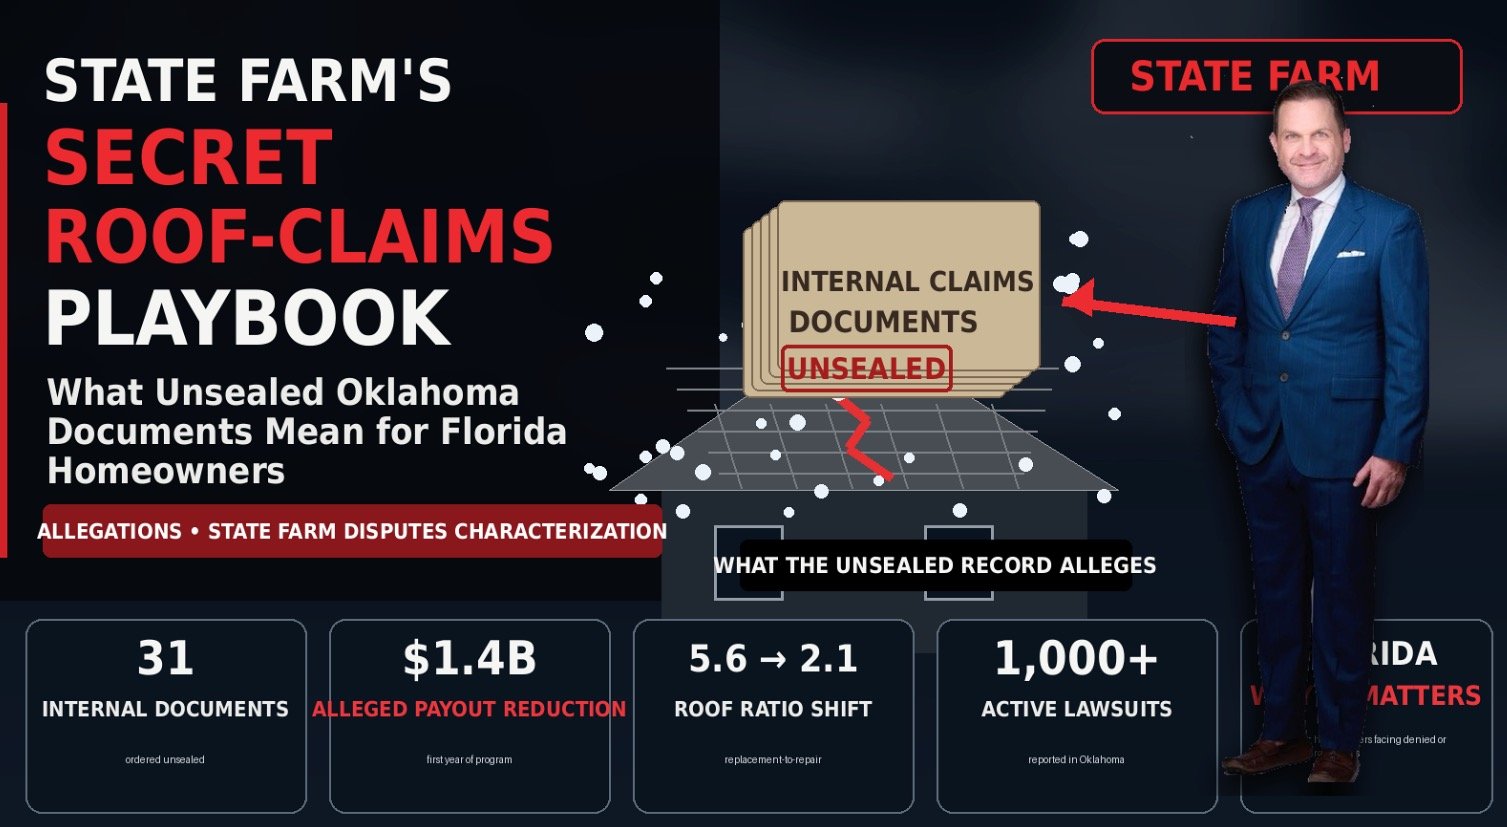
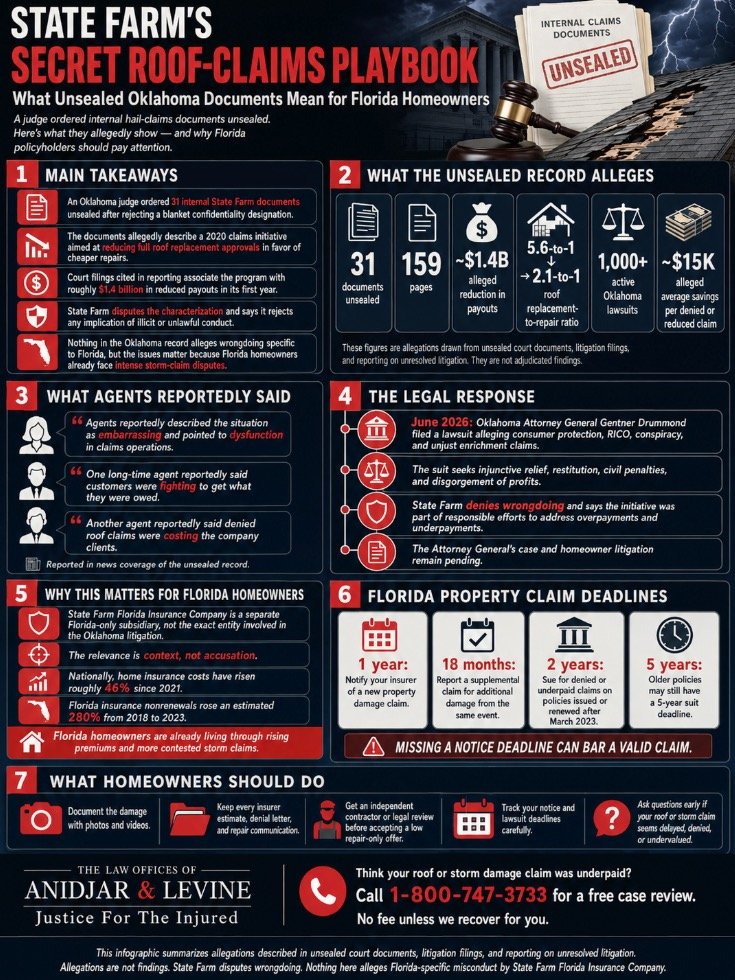
- A Comanche County, Oklahoma judge ordered State Farm to unseal 31 internal documents after ruling the company’s blanket confidentiality designation violated state law.
- The documents allegedly show a 2020 internal program, described in reporting as a “Wind/Hail Initiative,” aimed at reducing full roof replacement approvals. Oklahoma’s Attorney General has sued separately over what his office calls a “Hail Focus Initiative,” alleging racketeering and consumer protection violations.
- According to court filings cited in national reporting, the program is associated with roughly $1.4 billion in reduced payouts in its first year, and State Farm’s roof-replacement-to-repair ratio allegedly fell from 5.6-to-1 before the program to 2.1-to-1 after.
- State Farm disputes the characterization, saying it “strongly reject[s] any implication or political narrative that State Farm engages in illicit or unlawful conduct,” and describes the program as correcting both overpayments and underpayments.
- None of this is about Florida conduct specifically. But State Farm Florida Insurance Company, a separate subsidiary in the same corporate family, remains an active homeowners insurer here, and Florida has a long history of storm-claim disputes worth understanding.
What the Unsealed Documents Allegedly Show
According to reporting on court filings, State Farm launched an internal claims initiative in Texas in June 2020 and expanded it to Oklahoma within six months. Internal documents describe the goal as reducing the number of full roof replacements approved after wind and hail damage, in favor of cheaper repairs. A State Farm senior leader, identified in unsealed materials as a 27-year company veteran, reportedly flagged full roof replacements as the company’s “biggest bucket of opportunity” for reducing payouts, citing Accenture consulting data that put national roof-replacement rates far below what State Farm had historically approved. State Farm’s own attorneys later told the court they could not verify that consulting data.
A Comanche County judge presiding over consolidated bad-faith litigation originally allowed State Farm to designate roughly 800,000 documents as confidential. After reviewing the material, the judge ordered a subset, 31 documents totaling 159 pages, unsealed, finding the blanket confidentiality claim was not supported under Oklahoma law. Those documents now form the basis for reporting on the case and are part of the evidentiary record homeowners’ attorneys are using in more than 1,000 active lawsuits.
What State Farm’s Own Agents Reportedly Said
Some of the more striking material in the unsealed record isn’t from homeowners or their lawyers, but from State Farm’s own captive agents, writing to the company. According to letters embedded in the unsealed documents and reported by The Nation, an Ohio-based agent described the claims handling situation as “terribly embarrassing for State Farm” and pointed to “dysfunction within our SF claims operations.” A Kentucky-based agent, describing decades of loyalty to the company, reportedly wrote that its reputation had become comparable to a competitor’s, adding: “We now pay really low and customers fight to get what we owe them.” A third agent, in Ohio, reportedly said losing multiple clients over denied roof claims was “the first time in my 15 years I have had any issue with claims.”
“The old slogan of ‘we pay what we owe, not a penny less, not a penny more’ is not the case right now.” — a State Farm agent, in a 2021 letter reported as part of the unsealed record
These are letters from company agents as characterized in news reporting on unsealed litigation documents, not court findings, but they add internal, contemporaneous color to the allegations being litigated.
The Legal Response: An Attorney General’s RICO Lawsuit
In June 2026, Oklahoma Attorney General Gentner Drummond filed a separate lawsuit against State Farm in Cleveland County District Court, alleging violations of the state’s Consumer Protection Act and its Racketeer-Influenced and Corrupt Organizations Act, along with civil conspiracy and unjust enrichment claims. The suit seeks injunctive relief, civil penalties, restitution, and disgorgement of profits. “This case is about more than individual claim disputes,” Drummond said in announcing the suit. “The allegations describe a corporate scheme that threatens the integrity of Oklahoma’s insurance marketplace.”
State Farm has firmly disputed the allegations. In response to the broader litigation, the company has said it “strongly reject[s] any implication or political narrative that State Farm engages in illicit or unlawful conduct,” and its attorneys have characterized the 2020 initiative as “neither sinister nor surprising, but part of corporate responsibility,” intended to correct both overpayments and underpayments industry-wide. The company also points to more than $1 billion paid to Oklahoma customers over a two-year period as evidence it continued meeting its obligations. No court has resolved these claims on either side. The Attorney General’s case and the consolidated homeowner lawsuits remain pending, with depositions of senior State Farm leadership reportedly scheduled.
Why This Matters for Florida Homeowners
To be clear: nothing in the Oklahoma record alleges wrongdoing specific to Florida. State Farm Florida Insurance Company is a separate, Florida-only subsidiary with its own regulatory filings, and it continues to write new homeowners policies here, though underwriting is notably selective around older roofs, older homes, and coastal exposure. It is a different legal entity than the one named in the Oklahoma litigation, even though both operate under the State Farm name and corporate umbrella.
What makes this relevant to Florida homeowners anyway is context, not accusation. Florida has its own long, well-documented history of disputes over storm and roof damage claims, and the same industry-wide pressures described in the Oklahoma litigation, rising reinsurance costs, more frequent severe weather, and profitability targets, apply here too. Nationally, home insurance costs have risen roughly 46% since 2021, about three times the rate of inflation, and Florida has seen insurance nonrenewals surge an estimated 280% between 2018 and 2023, among the steepest increases in the country. Whatever a Florida court eventually finds true or untrue about a sister company’s practices in Oklahoma, the broader pattern, rising premiums paired with more contested claims, is something Florida policyholders are already living through.
Florida’s Own Property Claim Deadlines
If you have storm or roof damage in Florida, the deadlines that apply differ from those in the Oklahoma litigation, and they are unforgiving. Under Florida Statute 627.70132, you generally must notify your insurer of a new property damage claim within one year of the date of loss, and report a supplemental claim for additional damage from the same event within 18 months. If your insurer denies or underpays the claim and you need to sue, the deadline is 2 years from the date of loss for policies issued or renewed after March 2023, or 5 years for older policies. Missing the notice deadline can bar the claim entirely, regardless of how legitimate the damage is.
About The Law Offices of Anidjar & Levine
Founded in 2005 by Marc Anidjar and Glen Levine, the firm began as a two-person operation working out of a construction office conference room. Over the past 20 years, that modest start has grown into one of Florida’s most recognized personal injury practices — with more than $1 billion recovered in settlements on behalf of injury clients across the state. We bring that same determination and depth of experience to every case we handle.
We don’t represent insurance companies. We represent people, including Florida homeowners who believe a storm or roof damage claim was denied, delayed, or undervalued.
What To Do If You Think Your Storm Claim Was Shortchanged
- Report new damage to your insurer within one year of the loss, and any supplemental damage within 18 months, to protect your claim under Florida law.
- Keep your own photos, contractor estimates, and copies of every letter or estimate the insurer sends you.
- Before accepting a repair-only offer on what looks like replacement-level damage, get an independent opinion from a contractor or an attorney on whether the offer matches the actual damage.
- Track your 2-year (or 5-year, for older policies) suit deadline from the date of loss, and don’t wait until it’s close to get advice.
- A free consultation with an attorney costs nothing and can tell you whether your denial or offer is worth challenging.
Think your roof or storm damage claim was underpaid? Call The Law Offices of Anidjar & Levine at 1-800-747-3733 for a free, no-obligation case review. We don’t charge a fee unless we recover for you. Hablamos español.
Frequently Asked Questions
Is State Farm Florida Insurance Company the same entity being sued in Oklahoma?
No. The Oklahoma lawsuits and unsealed documents involve State Farm’s property insurance operations in Oklahoma. State Farm Florida Insurance Company is a separate, Florida-specific subsidiary that still writes new homeowners policies in the state, though both are part of the same corporate family. Nothing here alleges Florida-specific misconduct; the relevance is what the documents suggest about the parent company’s broader claims-handling approach.
Has a court found that State Farm committed fraud in Oklahoma?
Not yet. The Oklahoma Attorney General’s lawsuit, filed in June 2026, alleges violations of the state’s Consumer Protection Act and Racketeer Influenced and Corrupt Organizations Act, among other claims, and is pending. Homeowner lawsuits, including consolidated bad-faith claims, are also ongoing. State Farm has denied wrongdoing. These remain allegations until a court rules or the cases resolve.
How long do I have to file a homeowners insurance claim in Florida?
Under Florida Statute 627.70132, you generally must notify your insurer of a new property damage claim within one year of the date of loss, and report a supplemental claim for additional damage from the same event within 18 months. If you need to sue your insurer over a denied or underpaid claim, the deadline is 2 years from the date of loss for policies issued or renewed after March 2023, or 5 years for older policies.
What did State Farm say in response to the Oklahoma allegations?
State Farm has publicly rejected any suggestion of illegal conduct, stating it strongly rejects any implication that it engages in illicit or unlawful conduct, and has characterized its 2020 claims program as an effort to correct both overpayments and underpayments rather than a scheme to underpay claims. The company also points to more than $1 billion paid to Oklahoma customers over a two-year period.
My State Farm roof claim was denied or the offer seemed too low. What should I do?
Document the damage thoroughly, keep a copy of your insurer’s estimate and any denial letter, and have an independent adjuster or attorney review it before you accept or sign anything. A free consultation can help you determine whether the offer reflects the actual cost of repair or replacement.
This article discusses ongoing, unresolved litigation and a pending civil law enforcement action. Statements describing State Farm’s alleged conduct are drawn from unsealed court documents, litigation filings, and news reporting on that litigation, and are allegations, not adjudicated facts, unless specifically described as a court ruling. State Farm disputes characterizations of its conduct as improper or unlawful and has offered its own account, portions of which are quoted above. This article does not allege that State Farm Florida Insurance Company engaged in any wrongdoing and does not constitute legal advice or a guarantee of any outcome or recovery amount in any case. The hiring of a lawyer is an important decision that should not be based solely upon advertisements. Before you decide, ask us to send you free written information about our qualifications and experience.
Sources:The Nation – State Farm Is Embroiled in Scandal · KFOR / Yahoo Finance – State Farm Secret Documents Revealed · Oklahoma Watch – The Secret Documents · Oklahoma Attorney General – Official Press Release · NPR – Lawsuits Accuse State Farm