The Law Offices of Anidjar and Levine help Fort Myers property owners address storm and weather damage claims and understand their options when unsafe conditions cause injuries. We can help you document property damage, review policy terms and deadlines, respond to insurer requests, and assess disputes over repair costs, delays, or reduced payments. If a fall or other injury may involve a property owner’s failure to address a foreseeable hazard, we can evaluate the evidence and potential remedies. Learn steps to protect your claim and rights with a Fort Myers Personal Injury Lawyer.
Main Takeaways
- A Fort Myers property-claim lawyer can review storm damage, policy terms, deadlines, exclusions, and flood provisions.
- Report damage promptly, document the claim, and keep the claim number and all insurer communications.
- Preserve dated photos, weather alerts, repair estimates, inventories, invoices, and expenses for temporary living.
- Take reasonable steps to prevent further damage, but avoid unsafe areas and permanent repairs before assessment.
- A lawyer can help challenge disputed estimates or claim denials and explain available options under Florida law.
How We Can Help With Your Fort Myers Property Claim Storm & Weather Damage Injury Claim
When a storm damages your Fort Myers property, we can help you document the loss, review your insurance policy, and pursue the benefits you’re entitled to receive. We’ll organize photographs, repair estimates, receipts, and other records to present a clear account of the damage. Our team can explain relevant policy provisions, identify deadlines, and help you understand what information your insurer needs.
We develop a Coverage strategy based on your property’s condition, the available evidence, and your policy terms. We can prepare and submit claim materials, respond to documentation requests, and address questions about the scope or value of repairs. If the insurer’s assessment doesn’t reflect the documented loss, we’ll explain your options and support you through claim negotiation.
Throughout the process, we’ll communicate clearly, treat your concerns with respect, and work to protect your interests. By managing complicated claim requirements, we help you focus on restoring your property and supporting the people who depend on you.
OUR CONSULTATIONSARE FREE
START YOUR FREE CASE REVIEW
Understanding Fort Myers Property Claim Storm & Weather Damage Injury Cases
Storms and severe weather can cause roof, structural, and water damage, leading to disputes over what your insurance policy covers. We help you understand how the policy applies to your property and what evidence may support your claim. Insurers review the reported damage, policy terms, and documentation before deciding whether to pay benefits. Their decision may not reflect the full scope of covered repairs, so careful review matters.
Policy exclusions can limit coverage, but an insurer must apply them according to the policy language and relevant facts. We can help you examine the explanation for a denial or reduced payment and identify questions that need answers. If you and the insurer disagree about the amount of loss, a claim appraisal may provide a process for resolving that valuation dispute. We’ll explain the available steps, help you preserve key records, and support your efforts to secure a fair outcome while protecting the resources needed to restore your home and support your family.
Common Causes of Fort Myers Property Claim Storm & Weather Damage
Fort Myers property damage claims often arise from hurricanes and tropical storms, which can bring destructive winds and heavy rain. We also see losses caused by tornadoes, flooding, storm surge, hail, and lightning strikes. Identifying the source of damage can help us assess which parts of your property claim need attention.
Hurricane and Tropical Storms
Hurricanes and tropical storms can cause extensive property damage in Fort Myers through high winds, wind-driven rain, flooding, and flying debris. These systems may also bring storm surge, prolonged rainfall, and power outages that disrupt homes, businesses, and vital community services. When damage occurs, we can help you understand your insurance policy, document losses, and communicate with your insurer so your claim reflects the harm your property sustained. Prompt reporting and careful records can support a clearer review, while photographs, repair estimates, and receipts may help establish the extent of loss. Storm preparedness and evacuation planning can protect people and reduce avoidable risks before a storm arrives. Afterward, we encourage you to prioritize safety, prevent further damage when possible, and seek guidance if an insurer delays, disputes, or undervalues your claim.
Wind and Tornado Damage
High winds and tornadoes can damage Fort Myers properties in seconds, tearing off roofs, breaking windows, and sending debris into homes and businesses. Even when a storm passes quickly, its force can weaken structural components and leave a building unsafe. Wind pressure can lift roofs, loosen shingles, or separate roofing materials from the underlying structure. Flying branches and other objects can cause debris-impact damage, puncturing walls, damaging vehicles, and breaking doors or windows. We can help you document visible damage, preserve repair records, and understand the steps involved in presenting a property claim. Prompt inspections matter because hidden damage may worsen if left unaddressed. By carefully reviewing the policy, evidence, and insurer’s assessment, we can help you pursue a fair resolution and protect the people who depend on your property.
Flooding and Storm Surge
When heavy rain or coastal waters overwhelm drainage systems and shorelines, flooding and storm surge can damage Fort Myers homes and businesses. Rising water may enter through doors, windows, foundations, and damaged roofs, ruining flooring, electrical systems, furniture, and vital records. Saltwater can corrode building materials, while Floodwater contamination may expose occupants and workers to sewage, chemicals, and other hazards. We can help you document visible damage, protect receipts, and report losses promptly to your insurer. Keep people away from standing water until qualified professionals confirm the property is safe. Review your policy’s flood provisions and deadlines, since standard homeowners coverage may not cover flood losses. Storm surge mapping can help explain a property’s exposure, but insurers still need evidence connecting the reported damage to the event. Preserve photographs and repair estimates.
Hail and Lightning Strikes
Hail and lightning can damage Fort Myers properties even when a storm passes quickly. Hail impact may crack roof tiles, dent metal panels, break windows, and damage siding. These openings can let rain inside, further damaging insulation, ceilings, and belongings. We encourage you to photograph visible damage and take reasonable steps to protect the property without risking anyone’s safety.
Lightning ignition can start a fire, while a nearby strike may damage wiring, appliances, or electronic systems without visible flames. We recommend keeping repair receipts, inspection reports, and records of damaged items. If you serve tenants, employees, or community members, prompt repairs can help protect their safety and limit disruption. We can help you review policy terms, document losses, and understand the next steps in pursuing a property claim.
Don’t Wait. Call Our Florida Personal Injury Lawyers Now!
Legal Rights of Fort Myers Property Claim Storm & Weather Damage Injury Victims
Fort Myers property owners and tenants injured by storms or severe weather may have legal rights beyond an insurance claim. We can help you understand your protections, preserve key records, and pursue a fair resolution while keeping your family, neighbors, and community in mind.
Your rights depend on the policy, the damage, and who may be legally responsible.
- We can review your policy’s coverage, deadlines, and Policy exclusions, then help you respond to a denial or underpayment with supporting documentation.
- You may have appraisal rights when you and your insurer disagree about the amount of covered loss. We can explain the process and its limits before you decide whether to use it.
- If another party’s conduct contributed to your injury or loss, you may have a separate legal claim. We can assess responsibility, applicable deadlines, and potential remedies.
Prompt action can protect your options. We’ll explain each step clearly so you can make informed decisions and focus on those who depend on you.
Why Do Storm & Weather Damage Injuries Happen in Fort Myers?
Storm and weather-related property injuries often happen because severe conditions expose structural weaknesses, create hazards, or leave damage unnoticed. In Fort Myers, strong winds, heavy rain, and flooding can turn ordinary properties into dangerous places for residents, visitors, and workers. Roofing vulnerabilities may let water inside, loosen shingles, or cause roof sections to fall. These conditions can lead to slips, falling debris, or exposure to electrical hazards.
Drainage failures can also leave standing water around entrances, walkways, and parking areas. When water collects, people may lose their footing or encounter hidden damage beneath the surface. Storms can also break windows, dislodge exterior materials, and weaken stairs, railings, or ceilings. If property owners or managers don’t identify and address these hazards, someone may be injured while entering, leaving, or using the premises. Understanding how severe weather creates unsafe conditions helps us recognize why careful property maintenance matters to everyone who depends on these spaces.
What Should You Do After a Fort Myers Property Claim Storm & Weather Damage Injury?
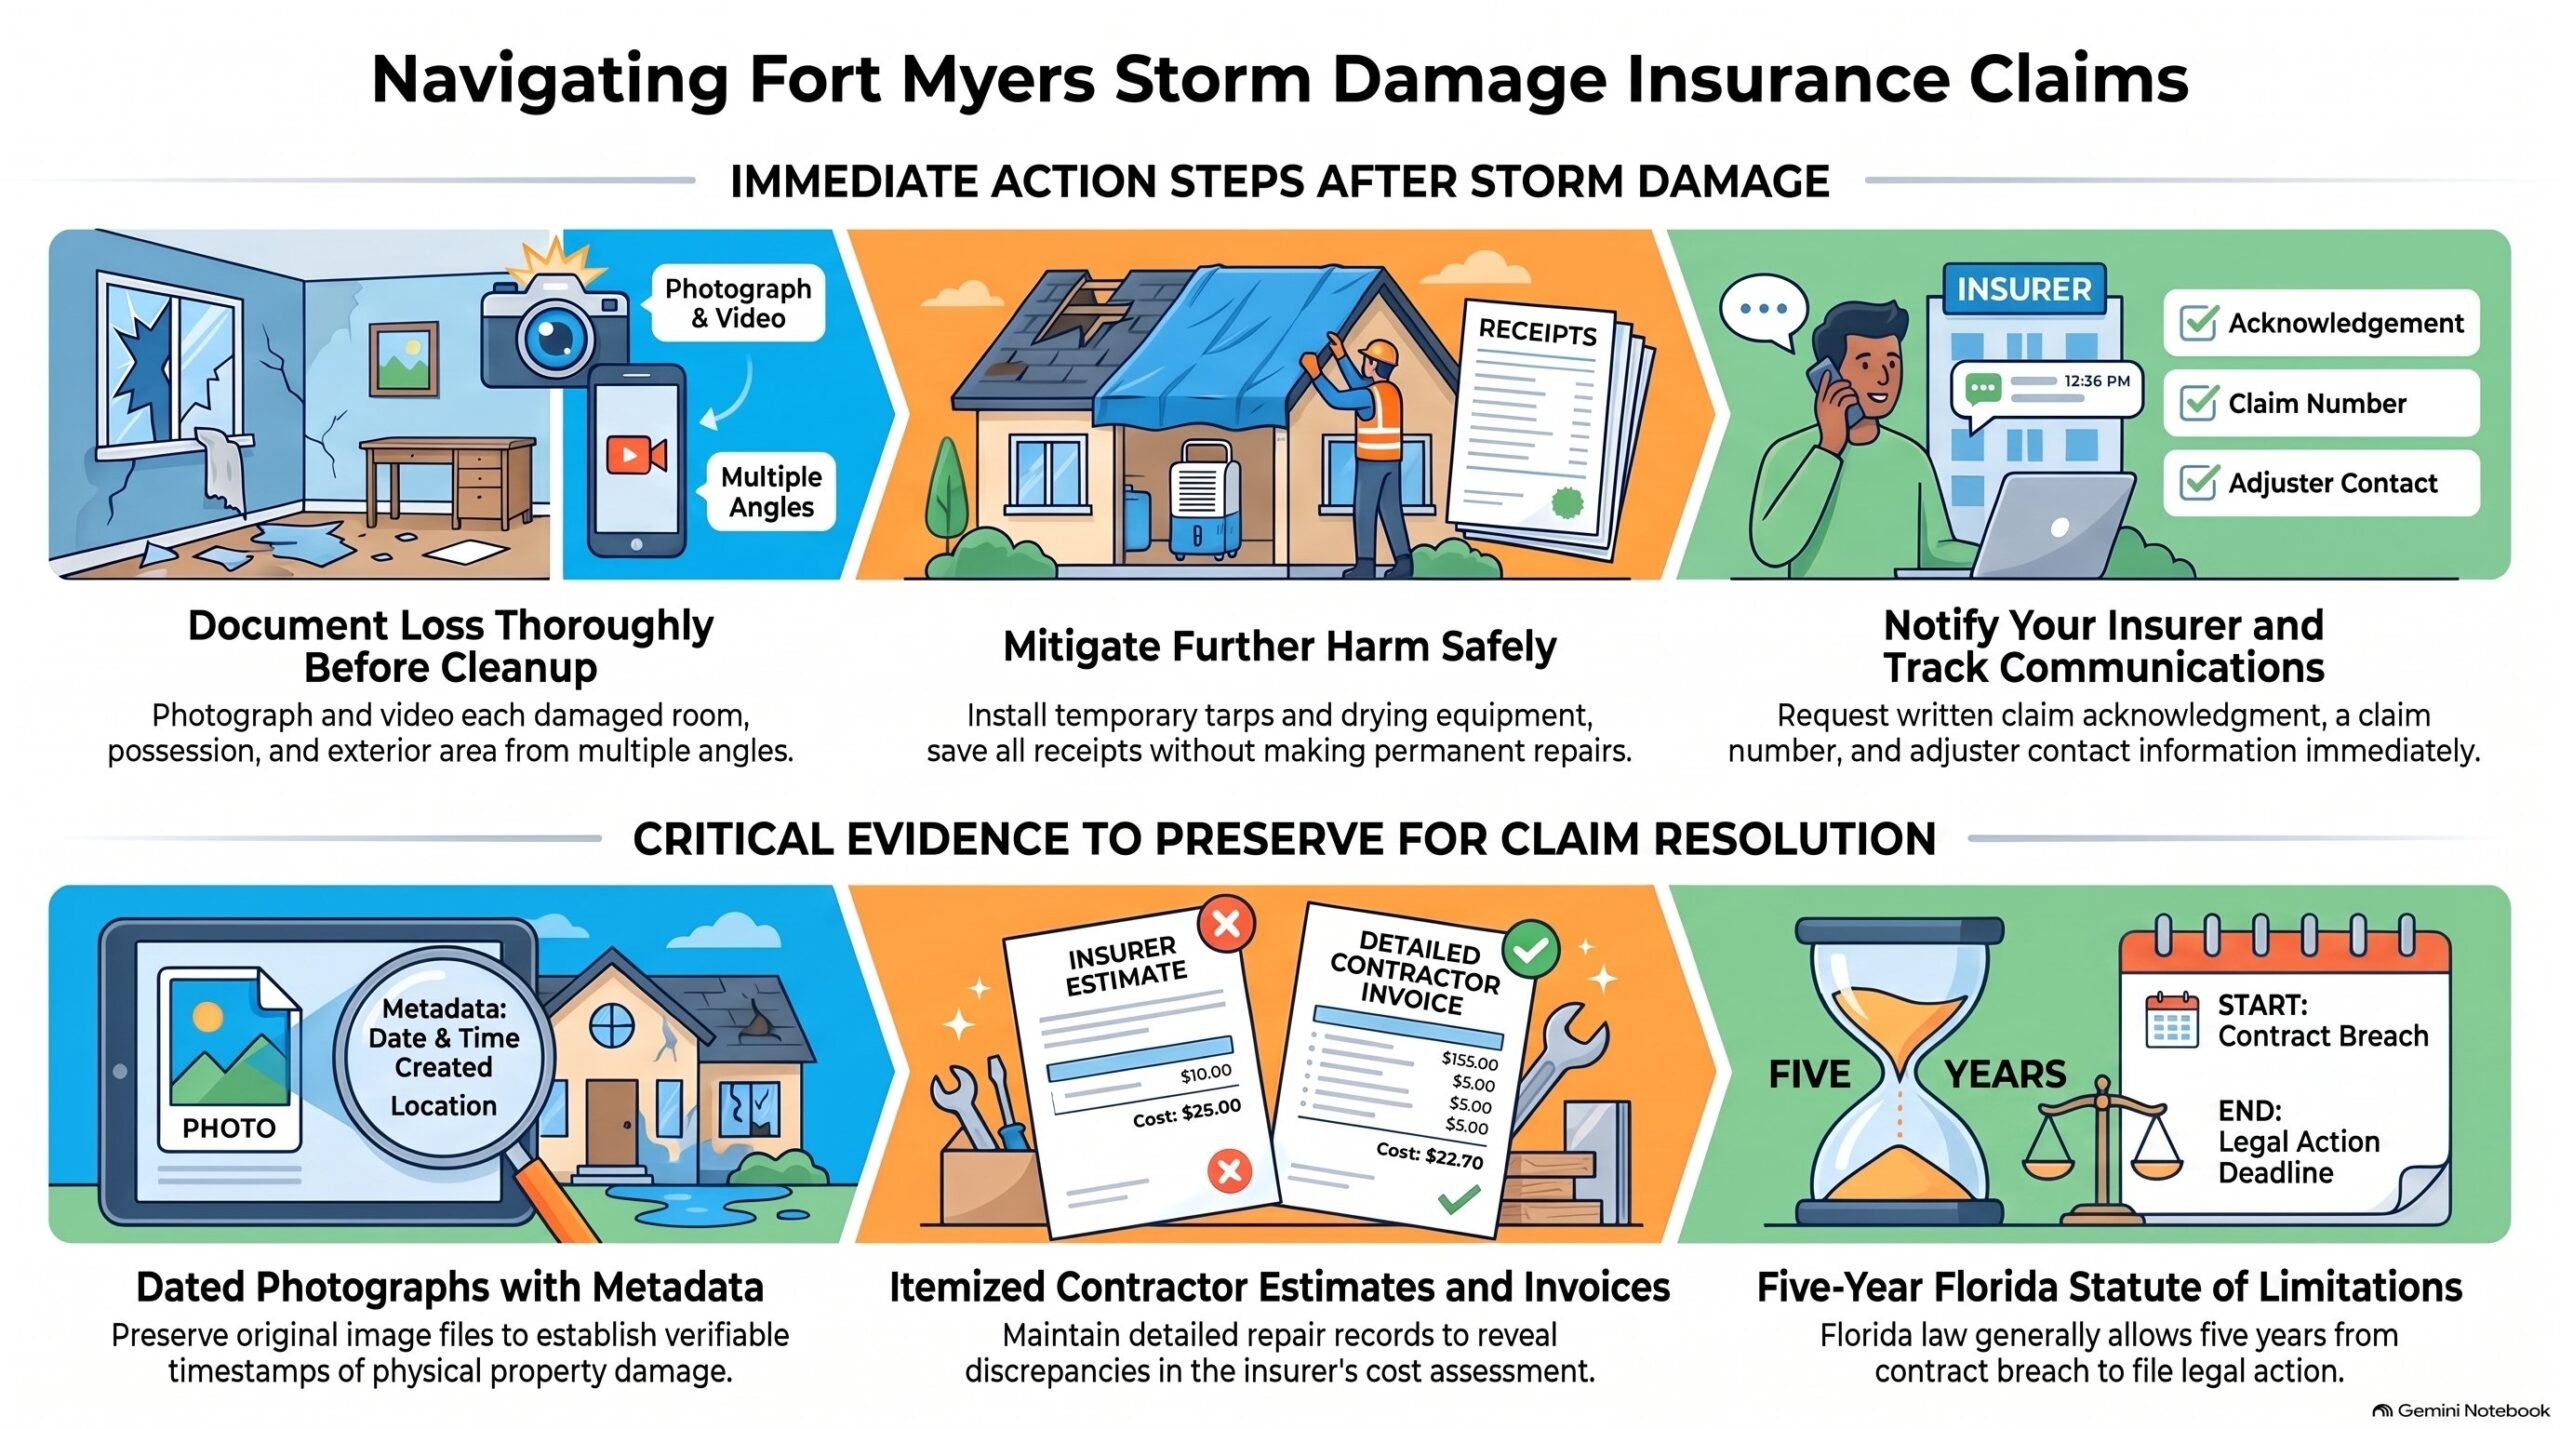
After storm or weather damage, we should document the affected areas with clear photographs and keep records of related expenses. We can limit further loss by taking reasonable steps to protect the property, while avoiding repairs that could compromise evidence. Then, promptly contact your insurer and provide an accurate account of the damage.
Document the Damage
How can you protect a property claim after severe weather? We can help you create a clear record before memories fade and you move damaged items. Photograph and video each affected room, exterior area, and possession from several angles. Include close-ups of broken materials and wider views that show the damage in context. Make a Damage inventory listing each item, its age, purchase date, estimated value, and condition. Gather receipts, warranties, repair records, and relevant before-storm photographs to support your account. Keep copies of every document and note when and how you sent information to your insurer. If you need Temporary housing, save lodging receipts and record related expenses. Organized evidence helps us present your loss accurately and supports a fair review of your claim. Keep descriptions factual and update your records as needed.
Prevent Further Loss
Once you’ve documented the damage, take reasonable steps to prevent it from getting worse. If it’s safe, move people and vital belongings away from unstable areas, standing water, or exposed wiring. Don’t enter a damaged structure if you suspect a collapse, gas leak, or electrical hazard; contact emergency services or qualified professionals instead.
Arrange Emergency tarping to cover roof openings and protect the interior from further rain. Use moisture-control measures, such as removing wet items and running appropriate drying equipment, to limit mold growth and further deterioration. Keep receipts and note the work performed, but don’t make permanent repairs before you can properly assess the damage. Choose licensed, insured contractors, and avoid anyone who pressures you into signing broad agreements. These precautions can protect your household and preserve your property while supporting a fair loss assessment.
Contact Your Insurer
Contact your insurer promptly to report the storm damage and ask what steps you must take to open a claim. We can help you prepare by gathering your policy information, photographs, repair estimates, and a clear account of what happened. Give accurate details, but avoid guessing about the cause or extent of damage that you haven’t confirmed. Ask the representative to explain deadlines, required forms, inspection procedures, and any temporary repairs you may make. Request written Claim acknowledgment, including your claim number and the adjuster’s contact information. Confirm coverage for the types of damage involved, but remember the insurer must review your policy and evidence before deciding. Keep copies of every message and note each call’s date, participants, and main points. Organized communication helps us protect your interests and resolve the claim fairly.
Don’t Wait. Call Our Florida Personal Injury Lawyers Now!
Critical Evidence in a Fort Myers Property Claim Storm & Weather Damage Injury Case
We can strengthen your storm damage claim by preserving evidence that links the weather event to your losses.
Start with these three categories:
- Dated photographs, weather reports, and alerts
- Repair estimates and invoices
- Witness statements and relevant records
Dated Damage Photographs
After a storm, dated photographs can help establish when damage occurred and how it changed over time. We can guide you in documenting affected areas promptly, before repairs or cleanup alter the evidence. Photograph roofs, ceilings, walls, flooring, damaged belongings, and any visible water intrusion from several angles. Include wider views to show each area’s location, then take close-ups that reveal specific damage. Preserve original files because Photo metadata may record when images were created and whether they were changed. Keep image backups in secure locations, and avoid editing or compressing the originals. A simple written log can identify each image’s date, location, and subject. If you’re helping protect your household or serving others after a storm, consistent records can clarify the property’s condition and support a careful review of your claim.
Weather Reports and Alerts
Weather reports and official alerts can help establish the conditions that affected your Fort Myers property and when they occurred. We can compare National Weather Service records, local forecasts, and Weather radar images with the timing and location of reported damage. These materials may show a storm’s path, rainfall, wind intensity, or flooding risk, helping us assess whether the event aligns with your account and the insurer’s position.
Save notices you received, including evacuation alerts, emergency management updates, and warnings from local authorities. Their timestamps can help document what officials knew and when they advised residents to act. If you shared responsibility for assisting family members, neighbors, or others, records may also clarify your movements and timing. We can preserve relevant reports and alerts promptly, since online sources may change or become harder to access.
Repair Estimates and Invoices
Repair estimates and invoices can show the scope and cost of storm damage to your Fort Myers property. We can use these records to explain what repairs the damage requires and whether the insurer’s assessment accounts for necessary work. A detailed estimate should identify affected areas, materials, labor, and projected costs. Estimate comparison can reveal significant differences between a contractor’s proposed repairs and the insurer’s calculation, helping us identify disputed items that need support.
After work begins, keep itemized invoices and proof of payment. Invoice verification lets us confirm that charges match completed repairs and that materials and labor relate to the covered damage. Accurate records help us present a clear, responsible claim and pursue funds needed to restore your property. We’ll review these documents carefully and explain any gaps or inconsistencies before you respond to the insurer.
Witness Statements and Records
When storm damage affects your Fort Myers property, witness statements and contemporaneous records can help establish what happened and when. We can help you identify people who saw the storm, noticed leaks, or observed conditions before and after the event. Ask each witness to describe only what they personally observed, including dates, times, and changes they noticed. Witness credibility depends on accurate, consistent details, not speculation or assumptions.
Prioritize statement preservation by recording accounts promptly and keeping original messages, photographs, and emails with their dates intact. We should also organize maintenance logs, inspection reports, and communications with contractors or insurers. These records may clarify whether damage followed the storm or developed over time. Avoid editing or embellishing evidence; preserve copies securely and share them with your claim representative or attorney. Careful documentation helps us present a clear account and support a fair resolution.
Long-Term Effects of Fort Myers Property Claim Storm & Weather Damage Injuries
Storm and weather-related injuries may cause chronic pain and limited mobility, affecting your ability to work and manage daily tasks. You may also face lasting respiratory problems, particularly after exposure to mold, dust, or contaminated water. We can help you understand how these effects, along with emotional and financial strain, may shape your property claim.
Chronic Pain and Mobility
After storm or weather damage in Fort Myers, injuries from falls, debris, or unsafe conditions can lead to chronic pain and lasting mobility problems. Chronic pain may persist after fractures, sprains, or back injuries, affecting sleep, concentration, and the ability to work or care for family. Mobility limitations can make walking, climbing stairs, or completing daily tasks difficult and may require therapy, assistive devices, or home adjustments. We can help you document these lasting effects through medical records, treatment plans, and clear accounts of how your injuries have changed your routine. Consistent care matters, both for your recovery and for showing the full impact of the harm. When you serve others, reduced independence can also disrupt responsibilities and community commitments. We’ll help you understand your options and pursue evidence-based compensation.
Lasting Respiratory Problems
Exposure to mold, dust, or other contaminants after storm damage can cause respiratory problems that persist long after the immediate danger has passed. Mold exposure may aggravate asthma, trigger persistent coughing, or reduce lung function, particularly for children, older adults, and people with existing conditions. We encourage you to seek medical evaluation when breathing symptoms continue or worsen, and to follow your provider’s treatment plan. Keep records of diagnoses, prescriptions, and recommended respiratory rehabilitation, as these details can help document how the damage has affected your health. If you’re supporting neighbors or family members after a storm, help them avoid contaminated areas and connect them with qualified care. We can also help you understand how medical evidence may support a property claim when storm-related conditions have caused lasting respiratory harm.
Emotional and Financial Strain
How long can storm damage affect daily life? Financial and emotional strain may persist long after the weather clears. Repair costs, temporary housing, lost income, and medical expenses can disrupt Household budgeting and limit resources for family needs. When you’re also managing lingering injuries or respiratory problems, these pressures may make it harder to work, care for others, and maintain stability.
We can help you document how storm-related harm affects your household over time. Keep records of expenses, missed work, treatment, and changes to daily responsibilities. These details can clarify the full impact of a property claim and support informed decisions about next steps. Emotional resilience matters, but you shouldn’t carry every burden alone. By seeking reliable guidance and support, we can protect your interests while you focus on recovery and serving those who depend on you.
Proving Liability in Fort Myers Property Claim Storm & Weather Damage Injury Cases
Storm damage alone doesn’t establish liability for an injury on someone else’s property in Fort Myers. We must show that the responsible party failed to take reasonable steps to protect visitors from a foreseeable hazard. Duty standards depend on the relationship between the injured person and the property owner, as well as the circumstances surrounding the danger.
Evidence can help establish what happened and whether the owner knew or should have known about the risk. We may review inspection records, maintenance history, photographs, weather reports, witness accounts, and repair timelines. For example, a loose roof panel, fallen branch, or flooded walkway may create a hazard if the owner knew about it or reasonably should have discovered it and failed to respond.
A careful causation analysis connects that failure to your injury. We’ll also consider whether the hazard was visible, whether warnings or barriers were provided, and whether other factors contributed. Clear documentation supports a fair assessment of responsibility and helps protect everyone affected.
Dealing With Insurance Companies After a Fort Myers Property Claim Storm & Weather Damage Injury
After a storm-related injury on someone else’s property, insurers may contact you to discuss the incident or request a statement. We can help you respond carefully, protect your interests, and keep you focused on recovery and your responsibilities to others.
Insurer communications may include questions about how you fell, what you observed, and whether you had prior symptoms. Answer truthfully, but don’t guess or minimize your injuries. Before giving a recorded statement or signing a release, consider speaking with a lawyer. A statement made before you understand the full effects of an injury could be used to challenge your account or limit compensation.
We can review correspondence, explain the proposed terms, and negotiate the claim with the insurer. This support can help you avoid pressure to accept an offer that doesn’t reflect your losses, including medical expenses, lost income, and continuing care. Keep copies of messages and documents, and direct requests for information to your legal representative when appropriate. Clear, measured communication can protect your claim while you serve your family and community.
What to Expect During a Fort Myers Property Claim Storm & Weather Damage Injury Claim Process
We’ll start by promptly reporting the storm damage and documenting your losses with photographs, receipts, and repair estimates. Next, we’ll review the insurer’s decision and the evidence supporting your claim. If the insurer disputes or undervalues your losses, we’ll explain the available options for resolving the dispute.
Reporting the Damage
Prompt notice can help protect your property claim and preserve important evidence. We recommend contacting your insurer as soon as it’s safe after a storm or other weather event. Use the policy’s listed reporting method, such as its claims line or online portal, and provide the date, location, and a concise description of the damage. If you’re unsure whether the loss is covered, report it anyway and ask what information the insurer needs next. Keep the conversation focused on facts, and avoid guessing about the cause or extent of damage. Request a claim number and written acknowledgment, then note the adjuster’s name and contact information. We can help you understand deadlines, communicate clearly, and pursue a fair response while you focus on your household and community.
Documenting Your Losses
After you report the damage, document each loss as soon as it’s safe to do so. Photograph affected rooms, damaged belongings, and visible structural problems before you begin cleanup. Take wide shots for context and close-ups that show specific damage. We can help you create an Inventory checklist that lists each item, its approximate age, purchase price, and current condition. Gather receipts, warranties, repair estimates, and other records that support your account. Keep copies of every document in a secure location, and note dates, expenses, and conversations related to the damage. If your home isn’t safe to occupy, document why and keep receipts for temporary housing, meals, and necessary purchases. Clear documentation helps us present your losses accurately and preserve important details while you focus on protecting your family and helping others in your community.
Reviewing the Claim
After you submit your claim, the insurer will review the information, inspect the damage, and decide what the policy may cover. We can help you understand each step and respond promptly to requests for records, photographs, repair estimates, or access to the property. The adjuster may compare observed damage with your documentation and assess whether the storm caused the reported loss. Careful policy interpretation matters because coverage depends on the policy’s terms, exclusions, limits, and facts surrounding the damage. We’ll explain what the insurer’s findings mean and identify information that may affect its evaluation. If the insurer uses the appraisal process to assess the damage amount, we can explain how it works. Staying organized and informed helps you protect your household and plan responsibly while the claim remains under review.
Resolving Disputes
If the insurer disputes your Fort Myers storm damage claim, we can help you understand its position and evaluate your options. We’ll review the policy, inspection findings, repair estimates, and correspondence to identify the disagreement and explain what evidence may address it. You can provide photographs, contractor reports, receipts, and other records showing the damage and its effect on your property.
Depending on your policy and the dispute, Mediation options may help both sides pursue a practical resolution with a neutral facilitator. Appraisal procedures may apply when the disagreement concerns the amount of loss, but they generally don’t resolve every coverage issue. We’ll explain the process, deadlines, and potential costs before you decide how to proceed. By handling the dispute carefully, we can protect your interests while helping you restore a safe home and serve your family and community.
Compensation for Fort Myers Property Claim Storm & Weather Damage Injury Damages
Storm and weather damage can cause substantial property losses, but compensation depends on your policy’s terms, the cause of the damage, and the evidence supporting your claim. We can help you identify covered losses and present a clear, well-supported claim so you can focus on restoring your home and supporting those who rely on you.
Compensation may address necessary repairs or replacement of damaged structures, subject to applicable policy conditions and exclusions. Coverage limits set the maximum available for particular losses, while deductibles and depreciation provisions may affect payment. We’ll review the policy, document damage with photographs, estimates, invoices, and inspection findings, and compare the insurer’s assessment with the actual repair needs.
If the parties disagree on the amount of covered damage, appraisal clauses may provide a process to resolve that valuation dispute. We can explain the clause’s requirements and help you evaluate whether appraisal is appropriate. Prompt reporting and careful records can strengthen your position and help prevent avoidable delays in reaching a fair resolution.
Economic vs. Non-Economic Damages in Fort Myers Property Claim Storm & Weather Damage Cases
We’ll first examine economic damages, such as repair costs, temporary housing, and lost income tied to storm damage. We’ll then consider non-economic losses, including disruption to your daily life and the stress of displacement. Comparing these categories can help us assess what your claim may include and how the evidence supports each loss.
Economic Damage Examples
After severe weather damages a home or business, economic losses can include repair costs, temporary housing, debris removal, and damaged personal property. We can help you identify and document these measurable expenses so your claim reflects the resources needed to restore the property and support those who depend on it. Keep invoices, receipts, estimates, photographs, and payment records, since clear documentation can help connect each cost to the storm damage.
If damage forces you to close a business, Business interruption losses may include lost income and necessary operating expenses during repairs. A household may also incur temporary relocation costs, such as lodging, storage, and added transportation. We can review policy terms, deadlines, and available records with you, then explain which claimed costs may be covered. Careful preparation helps present a complete, supportable request to the insurer.
Non-Economic Losses
Although property insurance claims generally focus on measurable financial losses, severe weather can also disrupt daily routines and create stress for homeowners and business owners. When a storm damages a home or workplace, the effects may reach beyond repair bills and lost income. You might experience Emotional distress from displacement, uncertainty, or the burden of managing repairs while caring for family, employees, or customers. Damage can also limit your enjoyment, keeping you from using familiar rooms, welcoming others, or carrying out ordinary activities. These personal effects matter, even when they’re harder to measure than physical damage. We can help you understand what your policy covers and document how the disruption has affected your household or business. Clear records and timely communication can support a complete claim while helping us advocate for the people who depend on you.
Comparing Damage Claims
When a storm damages your Fort Myers property, we separate economic losses from non-economic effects to show the full scope of the harm. Economic damages include documented repair costs, temporary housing, damaged belongings, and lost income when the property supports your work or business. We organize estimates, invoices, photographs, and other records to connect each expense to the storm and support your claim.
Non-economic effects may include disruption, stress, and loss of the property’s use or comfort. These impacts can be harder to measure, but we explain how they affected your daily life and responsibilities. A careful Claim comparison considers both categories, the available evidence, policy terms, and the insurer’s assessment. Settlement benchmarks provide context, but no prior result guarantees a specific recovery. We evaluate the full record so you can pursue a fair resolution.
Don’t Wait. Call Our Florida Personal Injury Lawyers Now!
When a Fort Myers Property Claim Storm & Weather Damage Injury Case Goes to Trial vs Settlement
A Fort Myers storm damage claim may settle through negotiations or proceed to trial if the parties can’t agree on the insurer’s responsibility or the value of the loss. We can help you assess both paths and choose an approach that supports a fair resolution while protecting your ability to rebuild and serve your family or community.
During settlement negotiations, we present evidence of the damage, repair costs, and the insurer’s handling of your claim. A negotiated agreement may resolve the dispute sooner and avoid the uncertainty, expense, and time involved in court. We’ll explain any proposed terms so you can make an informed decision.
If negotiations don’t produce an acceptable result, we may take the case to trial. Trial preparation can include organizing photographs, estimates, inspection records, and witness testimony to support your position. A judge or jury then evaluates the evidence and decides disputed issues. We’ll prepare you for each stage and discuss the risks and potential outcomes before proceeding.
Florida Laws That May Affect Your Fort Myers Property Claim Storm & Weather Damage Case
Florida law sets deadlines and standards that can shape how we handle your Fort Myers storm damage claim. These rules may affect notice, documentation, coverage disputes, and the steps available when an insurer questions the loss. We’ll review the policy and applicable requirements with care, so you can focus on protecting your home and supporting those who depend on you.
Florida law shapes storm damage claims, from notice deadlines and documentation to coverage disputes and available next steps.
- Florida law requires insurers to follow claim-handling standards, including timely communication and fair investigation. We can organize photographs, repair estimates, receipts, and other records to help present a clear account of the damage.
- Policy exclusions may limit coverage for certain causes or property conditions. We’ll compare the insurer’s explanation with the policy language and the available evidence, rather than assume a denial is final.
- Appraisal clauses may offer a process for resolving disagreements about the amount of a covered loss. We can explain how the clause works and assess whether it fits your circumstances.
Understanding these rules helps us pursue a careful, informed claim.
The Statute of Limitations for Fort Myers Property Claim Storm & Weather Damage Injury Cases
Because filing deadlines can affect your right to pursue compensation, we’ll identify the limitation period that applies to your Fort Myers storm or weather damage claim. Florida law generally gives policyholders five years to bring a breach-of-contract lawsuit based on a property insurance policy. The period usually begins when the insurer breaches the contract, not necessarily when the storm occurs. However, deadlines depend on the claim’s facts and the relief you seek, so we shouldn’t assume one date applies to every case.
Filing deadlines also differ from notice requirements and other time limits in an insurance policy. Policy limitations may require prompt notice, proof of loss, or compliance with specific claim procedures. Missing a contractual requirement can create problems even when the lawsuit deadline has not expired. We should carefully review the policy, claim correspondence, and relevant dates to determine which requirements apply. Acting promptly helps protect your ability to seek payment and preserve resources that support your household and community. When uncertainty exists, we should confirm the applicable deadline rather than risk delay.
How a Fort Myers Property Claim Storm & Weather Damage Lawyer Can Help You
After we identify the deadlines that apply to your claim, a Fort Myers property claim lawyer can help you address how your insurer’s handling your storm or weather damage. We can explain your policy, evaluate the evidence, and help you pursue a fair decision while protecting the resources your household or organization needs to serve others.
- Review the policy. Through careful Policy interpretation, we identify relevant terms, exclusions, notice requirements, and duties that may affect your claim.
- Assess the loss. Our coverage analysis compares the policy with photographs, repair estimates, inspection findings, and other records to clarify what damage may qualify for coverage.
- Address the insurer’s response. We can organize supporting documents, communicate with the insurer, challenge unsupported conclusions, and explain your options if the insurer delays, underpays, or denies the claim.
We also help you understand the reasoning behind each step. With a clear record and informed guidance, you can make decisions that support recovery and preserve your ability to care for those who depend on you.
When to Contact a Fort Myers Property Claim Storm & Weather Damage Lawyer
Contact a Fort Myers property claim storm and weather damage lawyer when the insurer delays, offers less than the documented cost of repairs, or denies coverage you believe your policy provides. Early guidance can help you understand your options while you focus on protecting your household and restoring your property.
Consider an attorney consultation if the insurer requests repeated information, disputes the cause or extent of damage, or pressures you to accept a settlement before you understand its terms. Keep copies of your policy, claim correspondence, photographs, repair estimates, and receipts so we can review the relevant facts with you.
Act promptly because Policy deadlines may apply to reporting damage, submitting documents, or filing a legal action. These time limits can vary by policy and circumstances, so don’t assume that ongoing discussions with the insurer extend them. If you’re unsure whether a response is fair or a deadline is approaching, ask for legal guidance before taking further steps. Timely advice helps you make informed decisions and preserve your ability to pursue the claim.
Why You Need an Experienced Fort Myers Property Claim Storm & Weather Damage Lawyer
An experienced Fort Myers property claim storm and weather damage lawyer can help you assess the insurer’s decisions, document the full scope of your losses, and respond to disputes over coverage or repair costs. We can explain how policy language applies to your circumstances and identify provisions that may affect your claim. Careful Policy interpretation and coverage analysis can clarify whether the insurer has considered covered damage, exclusions, deductibles, and applicable limits.
We can also organize photographs, repair estimates, inspection findings, and other records to support a clear account of what happened. When an insurer undervalues damage or delays a decision, we can communicate concerns, challenge unsupported conclusions, and pursue a fair review under the policy. This guidance can help you make informed choices while protecting your household’s financial stability. By addressing the claim methodically, we can reduce confusion and keep attention on documented facts, your contractual rights, and the resources needed to restore your property and move forward with confidence.
How to Choose the Right Fort Myers Property Claim Storm & Weather Damage Lawyer for Your Case
Choosing the right Fort Myers property claim storm and weather damage lawyer starts with evaluating the attorney’s experience handling insurance disputes like yours. Ask whether the lawyer has managed claims involving similar damage, policy language, and insurer responses. Relevant experience can help us assess disputed estimates, document losses, and identify missed deadlines before they affect your claim.
Review Attorney credentials, including Florida licensure, disciplinary history, and professional standing. We should also ask who will handle our case, how the firm communicates, and how often we can expect updates. Clear answers help us make an informed choice and stay involved throughout the process.
Discuss fee structures before signing an agreement. Ask how fees and case expenses are calculated, when payment is due, and whether we owe costs if the claim does not succeed. We should understand every term in writing. Finally, compare consultations and choose counsel who listens carefully, explains options plainly, and treats our household’s recovery with respect.
About The Law Offices of Anidjar & Levine
After reviewing how to select counsel, we can consider what the Law Offices of Anidjar & Levine offers property owners facing storm and weather damage disputes.
We work to help you understand your options, communicate with insurers, and pursue a claim supported by the available evidence.
We review policy terms, document damage, and explain the steps that may follow if an insurer disputes or delays payment.
Firm history reflects a practice serving people who need guidance during difficult legal and personal circumstances.
We bring that service-minded approach to property claims, where clear information and careful preparation can help you make informed decisions.
Our attorney values include responsiveness, diligence, and respect for each client’s concerns.
We listen to your account, assess the facts, and explain potential paths without promising a particular result.
When you contact us, we can discuss your situation and identify practical next steps.
You deserve counsel that takes your property loss seriously and keeps you informed throughout the process.
Frequently Asked Questions
Does Homeowners Insurance Cover Temporary Lodging After Storm Damage in Fort Myers?
Yes, homeowners insurance may cover temporary lodging after storm damage in Fort Myers if covered damage makes your home uninhabitable. We can help you review your policy’s Loss of Use coverage, which commonly includes Additional Living Expenses for reasonable costs above your normal household spending, such as hotel stays and meals. Coverage limits, waiting periods, and exclusions vary. Keep receipts, document the damage, and contact your insurer promptly to confirm eligibility and required approval before booking.
Can I File a Property Claim if My Roof Leaked Before the Storm?
Yes, we can help you assess whether you may file a property claim, even if your roof leaked before the storm. Coverage often depends on whether storm-related damage caused new damage or worsened the existing condition, and on your policy’s terms. Insurers may exclude preexisting roof leaks, but they must evaluate covered storm damage separately. We recommend documenting the roof’s condition, reporting the loss promptly, and preserving repair records for a fair review.
Should I Hire a Public Adjuster for My Fort Myers Storm Damage Claim?
You may benefit from hiring a public adjuster if your Fort Myers storm damage claim is complicated, disputed, or undervalued. We recommend comparing qualified professionals and reviewing Public adjuster fees, services, and contract terms before you commit. A public adjuster can help organize claim documentation, assess covered damage, and communicate with your insurer, but can’t guarantee payment. We’d also encourage you to preserve records and consider legal advice if coverage remains contested.
What if My Insurer Says Storm Damage Resulted From Poor Maintenance?
If your insurer attributes storm damage to poor maintenance, ask us to review its explanation and the policy language before accepting a denial or reduced payment. Policy exclusions may apply, but the insurer should support its position with relevant facts. We can help you preserve photographs, repair records, inspection reports, and other causation evidence, then respond clearly to the insurer. A careful review can protect your claim and help you make informed decisions.
Can I Reopen a Fort Myers Property Claim After Receiving Payment?
Yes, we may be able to pursue additional compensation after you receive payment, depending on your policy, claim status, and applicable deadlines. If repairs uncover damage the insurer didn’t include, we can document it and request supplemental payments. Some insurers allow reopened claims, but payment may have included a release or settlement terms that limit further recovery. We should promptly review your policy, settlement documents, and evidence, then advise you on the right next steps.
—————————
Storm and weather damage can leave you facing costly repairs, disputed coverage, and uncertainty about what to do next.
We can review your policy, assess the insurer’s decision, and explain the options available under Florida law.
Prompt action can help preserve evidence and protect your claim.
At The Law Offices of Anidjar and Levine, we hold insurers accountable and pursue the benefits you’re entitled to
Contact us to discuss your Fort Myers property damage claim.
Learn more about a Fort Myers Personal Injury Lawyer.