West Palm Beach property claim disputes and process-injury cases require careful review of policy language, claim communications, inspections, and resulting losses.
The Law Offices of Anidjar and Levine can evaluate coverage, identify responsible parties, challenge unsupported denials, and preserve evidence such as photographs, estimates, medical records, and repair invoices.
Counsel may also address delayed payments, inadequate investigations, valuation disagreements, and injuries connected to claim handling or unsafe conditions.
For guidance regarding injury-related claims, consult a West Palm Beach Personal Injury Lawyer.
Main Takeaways
- A West Palm Beach property claim lawyer evaluates coverage, damage evidence, responsible parties, and potential financial recovery.
- Legal guidance can address storm damage, water intrusion, mold, structural conditions, valuation disputes, exclusions, and delayed payments.
- Preserve photographs, inspection reports, communications, estimates, invoices, weather records, and witness information immediately.
- Counsel can challenge unsupported denials by reviewing policy language, claim handling, statutory duties, and available proof.
- Prompt medical care and complete treatment records are important when claim-handling conditions cause related injuries.
How We Can Help With Your West Palm Beach Property Claim Disputes & Process Injury Claim
When a property claim dispute or process-related injury claim arises in West Palm Beach, experienced legal guidance can help protect the claimant’s rights and financial interests. Counsel can review available information, identify responsible parties, and develop an organized plan to pursue appropriate relief. Early Evidence preservation may include securing photographs, inspection materials, communications, repair records, and witness information before conditions change or relevant records become unavailable.
Legal professionals can also explain documentation requirements, coordinate supporting records, and prepare submissions that clearly present losses. During insurance negotiation, counsel may assess coverage positions, challenge unsupported denials, and communicate with adjusters while protecting the claimant from avoidable concessions. A carefully developed settlement strategy considers medical expenses, property damage, lost income, future needs, and the strength of available evidence. Throughout the process, representation can reduce administrative burdens and help individuals or families focus on recovery and service to others. When settlement efforts do not resolve the matter, counsel can advise regarding further lawful options.
Understanding West Palm Beach Property Claim Disputes & Process Injury Cases


Understanding a West Palm Beach property claim dispute or process-related injury case begins with identifying the event, the parties involved, and the legal duties that may apply. A careful evaluation distinguishes property damage issues from injuries allegedly connected to claim handling, inspections, communications, or other administrative conduct. The analysis may involve the policy, applicable Florida statutes, contractual obligations, and evidence showing how the matter progressed.
OUR CONSULTATIONSARE FREE
START YOUR FREE CASE REVIEW
Coverage document review can clarify insured interests, exclusions, conditions, deadlines, and procedures governing notice and payment. Records such as photographs, estimates, correspondence, medical documentation, and claim notes may help establish the relevant timeline and support a fair assessment. When an insurer rejects or limits benefits, denied-claim appeals may require a focused response that addresses the policy language and available proof. Individuals assisting affected property owners should preserve records, communicate accurately, and avoid assumptions before legal duties are determined. A qualified attorney can evaluate potential remedies, explain procedural requirements, and help protect the interests of those seeking responsible resolution.
Don’t Wait. Call Our Florida Personal Injury Lawyers Now!
Common Causes of West Palm Beach Property Claim Disputes & Process
Common property claim disputes often arise from storm damage, particularly when insurers and policyholders disagree about the cause or extent of covered losses. Conflicts may also involve policy interpretation, claim valuation, and the proper assessment of repair or replacement costs. Delayed payment practices can further complicate the process, creating disputes over compliance with policy obligations and applicable law.
Storm Damage Disputes


Storm damage disputes arise when an insurer and property owner disagree about the cause, scope, or value of damage following a hurricane, tropical storm, wind event, or severe rainfall. Disagreements may involve whether wind, water intrusion, fallen trees, or resulting moisture caused particular conditions. Insurers may question the timing of reported damage, while owners may contend that inspections overlooked hidden structural problems. Documentation can substantially affect the claim process. Photographs, contractor observations, weather records, maintenance histories, and prompt Mitigation Efforts may help establish what occurred and how conditions progressed. Repair Estimates can also differ substantially because contractors may identify necessary work that an insurer’s assessment omits. A careful, impartial evaluation helps clarify disputed facts, preserve evidence, and support a fair resolution for the affected property owner.
Coverage Interpretation Conflicts
Coverage interpretation conflicts arise when an insurer and property owner assign different meanings to policy terms, exclusions, conditions, or limitations. Policy wording may contain technical language that affects whether a reported loss falls within coverage, particularly when provisions address concurrent causes, maintenance obligations, or duties after a loss. Insurers may rely on exclusions or narrow definitions, while policyholders may contend that coverage grants, endorsements, or reasonable expectations apply. Evidence disputes can intensify these disagreements when documents, photographs, inspection findings, or communications support competing interpretations of the policy’s requirements.
Carefully reviewing the complete policy, applicable endorsements, claim correspondence, and relevant facts can clarify the dispute. Legal guidance may help identify ambiguous provisions, assess interpretive arguments, and pursue a fair resolution while protecting the policyholder’s rights.
Claim Valuation Challenges
Even when policy language supports coverage, disputes may continue over the amount an insurer must pay. Valuation challenges often arise when the parties disagree about repair estimates, depreciation, replacement costs, or the extent of covered damage. An insurer may rely on internal pricing data, while a policyholder may present contractor estimates reflecting local labor and material expenses. Differences in measurements, construction standards, and damage scope can produce substantially different calculations. Insurance documentation issues, including incomplete photographs, missing receipts, or inconsistent inventories, may further complicate an accurate assessment. Carefully reviewing policy limits, endorsements, estimates, and supporting records helps clarify the applicable valuation method.
Qualified assistance can help organize evidence, identify unsupported reductions, and promote a fair resolution while limiting claim settlement delays caused by unresolved factual disputes.
Delayed Payment Practices
Delayed payment practices can intensify West Palm Beach property claim disputes when an insurer fails to issue benefits within a reasonable period after receiving the required documentation. Delays may arise from incomplete investigations, repeated requests for records, disputed coverage, or internal processing backlogs. When payments are withheld, property owners may struggle to fund emergency mitigation, secure contractors, and maintain safe living conditions. Extended delays can also disrupt repair timelines, increasing the risk of further damage and higher restoration costs. A complete proof of loss, photographs, estimates, receipts, and timely correspondence can help establish the claim’s basis and preserve a clear record. Individuals serving affected property owners may review policy deadlines, identify unexplained inaction, and communicate professionally with the insurer.
Legal guidance may be appropriate when delay appears unreasonable, prejudicial, or inconsistent with applicable Florida requirements.
Legal Rights of West Palm Beach Property Claim Disputes & Process Injury Victims
When a property claim dispute results in injury, affected individuals may have legal rights separate from the underlying insurance disagreement. Affected parties may pursue compensation for medical expenses, lost income, pain, and other legally recognized losses. They may also have rights involving fair treatment, timely claim handling, and access to relevant policy information.
A qualified attorney can evaluate liability, applicable deadlines, coverage provisions, and potential remedies while protecting the claimant’s interests.
Service-oriented representation should emphasize:
- Prompt medical attention and complete treatment records
- Evidence preservation steps, including photographs, notices, and witness information
- Accurate documentation of expenses, communications, and missed work
- Client communication tactics that provide respectful, timely, understandable updates
Injured individuals may decline unfavorable settlements until the claim’s full value is assessed. They can request reasonable accommodations during the process and may seek litigation when negotiations fail. Because legal rights depend on facts, policy language, and Florida law, prompt consultation with counsel can help preserve evidence, clarify options, and support an informed decision.
Why Do West Palm Beach Property Claim Disputes & Process Injuries Happen?
Property claim disputes and related injuries often arise from unclear policy terms, inadequate documentation, disputed causes of damage, or delays in investigating and resolving a claim. In West Palm Beach, severe storms, wind, flooding, and aging construction can complicate efforts to determine whether a loss is covered. Insurers and policyholders may disagree about excluded perils, depreciation, repair standards, or the scope of necessary work. Underinsured coverage can create additional conflict when available limits do not reasonably address rebuilding expenses, personal property losses, or code-compliance costs. Roof replacement disputes often arise when insurers attribute damage to wear and tear rather than a covered storm event, or when estimates differ on repairability.
Process-related injuries may occur when claim handling causes unsafe living conditions, prolonged displacement, financial strain, or delayed repairs. These disputes often reflect conflicting evidence, inconsistent evaluations, communication failures, and competing interpretations of contractual duties rather than a single mistake by either party involved.
What Should You Do After a West Palm Beach Property Claim Dispute & Process Injury?
After a property claim dispute or related injury, the claimant should promptly document all damage with photographs, records, and written descriptions. The claimant should notify the insurer without unnecessary delay and carefully preserve communications and claim documents. Consultation with a qualified claims lawyer can help protect the claimant’s rights and address potential disputes.
Document Property Damage
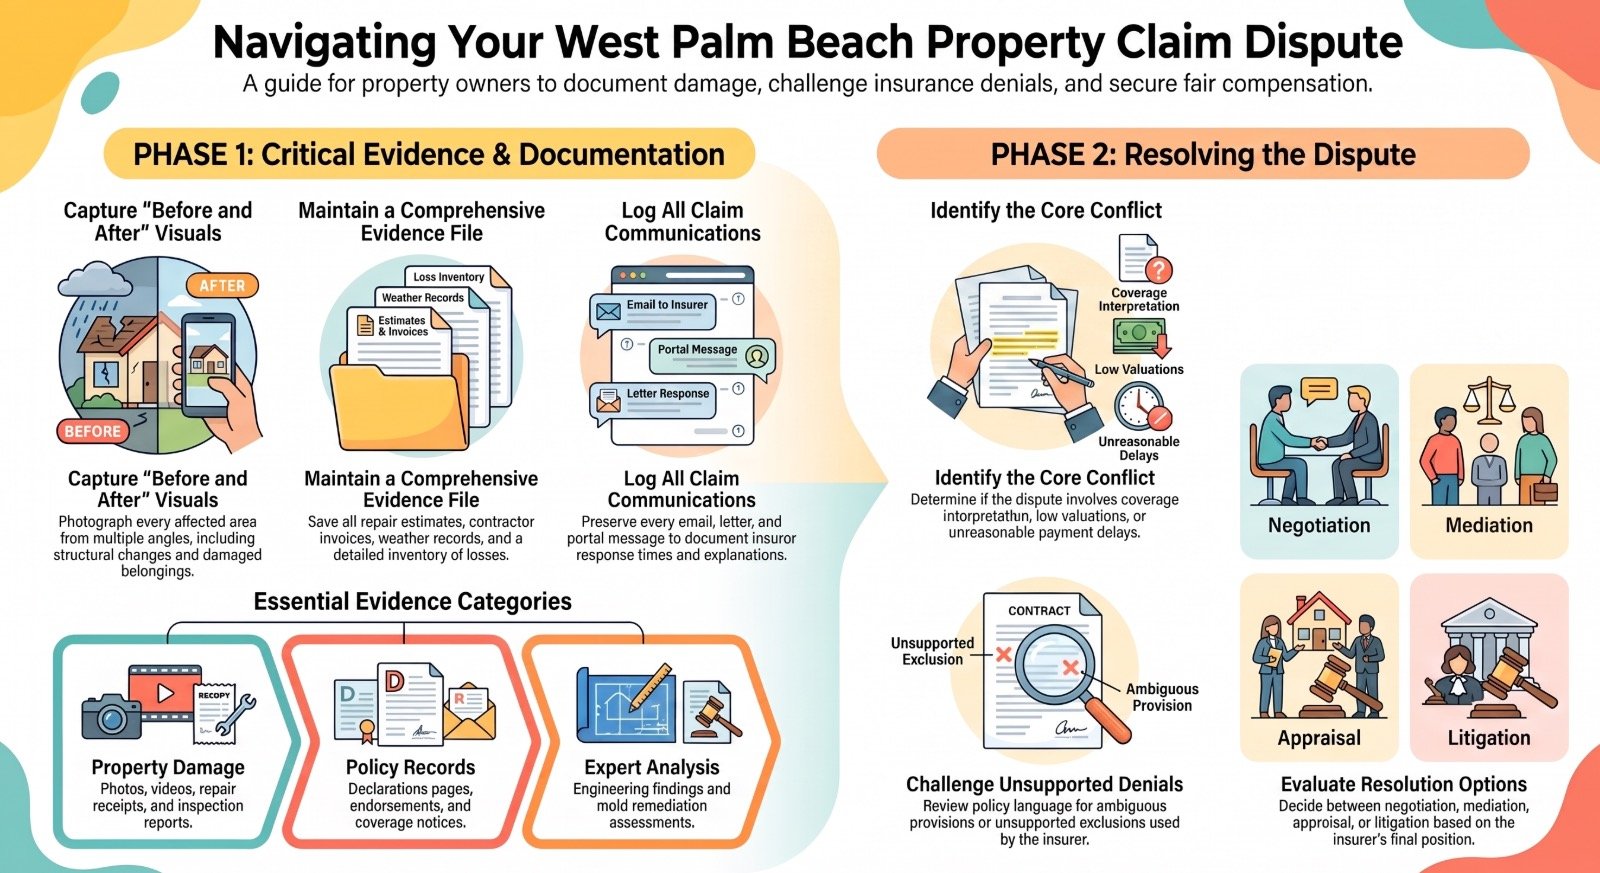
Clear, thorough documentation is necessary to protect a homeowner’s position in a West Palm Beach property claim dispute. After damage occurs, the homeowner should photograph and record every affected area, including structural changes, damaged belongings, standing water, and visible debris. Claim photos should show both close details and wider views that establish the damage’s location and extent. Written notes should note when you discovered the conditions and describe any ongoing water intrusion, unusual odors, or safety concerns. Preserve receipts, repair estimates, contractor findings, and invoices as insurance documentation. If Mold remediation becomes necessary, records should include inspection results, treatment recommendations, completed work, and related expenses. Keeping these materials in an organized, secure file can help clarify the property’s condition, support accurate evaluation, and preserve information needed to serve the homeowner’s interests.
Notify Your Insurer
Prompt notification is an important first step in protecting a homeowner’s rights during a West Palm Beach property claim dispute. The policyholder should contact the insurer promptly after discovering covered damage, even when the full extent of the loss remains uncertain. A timely Coverage Notice should identify the property, describe the event, and state when the damage was discovered. Communicate through the insurer’s designated channels, and keep confirmation of the submission for future reference. The homeowner should also request claim instructions, deadlines, inspection procedures, and information about temporary repairs. A Documentation Checklist can help organize photographs, videos, receipts, repair estimates, correspondence, and policy records. Accurate, consistent reporting allows adjusters to evaluate the claim efficiently while preserving a clear record of the homeowner’s cooperation and losses.
Consult a Claims Lawyer
When a West Palm Beach property claim becomes disputed, delayed, underpaid, or procedurally complicated, the policyholder should consult a qualified claims lawyer before making statements or accepting a settlement. Counsel can examine the policy, damage evidence, correspondence, and deadlines to identify coverage issues and protect the policyholder’s interests. A claim timeline review may reveal missed obligations, unreasonable delays, inconsistent explanations, or improper claim handling. The lawyer can also explain available remedies, organize supporting documentation, and communicate with the insurer on the policyholder’s behalf. For denied coverage appeals, legal guidance may clarify whether the insurer relied on an unsupported exclusion, conducted an incomplete investigation, or misinterpreted policy language.
Prompt consultation helps preserve evidence and promotes a fair resolution while enabling the policyholder to serve family, tenants, customers, or the broader community responsibly.
Don’t Wait. Call Our Florida Personal Injury Lawyers Now!
Critical Evidence in a West Palm Beach Property Claim Disputes & Process Injury Case
Critical evidence can establish the extent of loss, support policy coverage, and clarify whether an insurer handled the claim properly.
A West Palm Beach property claim disputes lawyer may organize the following materials to strengthen the case:
- Property damage documentation, including photographs, repair estimates, and receipts
- Insurance policy records, endorsements, and coverage notices
- Expert inspection reports identifying damage, cause, and repair requirements
- Claim communication history, including emails, letters, and recorded statements
Property Damage Documentation
Property damage documentation provides essential evidence in a West Palm Beach property claim dispute, establishing the nature, extent, and timing of the alleged loss. Photographs and videos should capture each affected area from multiple angles, including close views of damaged materials and wider images showing location and context. Dated inspection notes can show when you discovered the conditions, how they progressed, and whether you made temporary repairs. Receipts, contractor invoices, measurement records, and itemized repair proposals may help demonstrate reasonable restoration costs. Evidence preservation steps include retaining original files, avoiding unnecessary alterations, and keeping damaged materials when safe and practical.
Disputed estimate reviews may compare scope, quantities, labor assumptions, and omitted damage through objective documentation. Organized records can assist professionals seeking a fair, efficient resolution for affected property owners.
Insurance Policy Records
Insurance policy records establish the contractual framework for evaluating a West Palm Beach property claim dispute, including coverage provisions, exclusions, deductibles, limits, endorsements, and applicable deadlines. A complete policy file may include declarations pages, renewal notices, amendments, insurer correspondence, and applicable forms. Reviewing these records helps determine whether the carrier applied policy language consistently and whether the policyholder satisfied notice, proof-of-loss, or cooperation requirements. Policyholder rights may depend on identifying controlling provisions rather than relying on summaries or verbal explanations. Organized records also support targeted document requests for claim notes, payment calculations, reservation-of-rights letters, and coverage decisions.
Counsel serving affected property owners can compare those materials with the governing contract, identify unexplained inconsistencies, and preserve significant issues for negotiation or formal proceedings. Accurate policy records promote informed decisions and fair claim resolution.
Expert Inspection Reports
When the cause, scope, or value of alleged damage is disputed, expert inspection reports can provide an objective foundation for evaluating a West Palm Beach property claim dispute. A qualified professional may document structural conditions, moisture intrusion, roof damage, electrical concerns, or other covered losses through photographs, measurements, testing, and methodical observations. Such evidence can distinguish sudden damage from deferred maintenance and identify Hidden mold risks that may not be visible during an initial review. A detailed report may also address repair methods, necessary mitigation, and estimate accuracy, helping determine whether proposed costs reasonably reflect the property’s condition.
Independent findings can help claimants, insurers, and attorneys evaluate coverage issues and present a clear, fact-based evaluation. Prompt inspection is important because conditions may change or become less observable over time.
Claim Communication History
A complete claim communication history can be crucial evidence in a West Palm Beach property claim dispute, particularly when the parties disagree about notice, coverage, cooperation, or the handling of an alleged process injury. Emails, letters, call logs, texts, and portal messages may show when the Initial claim was submitted, what information was requested, and how promptly each participant responded. These records can clarify policy deadlines, document inspection arrangements, and explain delays or incomplete submissions. They may also preserve settlement offers, counteroffers, and negotiation timing, helping establish whether discussions occurred in good faith. Organized communications allow counsel to compare statements with policy requirements and inspection findings. Preserving complete, dated records can support a fair evaluation, protect procedural rights, and help all parties pursue a responsible resolution.
Long-Term Effects of West Palm Beach Property Claim Disputes & Process Injuries
Long-term property claim disputes can create ongoing financial strain as unpaid benefits, temporary expenses, and related losses accumulate. Delayed repairs may worsen property damage, increase restoration costs, and interfere with safe or normal use of the premises. Prolonged legal stress can further affect decision-making and personal well-being while the dispute remains unresolved.
Ongoing Financial Strain
Ongoing financial strain often develops when a property claim dispute delays payment for covered damage or results in an inadequate settlement. Affected property owners may face budget stress as they continue paying premiums, financing costs, temporary living expenses, or obligations connected to an impaired asset. Policy shortfalls can compound the problem when an insurer interprets coverage narrowly, undervalues losses, or excludes costs the owner reasonably expected to be covered. Over time, depleted savings and increased borrowing may affect household stability, business operations, and the ability to support family members or community responsibilities. Careful documentation of financial losses can help clarify the dispute and preserve evidence for review. A qualified property claim lawyer may evaluate policy language, payment records, and insurer conduct while seeking a fair resolution through negotiation or litigation when appropriate.
Delayed Property Repairs
Delayed property repairs can worsen a West Palm Beach property claim dispute by allowing water intrusion, structural deterioration, mold growth, or other damage to worsen before coverage is resolved. These conditions may make a home less safe and increase the scope and cost of necessary restoration. Treatment timelines can also be affected when moisture exposure creates health concerns requiring assessment, remediation, or medical attention before occupants can safely return. Contractor delays may restore the problem when professionals cannot begin work until an insurer approves an estimate or issues payment. Detailed photographs, inspection reports, repair estimates, and written communications can help document changing conditions and support timely action. A property claim lawyer may assist affected individuals in pursuing coverage while encouraging reasonable measures to restore further damage during the dispute.
Prolonged Legal Stress
Prolonged legal stress can affect a policyholder’s health, finances, and ability to manage restoration after a West Palm Beach property claim dispute. Months of unresolved correspondence, inspections, and uncertainty may contribute to sleep problems, reduced concentration, and mental burnout. Insurance anxiety can also interfere with employment, family responsibilities, and decisions about necessary repairs. These effects may worsen when the property remains unsafe or uninhabitable, especially for older adults, caregivers, and households with limited resources. A documented claim file, organized repair records, and timely communication can help mend confusion and preserve important evidence. Legal guidance may provide structure by explaining coverage issues, deadlines, and dispute options.
Supportive professionals should recognize the human consequences of prolonged conflict and help affected policyholders pursue fair resolution without minimizing their ongoing physical or emotional strain.
Proving Liability in West Palm Beach Property Claim Disputes & Process Injury Cases
Proving liability in West Palm Beach property claim disputes and process injury cases requires clear evidence connecting the responsible party’s conduct to the documented loss or injury. Relevant proof may include photographs, repair estimates, inspection reports, medical records, witness statements, contracts, and dated communications. Thorough damage documentation can establish the property’s condition before and after the event, while medical evidence may connect an unsafe process or negligent act to resulting harm.
The claimant generally must identify the applicable duty, show how that duty was breached, and demonstrate that the breach caused measurable damages. In property matters, maintenance records and expert opinions can clarify whether a defect, storm-related condition, or construction error created the loss. In injury matters, incident reports and testimony can establish unsafe procedures or inadequate warnings.
Organized insurer communication should preserve factual accuracy without speculation or admissions. A careful evidentiary record supports fair evaluation, protects affected individuals, and helps counsel present a clear, service-oriented claim for appropriate relief.
Dealing With Insurance Companies After a West Palm Beach Property Claim Disputes & Process Injury
When a West Palm Beach property claim dispute also involves a process-related injury, handle communication with the insurance company carefully and support it with organized evidence. The claimant should report the incident promptly, describe property damage and resulting injuries accurately, and avoid speculation about fault or recovery. Photographs, repair estimates, medical records, witness information, correspondence, and policy documents can help establish a consistent account.
An Independent coverage review may clarify exclusions, notice requirements, valuation provisions, and policy-imposed responsibilities. Claimants should preserve all insurer communications, meet stated deadlines, and request explanations for delays, reservations of rights, or reduced offers. A written response should identify factual errors without making unnecessary admissions.
When conduct suggests mishandling, an attorney may evaluate policy breach remedies, including demands for correction, statutory options, or litigation. Professional communication remains important because careful documentation protects the claimant’s interests while supporting fair treatment of affected property owners, tenants, employees, and families throughout the dispute.
What to Expect During a West Palm Beach Property Claim Dispute & Process Injury Claim Process
The claim process generally begins with filing a property claim and providing thorough documentation of damage, repairs, and related losses. Claimants should expect communications with insurers, evidence review, and negotiations concerning coverage and payment. If disputes remain unresolved, options may include further negotiation, appraisal, mediation, or litigation.
Filing Your Property Claim
Filing a property claim begins with promptly notifying the insurer and documenting the damage through photographs, repair estimates, inspection reports, and records of related expenses. The policyholder should review coverage terms, deadlines, deductibles, and notice requirements before submitting the claim. A complete application generally identifies the property, date and cause of the loss, affected interests, and requested benefits. Damage estimates and contractor quotes can help establish anticipated repair costs, although the insurer may require its own inspection or additional information. Claimants should retain copies of all submissions and communicate with adjusters in writing when practical. If coverage questions, delays, or partial payments arise, a property-claim attorney may evaluate the policy, clarify available remedies, and help protect the claimant’s interests while promoting a fair resolution for all affected parties.
Documenting Damage and Losses
Through systematic documentation, a policyholder can establish the extent of property damage and support the value of the claimed losses. Photographs and videos should capture affected rooms, structural components, personal belongings, and conditions before cleanup or repairs begin. A written inventory can identify each damaged item, its purchase date, approximate value, and replacement cost, while receipts, warranties, and maintenance records may provide additional support. Contractors’ estimates should describe necessary work, materials, labor, and observed causes without overstating conclusions. Mold detection may be appropriate when moisture intrusion creates concealed health or structural concerns. In intricate cases, building code analysis can clarify whether repairs must satisfy current safety requirements.
Preserving damaged materials, obtaining inspection reports, and maintaining a dated communications file can help provide a reliable record for claim evaluation and future review.
Negotiating With Insurers
When an insurer evaluates a West Palm Beach property claim, negotiations typically begin after the policyholder submits supporting documentation and an adjuster investigates the reported damage. The insurer may request estimates, photographs, receipts, repair invoices, and additional statements to assess coverage and valuation. Careful record collection helps present a consistent account of the loss and supports informed communication with the adjuster. Policyholders should review proposed calculations, identify omissions, and provide factual explanations when the insurer’s assessment differs from documented expenses. Communications should remain organized, courteous, and directed toward clarifying policy provisions, deductibles, depreciation, and payment timing.
A claim denial may result from exclusions, insufficient proof, missed deadlines, or disagreements about causation. Understanding the insurer’s stated position helps the policyholder evaluate the available information and prepare an appropriate response.
Resolving Disputed Claims
Resolving a disputed property claim generally begins with a careful review of the insurer’s written position, the applicable policy provisions, and the documentation supporting the claimed loss. The process may require comparing estimates, photographs, receipts, engineering findings, and communication records to identify factual or coverage disagreements. A root cause analysis can clarify whether damage resulted from a covered event, excluded condition, or delayed reporting. Counsel may request additional investigation, submit supporting evidence, and address deficiencies in the insurer’s evaluation. Effective negotiation strategy tips include presenting organized documentation, separating undisputed amounts from contested issues, and responding directly to each stated reason for denial or limitation.
If negotiations fail, mediation, appraisal, or litigation may follow, depending on policy language and Florida procedures. Throughout the process, careful communication and timely action help protect the policyholder’s interests.
Don’t Wait. Call Our Florida Personal Injury Lawyers Now!
Compensation for West Palm Beach Property Claim Disputes & Process Injury Damages
Property claim disputes in West Palm Beach may entitle policyholders to compensation for covered damage, delayed payments, improper claim denials, or other insurer misconduct. Available recovery depends on the policy, evidence, and conduct involved in the dispute. A successful claim may address reasonable repair or replacement costs, emergency mitigation, personal property losses, and necessary services required to protect the premises from further harm. In appropriate circumstances, policyholders may also seek rent reimbursement when covered damage makes a residence temporarily uninhabitable. Additional remedies may apply when an insurer fails to investigate promptly, undervalues documented losses, or violates statutory obligations governing claim handling.
Emotional distress can arise from prolonged displacement, uncertainty, and repeated efforts to obtain benefits, although compensation for such harm may require specific supporting facts and legal authority. Prompt documentation, professional estimates, correspondence, photographs, receipts, and records of insurer communications can help clarify the requested recovery. A qualified attorney can evaluate coverage, preserve evidence, and pursue fair treatment for affected policyholders and families.
Economic vs Non-Economic Damages in West Palm Beach Property Claim Disputes & Process Cases
Economic property losses may include repair costs, replacement expenses, lost rental income, and other measurable financial harm. Non-economic property damages can reflect diminished use, inconvenience, or loss of enjoyment, although their availability and valuation may depend on applicable law and the claim’s circumstances. Calculating claim compensation requires reviewing supporting documentation, policy terms, causation, and both recoverable economic and non-economic losses.
Economic Property Losses
When a covered event damages a residence or commercial property, the resulting economic losses generally form the central measure of an insurance claim. These losses may include property repair costs, replacement materials, contractor labor, debris removal, temporary protection, and necessary professional assessments. If water intrusion creates a health or structural concern, mold remediation may become a compensable expense when the policy covers the underlying cause and the work is reasonable and properly documented. A thorough claim ordinarily connects each expense to the covered damage, distinguishes completed work from estimates, and preserves invoices, photographs, inspection findings, and payment records. Policy limits, deductibles, exclusions, depreciation provisions, and repair timelines can affect recovery. Careful documentation helps policyholders and their representatives present accurate claims and address valuation disputes with the insurer.
Non-Economic Property Damages
Although insurance claims primarily address measurable repair and replacement costs, some property disputes involve losses that are difficult to assign a dollar value. Non-economic property damages may involve emotional distress, loss of comfort, disruption of household routines, or diminished enjoyment of a home after covered damage. These effects can be especially significant when residents face displacement, uncertainty, or prolonged repair delays. In West Palm Beach disputes, whether these damages are recoverable often depends on the policy language, applicable Florida law, and the facts linking the insurer’s conduct to the claimed harm. Documentation describing living conditions, communications, and daily disruptions may help clarify the human impact. Legal professionals serving affected policyholders can explain whether these losses are recognized and how they relate to alleged claim-handling violations, without overstating potential recovery.
Calculating Claim Compensation
Calculating compensation in a West Palm Beach property claim dispute requires separating documented economic losses from any non-economic harm recognized under the policy or applicable Florida law. Economic damages may include dwelling repairs, personal-property replacement, temporary housing, debris removal, and related expenses. Accurate estimating repair costs requires qualified contractors, photographs, invoices, building records, and consideration of code-upgrade requirements. If the loss disrupts a business or employment, examining lost wages involves payroll records, tax documents, schedules, and evidence connecting the interruption to the covered damage. Non-economic damages are generally limited in property insurance matters and may depend on policy language, statutory remedies, or associated personal-injury claims.
A careful review also accounts for deductibles, depreciation, limits, exclusions, and prior payments. Clear documentation supports fair resolution and helps protect resources intended for recovery.
When a West Palm Beach Property Claim Dispute & Process Injury Case Goes to Trial vs Settlement
The decision to resolve a West Palm Beach property claim dispute through settlement or trial depends on the strength of the evidence, the extent of the damage, the insurer’s position, and the risks associated with continued litigation. Settlement may provide a faster, more predictable resolution, allowing a policyholder to repair property, restore stability, and avoid the expense and uncertainty of courtroom proceedings. Negotiations should address documented losses, claim-denial reasons, coverage interpretations, and any bad-faith investigations that may have affected the insurer’s handling.
Trial may become necessary when an insurer refuses a reasonable payment, disputes persuasive evidence, or fails to respect policyholder rights. A judge or jury then evaluates testimony, records, expert opinions, and the parties’ conduct. Counsel can explain the basics of legal strategy, including expected costs, timelines, evidentiary challenges, and potential outcomes. The appropriate path depends on the client’s priorities and the case’s strength. Careful preparation supports informed decisions and promotes fair treatment throughout the process.
Florida Laws That May Affect Your West Palm Beach Property Claim Disputes & Process Case
Florida statutes and insurance regulations may importantly affect how a West Palm Beach property claim dispute is investigated, negotiated, and litigated. Florida law generally requires insurers to acknowledge communications, investigate covered losses, and explain claim decisions in good faith. Policy language, endorsements, deductibles, and statutory duties can determine whether damage qualifies for payment and what evidence supports the claim.
Relevant considerations may include:
- Building-code requirements and ordinance-or-law coverage
- Wind mitigation reports, inspections, and hurricane deductibles
- Prompt communication, documentation, and sworn proof-of-loss requirements
- Unfair claim practices and potential bad-faith exposure
A careful review of the policy and available records can help identify coverage obligations, exclusions, and disputed factual issues. Photographs, repair estimates, maintenance records, weather data, and correspondence may clarify causation and the claim timeline. Counsel serving policyholders and communities can help present information accurately while encouraging fair, efficient resolution. Because statutory requirements and policy provisions interact, individualized legal analysis remains important before accepting payment, signing a release, or pursuing further remedies.
The Statute of Limitations for West Palm Beach Property Claim Disputes & Process Injury Cases
Because statutory deadlines can control whether a court hears a dispute, policyholders must identify the applicable limitation period soon after an insurer denies, underpays, or delays a West Palm Beach property claim. Florida law establishes different Filing deadlines depending on the policy language, loss type, date of damage, and applicable statutory amendments. A policy may also require prompt notice, documentation, examinations, or an appraisal request before litigation begins. Missed notices can complicate coverage disputes, particularly when an insurer argues that delayed reporting impaired its investigation. Separate deadlines may govern breach-of-contract claims, appraisal demands, administrative requirements, and lawsuits involving property-related injuries.
Policy provisions, statutory tolling, fraud, concealment, or the date a claim became reasonably discoverable may affect the controlling period. Because these issues are fact-specific, records should preserve the loss date, communications, estimates, payments, denials, and repair history. Timely attention protects claimants and supports fair resolution for affected families and communities.
How a West Palm Beach Property Claim Disputes & Process Lawyer Can Help You
A West Palm Beach property claim disputes and process lawyer can evaluate coverage, investigate the loss, and identify procedural requirements that may affect recovery. The lawyer can organize evidence and communicate with insurers while protecting the policyholder’s interests.
Key services may include:
- Reviewing exclusions, endorsements, limits, and conditions
- Documenting damage through records, photographs, and qualified evaluations
- Assessing Policy Notice Requirements and proof-of-loss obligations
- Preparing negotiations, appeals, or bad-faith lawsuits when supported by evidence
Counsel can also explain disputed adjustment decisions and distinguish legitimate coverage questions from unreasonable claim handling. By coordinating contractors, engineers, accountants, and other professionals, the lawyer helps develop a reliable presentation of the loss. Clear guidance may reduce administrative errors, preserve relevant documentation, and promote fair treatment for property owners serving families, employees, tenants, or community members. Representation further allows the policyholder to make informed decisions about settlement positions and available remedies without personally managing every technical exchange with the insurer. The lawyer’s work remains focused on accountability, accuracy, and lawful recovery.
When to Contact a West Palm Beach Property Claim Disputes & Process Lawyer
When an insurer delays, underpays, denies, or inadequately investigates a property claim, prompt consultation with a West Palm Beach property claim disputes and process lawyer may help protect the policyholder’s rights. Early guidance can clarify policy obligations, response deadlines, and the claim timeline before procedural errors compromise recovery. A lawyer may also assess whether the insurer’s conduct suggests Bad Faith, including unreasonable delays, incomplete inspections, or unsupported coverage positions.
Contact should occur before signing a release, accepting a reduced payment, or providing recorded statements about disputed damage. Prompt advice can support evidence preservation by organizing photographs, repair estimates, receipts, inspection reports, communications, and expert opinions. It may also help identify additional damage that becomes apparent after the initial loss.
Legal involvement is particularly appropriate when an insurer requests repeated documentation, changes its explanation for denial, or fails to communicate. A lawyer can evaluate available remedies and develop a settlement strategy based on documented losses, policy language, and applicable Florida procedures, while helping the policyholder serve household or organizational needs responsibly.
Why You Need an Experienced West Palm Beach Property Claim Disputes & Process Lawyer
Skilled legal counsel can provide the structured analysis and strategic advocacy needed to address complex property claim disputes in West Palm Beach. A seasoned lawyer helps policyholders understand available protections, preserve crucial evidence, and pursue fair treatment while they focus on protecting their families, employees, tenants, or communities.
Careful claim documentation can establish the property’s condition, covered damage, repair costs, communications, and resulting losses. This record may be particularly important when home repair delays increase expenses or create health and safety concerns. A lawyer can also conduct a thorough policy language review, identifying coverage provisions, exclusions, deadlines, and insurer obligations that may affect the claim.
When an insurer undervalues, delays, or improperly denies a valid loss, counsel can assess whether insurance bad faith or other actionable conduct may be involved. Through organized negotiation, formal demands, or litigation when appropriate, experienced representation promotes accountability and helps claimants access the resources needed to restore affected property and support those who depend on it.
How to Choose the Right West Palm Beach Property Claim Disputes & Process Lawyer for Your Case
Selecting the right West Palm Beach property claim disputes and process lawyer requires careful consideration of the attorney’s experience, resources, and approach to insurance matters. A qualified lawyer should understand Florida property insurance requirements, investigate losses thoroughly, and communicate clearly about available options. Reviewing experience with similar claims can help determine whether counsel is prepared to address denied, delayed, or undervalued benefits.
Potential clients should ask how the lawyer evaluates coverage, documents damage, and handles negotiations or litigation when necessary. Policy deadline checks are critical because notice requirements, proof-of-loss obligations, and lawsuit limitations can affect a claim’s viability. The lawyer should also recognize signs of insurer bad faith, including unreasonable delays, inadequate investigations, or unsupported claim denials.
A suitable attorney provides realistic assessments rather than guarantees, explains fees in writing, and identifies the evidence needed to support recovery. Professionalism, responsiveness, and a commitment to protecting policyholders can indicate whether the lawyer is equipped to serve the client’s interests throughout the dispute process. Clear guidance helps affected property owners make informed decisions.
About The Law Offices of Anidjar & Levine
The Law Offices of Anidjar & Levine represents policyholders in West Palm Beach property claim disputes involving denied, delayed, or undervalued insurance benefits. The firm assists homeowners, condominium associations, and business owners seeking fair treatment after property damage. Its attorneys examine policies, evaluate coverage issues, document losses, and communicate with insurers throughout the claim process.
The firm handles disputes involving storm damage, water intrusion, fire, mold, and other covered events. Its experience includes public adjuster disputes, particularly when disagreements arise concerning estimates, documentation, or the scope of claimed repairs. Attorneys may also review roof replacement coverage and assess whether policy language, exclusions, or causation findings affect a claim.
A client-focused approach emphasizes clear explanations, careful preparation, and responsive communication. By helping policyholders understand available remedies, the firm supports informed decisions during demanding circumstances. When negotiations do not resolve a dispute, its legal team can pursue appropriate action to protect the client’s interests and seek benefits permitted under the insurance policy.
Frequently Asked Questions
Can I File a Property Claim if I Am Still Negotiating With My Insurer?
Yes, a policyholder can generally file a property claim while still negotiating with the insurer, provided the policy’s notice requirements and deadlines are satisfied. Filing preserves rights and creates a formal record, while discussions may continue toward a claim settlement. The policyholder should review the insurer timeline, document damage, retain estimates, and communicate in writing. If negotiations stall or payment is inadequate, legal guidance can help evaluate coverage, deadlines, and available remedies.
What Types of Properties Can Be Involved in a Property Claim Dispute?
Property claim disputes can involve many insured assets, including single-family homes, commercial buildings, vacant land improvements, and personal property damaged by covered events. A Condo unit may raise questions involving interior repairs, shared structures, association responsibilities, or loss assessments. A rental property can involve building damage, lost rental income, tenant-related losses, and disputes over policy conditions. Each claim depends on the insurance contract, damage evidence, applicable exclusions, and the parties’ legal responsibilities.
Can a Denied Claim Be Reopened After Receiving New Evidence?
A Denied Claim may sometimes be reopened when New Evidence materially supports coverage, establishes previously unknown damage, or demonstrates an evaluation error. The policyholder should promptly document the evidence, submit a written request, and explain how it relates to the original decision. The Reopening Process depends on policy terms, insurer procedures, and Legal Timelines, which may limit available remedies. Professional guidance can help preserve rights and present the request effectively.
Will Filing a Complaint Affect My Future Insurance Premiums?
Filing a complaint may affect future insurance premiums, but it doesn’t automatically trigger an increase in every case. The policy impact depends on the claim’s nature, frequency, resolution, and the insurer’s underwriting practices. Claim timing can matter, particularly when multiple claims occur within a short period. Insurer retaliation is generally prohibited, although lawful repricing may occur. Policyholders should document communications and consider possible long term effects before pursuing formal remedies.
Can I Pursue Appraisal or Mediation Instead of Filing a Lawsuit?
Yes, a policyholder may pursue appraisal or mediation instead of immediately filing a lawsuit, depending on the policy terms and the nature of the dispute. Appraisal generally addresses the amount of loss, while mediation supports broader settlement options through guided negotiation. A negotiation pause may help clarify documentation, coverage positions, and settlement authority. Because deadlines and procedural requirements vary, professional review can protect the policyholder’s rights while supporting a fair, efficient resolution for all parties.
—————————
Property claim disputes and process-related injuries can create substantial financial, physical, and legal burdens. Understanding your rights, documenting losses, and responding promptly to insurers or responsible parties are essential steps in protecting your claim.
A skilled West Palm Beach Personal Injury Lawyer can evaluate the circumstances, identify available remedies, and pursue fair compensation through negotiation or litigation. The Law Offices of Anidjar and Levine provide knowledgeable guidance and dedicated representation tailored to each client’s needs and objectives.