
The Law Offices of Anidjar and Levine help policyholders pursue insurance benefits after roof or structural damage.
A West Palm Beach Personal Injury Lawyer can review policy provisions, deadlines, exclusions, and notice requirements while organizing photographs, estimates, inspections, invoices, and correspondence.
Qualified contractors or engineers may assess concealed damage, causation, and necessary repairs.
Legal representation can also address denials, undervalued estimates, maintenance disputes, and delayed investigations, helping explain claim documentation, legal rights, and options for pursuing a fair resolution.
Main Takeaways
- A West Palm Beach property claim lawyer can evaluate roof and structural damage coverage under your insurance policy.
- Legal counsel can document storm damage, water intrusion, concealed conditions, causation, and necessary repairs with qualified professionals.
- Lawyers can organize photographs, estimates, invoices, inspection reports, and insurer communications into a strong claim presentation.
- Counsel may challenge denials, undervalued payments, unsupported exclusions, and disputes involving maintenance or causation.
- Prompt evidence preservation, mitigation, inspections, and compliance with notice and proof-of-loss deadlines can protect potential benefits.
How We Can Help With Your West Palm Beach Property Claim Roof & Structural Damage Injury Claim
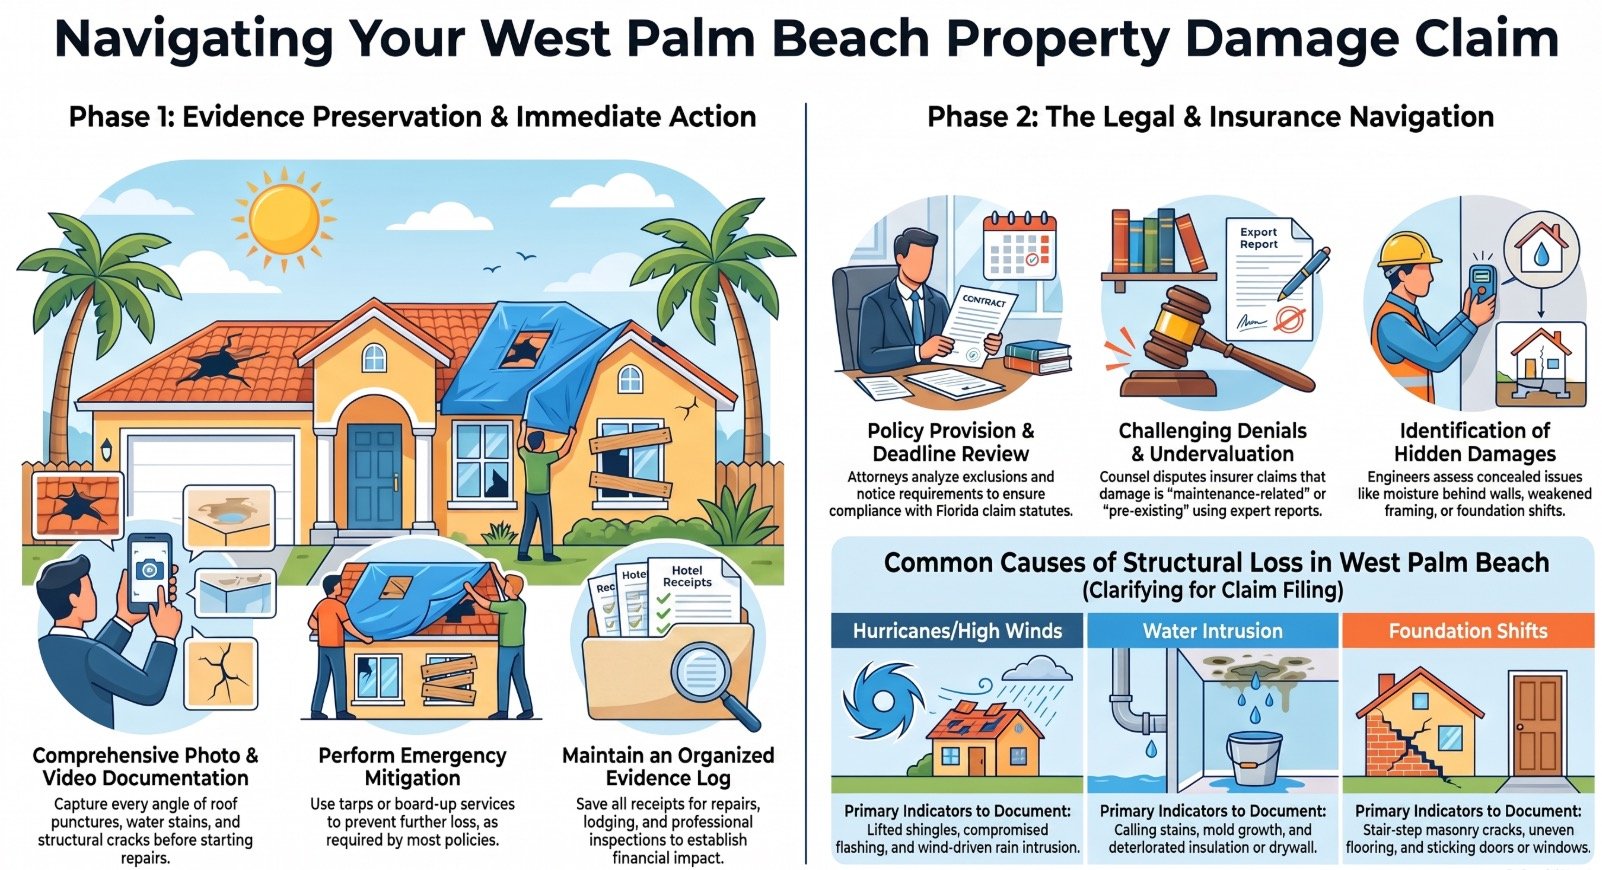
When a West Palm Beach property sustains roof or structural damage, experienced legal counsel can help the policyholder pursue the full benefits available under the insurance policy. Counsel can review the policy, identify applicable coverage, and explain obligations concerning notice, mitigation, proof of loss, and deadlines. A thorough Home inspection may document visible conditions, concealed damage, causation indicators, and necessary repairs. Legal professionals can coordinate with qualified contractors, engineers, and other experts to develop a reliable assessment without overstating the claim.


Counsel can also organize photographs, repair estimates, invoices, correspondence, and insurer documentation into a clear presentation for the carrier. When an insurer requests additional information or questions the scope of damage, counsel can provide measured, evidence-based responses. The objective is to help the policyholder obtain a fair evaluation while preserving resources for restoring a safe, functional property. By handling communications and claim administration, legal representatives allow affected owners to focus on their families, employees, tenants, or community responsibilities.
Understanding West Palm Beach Property Claim Roof & Structural Damage Injury Cases
OUR CONSULTATIONSARE FREE
START YOUR FREE CASE REVIEW
Understanding a West Palm Beach property claim involving roof or structural damage begins with identifying the policy provisions, documented conditions, and events that caused the loss. A careful review determines whether coverage applies, what exclusions may be asserted, and which deadlines govern notice, inspection, and proof of loss.
These cases often depend on organized records rather than assumptions. Evidence preservation strategies may include photographing affected areas, retaining damaged materials when safe, securing repair estimates, and maintaining correspondence with insurers and contractors. Independent inspections can help clarify the scope and significance of observed damage.


Policy claim disputes may arise when an insurer questions causation, limits payment, or characterizes damage as excluded maintenance. A qualified attorney can evaluate the policy language, compare it with documented conditions, and help present a complete claim. Clear communication and accurate records support fair treatment, especially when property owners try to protect occupants, employees, or community members from ongoing hazards while pursuing appropriate recovery.
Common Causes of West Palm Beach Property Claim Roof & Structural Damage
West Palm Beach property claim roof and structural damage commonly results from hurricanes and high winds, which can compromise roofing systems and load-bearing components. Roof leaks, water intrusion, flooding, and storm surge may cause extensive interior deterioration and weaken structural materials. Foundation shifts and cracks represent another significant cause, potentially affecting a property’s stability and raising intricate insurance coverage issues.
Hurricane And Wind Damage
Hurricanes and high winds are leading causes of roof and structural damage in West Palm Beach, where powerful gusts, wind-driven rain, and flying debris can compromise shingles, tiles, flashing, windows, and load-bearing components. Sustained wind pressure may lift roofing materials, weaken connections, or shift structural elements, while airborne objects can create sudden openings and impact damage. Property owners should prioritize hurricane preparedness by securing outdoor items, documenting existing conditions, and arranging qualified inspections after a storm. Photographs, repair estimates, building records, and official weather reports may help establish the extent and cause of covered damage.
Prompt attention also supports insurance claim timing requirements, which can vary by policy and jurisdiction. A property claim lawyer may help affected owners preserve evidence, communicate with insurers, and pursue fair compensation for necessary repairs.
Roof Leaks And Water Intrusion
Roof leaks and water intrusion can cause substantial damage to West Palm Beach properties, particularly when heavy rain enters through failed shingles, cracked tiles, deteriorated flashing, damaged vents, or improperly sealed openings. Moisture may spread beneath roofing materials, weaken decking, stain ceilings, damage insulation, and compromise interior finishes. Delayed detection can increase repair costs because water often travels beyond the visible entry point before symptoms appear. Persistent dampness may also create conditions associated with Mold exposure, which can affect occupants and require expert remediation. Property owners should document affected areas, preserve photographs, obtain qualified inspections, and promptly report losses to insurers.
An experienced property claim lawyer can help evaluate coverage, challenge incomplete assessments, and pursue payment for necessary repairs, including hidden repairs discovered during authorized work.
Flooding And Storm Surge
Flooding and storm surge can cause extensive roof and structural damage when rising water, wind-driven waves, and saturated ground affect a West Palm Beach property. Flood damage may weaken roofing materials, damage interior framing, and destroy electrical, mechanical, and personal property systems. Storm surge can force contaminated water through doors, windows, and other openings, leaving moisture in concealed spaces that require prompt professional evaluation. Delayed drying increases the likelihood of mold growth, odors, and additional deterioration, potentially complicating a property claim. Property owners should prioritize safety, document visible conditions with photographs and videos, preserve damaged materials when practical, and retain receipts for emergency services.
Detailed insurance documentation, including repair estimates, mitigation records, and correspondence, can help establish the scope and timing of covered losses for the benefit of affected occupants.
Foundation Shifts And Cracks
When soil movement, drainage problems, or construction-related defects affect a West Palm Beach property, foundation shifts and cracks can stress connected walls, floors, and roofing components. Soil Settlement can occur when underlying materials compress unevenly, particularly after construction or changes in moisture levels. Drainage Issues may saturate supporting soil, cause erosion, or create pressure against foundation walls. Visible indicators can include stair-step masonry cracks, uneven flooring, sticking doors, separated trim, and roofline distortions. Because these conditions can worsen gradually, property owners may benefit from promptly documenting damage, maintenance history, weather events, and any professional evaluations.
A qualified property claim lawyer can help assess whether covered causes contributed to the loss, identify potentially disputed repairs, and support fair treatment for owners seeking to protect occupants and preserve their homes.
Legal Rights of West Palm Beach Property Claim Roof & Structural Damage Injury Victims
Property owners in West Palm Beach whose buildings sustain roof or structural damage may have legal rights to pursue insurance benefits, repair costs, and other losses covered by their policies. Policy language, deadlines, exclusions, and proof requirements can determine what’s available. A careful review may help affected owners protect occupants, stabilize premises, and serve tenants or families responsibly.
Potential rights may include:
- Requesting a prompt, fair claim investigation
- Obtaining written explanations for denials or partial payments
- Challenging undervalued estimates and unsupported exclusions
- Hiring qualified professionals to document covered damage
- Pursuing appraisal, mediation, or litigation when appropriate
Owners should avoid relying solely on verbal statements and should preserve photographs, inspection reports, invoices, communications, and damaged materials. These evidence preservation steps can strengthen the claim. Awareness of Insurance adjuster tactics, including rushed settlements or narrow damage assessments, may also help owners respond carefully. Legal counsel can evaluate policy obligations, applicable Florida law, and the best path to fair benefits while coordinating with contractors and safety professionals.
Why Do West Palm Beach Property Claim Roof & Structural Damage Injuries Happen?
Roof and structural damage injuries in West Palm Beach often arise from a combination of severe weather, construction defects, deferred maintenance, and inadequate repairs. Hurricanes, tropical storms, wind-driven rain, and flooding can weaken roofing systems, ceilings, walls, and foundations. Falling materials, water intrusion, mold growth, and unstable structures may then create hazardous conditions for residents, visitors, and workers.
Defective design or installation can leave flashing, supports, or drainage systems unable to withstand ordinary exposure. Property owners may also postpone inspections or rely on unqualified contractors, allowing minor deterioration to become a significant safety threat. In some cases, insurers, contractors, or maintenance providers dispute responsibility, complicating recovery for affected individuals.
Insurance claim timelines may affect how quickly damage is evaluated and addressed, while homeowner mitigation steps can reduce additional loss when done properly. Understanding these contributing factors helps communities protect vulnerable occupants, preserve safe housing, and support fair treatment for people facing property-related injuries and disruptions.
Don’t Wait. Call Our Florida Personal Injury Lawyers Now!
What Should You Do After a West Palm Beach Property Claim Roof & Structural Damage Injury?
After roof or structural damage, the property owner should document all visible conditions with photographs, videos, repair estimates, and written descriptions. Immediate repairs may be necessary to protect occupants and prevent further damage, but the owner should preserve evidence and retain receipts whenever possible. Consulting a property lawyer can help assess coverage, protect legal rights, and address disputes with the insurer.
Document All Damage
When roof or structural damage occurs, the policyholder should document every visible condition before repairs or debris removal alter the evidence. Photographs should capture the entire property, close views of damaged materials, water stains, ceiling movement, fallen components, and affected personal property. Water photo documentation should include multiple angles, surrounding areas, and dates when available. A written inventory should identify each damaged item, its location, estimated age, and condition before the incident. Keep insurance notices, inspection reports, contractor observations, and weather information in an organized file. If occupants or neighbors observed the event, tenant written statements can record what they saw, when they noticed it, and any resulting changes. Accurate records help representatives evaluate the claim, communicate facts clearly, and protect the interests of everyone relying on the property.
Seek Immediate Repairs
Prompt action can help prevent additional roof and structural damage while preserving the property claim. A qualified contractor should conduct a safety inspection before entering affected areas or beginning work. If openings expose the interior, emergency board-up services can restrict unauthorized access, weather, and debris. Tarp mitigation may provide temporary protection when permanent roof work cannot occur immediately, particularly after severe weather. Water removal and ventilation also help prevent mold by reducing moisture in walls, ceilings, and flooring. Limit repairs to necessary stabilization until you evaluate and document the extent of the damage. Retain receipts, contracts, photographs, and work descriptions, and have contractors identify all affected materials and conditions. Prompt repairs can protect occupants, neighboring property, and the integrity of the damaged structure.
Consult a Property Lawyer
Documented emergency repairs can stabilize a property, but disputes may still arise over coverage, causation, valuation, or the scope of necessary structural work. A property lawyer can review the policy, photographs, contractor estimates, engineering findings, and insurer correspondence to identify missed obligations or unsupported conclusions. Early legal guidance may also help preserve evidence and prevent repairs from being characterized as unauthorized improvements. If the insurer denies the claim, counsel can develop a Claim denial appeal supported by policy language, repair records, and qualified professional opinions.
When coverage is available, a lawyer can present a settlement negotiation strategy that accounts for replacement costs, code upgrades, additional living expenses, and related losses. Seeking counsel enables property owners to pursue fair treatment while coordinating responsibly with contractors, occupants, and community members affected by the damage and repair process.
Critical Evidence in a West Palm Beach Property Claim Roof & Structural Damage Injury Case
Critical evidence can establish the cause, scope, and financial impact of roof and structural damage in a West Palm Beach property claim involving injury. A careful record should connect property conditions with reported harm, repair needs, and applicable insurance coverage.
Key materials may include:
- Photographs and videos documenting roof damage, water intrusion, and related conditions
- Records showing structural defects, code violations, or maintenance concerns
- Independent expert inspection reports identifying causation and necessary repairs
- Injury records, medical evaluations, treatment bills, and related documentation
- Insurance policies, claim correspondence, estimates, and communications with adjusters
Roof Damage Documentation
When a roof sustains damage, thorough documentation provides essential evidence of the property’s condition and the scope of the resulting loss. Photo evidence should capture affected areas from multiple angles, including close views of missing materials, punctures, water stains, and debris. Images taken promptly, with date information preserved, can help demonstrate when conditions appeared and how they progressed. Keeping a damage log provides a consistent written record of observations, reported incidents, weather events, temporary measures, and communications with insurers or contractors. Records should identify dates, locations, descriptions, and related expenses without speculation. Receipts, inspection reports, repair estimates, and maintenance records may further clarify the claim’s financial impact and the roof’s prior condition.
Organized documentation allows a lawyer to evaluate coverage issues and advocate responsibly for the property owner.
Structural Defect Evidence
Evidence of a structural defect should establish the location, nature, and progression of the condition affecting the property. A detailed Photo timeline can connect visible changes to specific dates, weather events, repairs, or reported incidents. Images should show cracks, shifting walls, uneven floors, water intrusion, damaged framing, and related conditions from multiple angles, while preserving original files and identifying each location. Maintenance records, contractor communications, invoices, and warranty materials may help demonstrate notice, causation, and the property’s condition before and after the damage. Statements from occupants, contractors, or neighboring witnesses can provide additional context regarding sounds, movement, leaks, or recurring problems.
When disputed issues require expert knowledge, expert testimony may explain how observed conditions relate to structural failure and the claimed property loss. Clear organization helps decision-makers evaluate responsibility fairly.
Expert Inspection Reports
Expert inspection reports can provide an independent assessment of roof and structural conditions that photographs, records, and witness statements alone may not establish. A qualified engineer or building expert can define the Inspection scope, document visible and concealed damage, and identify conditions affecting safety, habitability, or repair requirements. The report may connect observed deterioration to a weather event, construction defect, maintenance issue, or other potential cause. Establishing a damage timeline helps distinguish recent losses from preexisting conditions and clarifies when each defect likely developed. An evidence checklist can guide collection of photographs, measurements, moisture readings, permits, maintenance records, and related communications.
Detailed findings should be compared with contractor estimates to evaluate whether proposed repairs address the full scope of covered damage. Clear, impartial documentation can help decision-makers serve affected property owners fairly.
Injury and Medical Records
Medical and injury records can document harm caused by roof failures, structural defects, falling materials, water intrusion, unsafe conditions, or displacement during emergency repairs. These records may establish the nature, severity, and duration of injuries while connecting treatment to the property event. Relevant evidence includes emergency room reports, diagnostic imaging, physician opinions, prescriptions, therapy notes, billing records, and disability documentation. A complete medical timeline should identify symptoms, diagnoses, treatment dates, work restrictions, and recovery progress. Photography documentation may show hazardous conditions, visible injuries, damaged belongings, or locations relevant to the incident.
Witness statements can corroborate how the injury occurred, observed symptoms, and changes in the affected person’s abilities. Complete, consistent records help attorneys present an accurate claim and support fair consideration for injured occupants, visitors, and families.
Long-Term Effects of West Palm Beach Property Claim Roof & Structural Damage Injuries
Long-term roof and structural damage can leave a property with ongoing instability, creating safety concerns and complicating repairs or insurance resolution. Occupants may also experience persistent health complications from moisture, mold, debris, or unsafe living conditions. These consequences can impose continuing financial and emotional strain through medical costs, displacement, repair expenses, and uncertainty.
Ongoing Structural Instability
When roof or structural damage remains unresolved, a West Palm Beach property may develop ongoing instability that affects its safety, value, and usability. Shifting framing, weakened supports, and recurring leaks can gradually deteriorate floors, ceilings, and exterior walls. Hidden moisture may remain behind finished surfaces, complicating inspections and increasing repair demands. Property owners may need engineers, contractors, and qualified mold remediation professionals to document conditions and establish an appropriate restoration plan. Delayed action can also create questions about causation, repair scope, and responsibility, particularly during an insurance dispute.
A careful claim record should include photographs, inspection findings, estimates, maintenance records, and communications with the insurer. Legal counsel can help preserve evidence, evaluate coverage, and pursue remedies that support safe, stable housing for affected occupants and responsible property stewardship.
Persistent Health Complications
Persistent exposure to roof leaks, structural debris, damp materials, or mold can contribute to health complications that continue after the initial property damage. Mold exposure may worsen asthma, allergies, sinus conditions, and other respiratory symptoms, particularly among children, older adults, and individuals with existing illnesses. Prolonged contact with contaminated materials can also cause persistent coughing, headaches, skin irritation, or fatigue. Without proper assessment and remediation, affected occupants may experience declining respiratory function or recurring symptoms even after temporarily leaving the property. Medical documentation can help establish when symptoms began, how they progressed, and whether environmental conditions contributed.
Property owners and insurers should treat reported health concerns seriously, arrange qualified inspections, preserve relevant records, and address hazardous conditions promptly to protect occupants and support appropriate care.
Financial And Emotional Strain
Roof and structural damage can create financial and emotional strain that extends well beyond the initial insurance claim. Homeowners may face temporary housing costs, emergency repairs, lost work, and mounting bills while coverage remains unresolved. Insurance claim frustration often intensifies when adjusters dispute estimates, request repeated documentation, or delay decisions without clear explanations. Delayed repairs can allow moisture intrusion, mold growth, and structural deterioration to worsen, increasing eventual restoration expenses and disrupting household stability. These pressures may contribute to anxiety, sleep difficulties, strained relationships, and reduced confidence in the recovery process.
A West Palm Beach property claim lawyer can help organize evidence, evaluate policy obligations, and communicate with insurers on the claimant’s behalf. Timely legal guidance may protect available benefits and support a fair resolution while reducing unnecessary hardship for affected families.
Don’t Wait. Call Our Florida Personal Injury Lawyers Now!
Proving Liability in West Palm Beach Property Claim Roof & Structural Damage Injury Cases
Proving liability in West Palm Beach property claim roof and structural damage injury cases requires clear evidence connecting the responsible party’s conduct or omission to the unsafe condition and resulting losses. Relevant proof may include photographs, inspection reports, repair estimates, construction records, maintenance logs, witness statements, and professional evaluations. These materials can show when damage developed, whether warning signs existed, and who had authority to correct the hazard.
Faulty Construction may establish that design errors, defective materials, or code violations created the dangerous condition. Evidence identifying Negligent Contractors can demonstrate that workers failed to follow approved plans, recognized safety practices, or contractual duties. Property owners, managers, developers, and other responsible entities may also face liability when they knew, or reasonably should have known, about a hazardous roof or structural defect and failed to address it.
A qualified attorney can preserve evidence, consult engineers and building professionals, identify applicable duties, and organize a persuasive claim that supports injured individuals and their families.
Dealing With Insurance Companies After a West Palm Beach Property Claim Roof & Structural Damage Injury
Once liability evidence has been preserved, communications with insurance companies can materially affect the value and outcome of a West Palm Beach property claim involving roof or structural damage and related injuries. Claimants should provide timely notice, describe the incident accurately, and preserve photographs, repair records, medical documentation, and witness information. Statements should remain factual and avoid speculation about fault, causation, or future losses.
An insurer may begin a coverage investigation to determine whether the policy applies, whether exclusions or limitations control, and whether notice requirements were satisfied. Understanding denied claim reasons is critical when an adjuster disputes responsibility, characterizes damage as ordinary wear, or attributes injuries to another cause. A lawyer may review policy language, challenge unsupported conclusions, and communicate without compromising the claimant’s position. Professional, organized correspondence can help protect evidence and clarify disputed issues while treating adjusters respectfully. Individuals serving affected property owners should recognize that premature settlement agreements or recorded statements may restrict later recovery before the claim’s full consequences are understood.
What to Expect During a West Palm Beach Property Claim Roof & Structural Damage Injury Claim Process
The process typically begins with an initial claim assessment to evaluate coverage, losses, and available evidence. Documentation of roof damage and a professional structural inspection help establish the property’s condition and the scope of necessary repairs. Once the claim is supported, settlement negotiations address the insurer’s valuation and the compensation warranted under the policy.
Initial Claim Assessment
During an initial claim assessment, a West Palm Beach property claim roof and structural damage lawyer reviews the circumstances of the loss, the condition of the property, and the available insurance coverage. The lawyer may arrange an Emergency roof assessment when immediate safety concerns or continuing exposure threaten residents, occupants, or crucial operations. This evaluation helps identify urgent stabilization needs without prematurely determining the claim’s full value. Early evidence preservation also becomes important, particularly when weather, construction defects, maintenance issues, or third-party conduct may affect responsibility. The lawyer typically explains policy duties, notice requirements, relevant deadlines, and communications with the insurer.
An initial assessment may also identify potential conflicts between coverage provisions and exclusions. By establishing priorities promptly, counsel can help protect the client’s interests while supporting a fair resolution for affected individuals and communities.
Documenting Roof Damage
Careful documentation establishes a reliable record of roof damage for a West Palm Beach property claim involving structural loss or related injuries. A property owner or designated representative should photograph every affected area from multiple angles, including exterior surfaces, interior stains, fallen materials, and damaged personal property. A Photo timeline can connect conditions to the reported event by recording dates, weather observations, emergency measures, and subsequent changes. Written notes should identify locations, approximate dimensions, visible hazards, and any actions taken to protect occupants or prevent additional loss. Receipts for tarps, temporary repairs, cleanup, and lodging should be preserved with correspondence from insurers and contractors.
Digital files require weatherproof storage through secure cloud backups or protected physical media. This organized record supports accurate communication and helps advocates serve affected individuals responsibly.
Structural Inspection Process
When a roof or structural condition is reported, an insurer may arrange an inspection to evaluate the cause, scope, and severity of the alleged damage. During a Hurricane inspection, an adjuster or engineer may examine roofing materials, flashing, framing, ceilings, walls, foundations, and visible safety concerns. Photographs, measurements, maintenance records, and weather information may be reviewed to distinguish storm-related damage from wear, construction defects, or prior conditions. Moisture testing can identify concealed water intrusion and help trace its path through insulation or structural components. The inspection may also address Structural settlement, including cracks, uneven floors, shifting walls, or foundation movement. A load assessment may determine whether damaged beams, trusses, or supports remain capable of carrying expected weight. A written report should be reviewed carefully for accuracy and completeness.
Settlement Negotiation Steps
Once the insurer has reviewed the inspection findings and supporting documentation, settlement negotiations may begin regarding the value and range of the roof or structural damage claim. The policyholder or representative typically presents repair estimates, photographs, engineering opinions, invoices, and evidence of related losses. Contractor documentation management helps ensure that records remain organized, consistent, and easy to confirm. The parties may exchange written offers, identify contested issues, and request additional inspections or explanations. Careful attention to the Insurance claim deadline can help prevent missed due dates and clarify when responses are required. If negotiations stall, mediation or formal legal action may become necessary.
Throughout the process, a qualified lawyer can evaluate policy language, challenge unsupported exclusions, and pursue a resolution that addresses necessary repairs while serving the property owner’s legitimate interests.
Compensation for West Palm Beach Property Claim Roof & Structural Damage Injury Damages
Compensation for roof and structural damage may include the reasonable cost of repairs, replacement of damaged materials, temporary housing, personal property losses, and related expenses covered under the applicable insurance policy. A careful evaluation can identify Hidden damages, including moisture intrusion, weakened framing, mold, or electrical risks that may not appear during an initial inspection. Documentation should connect each loss to the covered event and distinguish necessary repair costs from upgrades or unrelated maintenance. Policy exclusions, deductibles, limits, and conditions may reduce or restrict payment, making a complete policy review critical. Claim timelines also matter because late notice, missed proof requirements, or delayed mitigation may provide grounds for a coverage dispute.
A qualified representative can help organize photographs, estimates, invoices, inspection findings, and correspondence for a clear submission. When serving policyholders, counsel may also seek prompt payment for reasonable emergency measures and advocate for fair treatment throughout adjustment, appraisal, or litigation. Each claim requires individualized analysis.
Economic vs Non-Economic Damages in West Palm Beach Property Claim Roof & Structural Damage Cases
Economic damages may include roof repairs, structural restoration, temporary housing, debris removal, and related financial losses. Non-economic losses can involve diminished use, inconvenience, disruption, and reduced enjoyment of the property, depending on the claim and applicable law. Establishing damage values generally requires invoices, estimates, photographs, expert assessments, and other reliable documentation.
Economic Damage Categories
When a covered roof or structural loss occurs, the value of a property claim depends on the specific financial harm you can establish, not merely the visible extent of the damage. Economic damages may include reasonable costs required to restore the insured property to its pre-loss condition. Relevant categories can include emergency protection, temporary repairs, debris removal, water mitigation, replacement materials, labor, permits, and professional inspections. Documented roof leak costs may support payment for damaged interiors and necessary remediation. Evidence of foundation settlement can help identify stabilization or engineering expenses when movement affects covered structures. Accurate structural repair estimates provide a basis for evaluating scope and pricing. An Insurance denial response should address exclusions, causation, and valuation with organized records, invoices, photographs, and qualified expert opinions.
Non-Economic Losses
Non-economic losses in West Palm Beach property claim disputes involve harm not measured solely by repair invoices or replacement costs. Roof or structural damage may disrupt a household’s sense of safety, privacy, stability, and normal daily life. Residents can experience anxiety during storms, sleep disruption, loss of enjoyment, or frustration caused by unsafe conditions and prolonged displacement. Although these effects may not appear on financial records, they can materially affect well-being and family relationships. Insurers may dispute whether such harm falls within policy coverage or whether it is sufficiently connected to the covered event. Damage proof may include medical records, personal journals, photographs, and witness statements describing changes in behavior or living conditions. A lawyer can assess available remedies while presenting the claimant’s experience with dignity, accuracy, and respect.
Proving Damage Values
Accurately proving damage values in West Palm Beach roof and structural damage claims requires separating measurable financial losses from documented effects on a claimant’s living conditions and well-being. Economic damages may include repair invoices, engineering evaluations, temporary housing, damaged contents, mitigation expenses, and lost rental income. Photographs, inspection reports, receipts, contractor bids, and maintenance records can connect each expense to the covered event. Non-economic effects, such as displacement, disrupted routines, and diminished habitability, should be described consistently and supported by personal records or witness statements.
Claimants should also review Insurance coverage limits, deductibles, exclusions, and valuation methods before presenting demands. Independent review can identify damage estimate pitfalls, including omitted structural work, improper depreciation, or unsupported assumptions. A carefully organized evidence package helps insurers, adjusters, and courts evaluate the claim fairly and efficiently.
Don’t Wait. Call Our Florida Personal Injury Lawyers Now!
When a West Palm Beach Property Claim Roof & Structural Damage Injury Case Goes to Trial vs Settlement
The decision to take a West Palm Beach property claim involving roof or structural damage to trial rather than settlement depends on the strength of the evidence, the insurer’s position, the extent of the loss, and the parties’ willingness to accept litigation risks. Settlement may provide faster payment, greater predictability, and fewer demands on property owners and their families. It can also support timely repairs and reduce disruption for those responsible for maintaining safe homes or businesses.
Trial may become appropriate when coverage is disputed, damage values remain substantially contested, or settlement offers fail to reflect documented losses. A careful trial timeline can include discovery, expert inspections, depositions, motions, and testimony preparation. Evidence readiness is critical, including photographs, repair records, engineering opinions, estimates, and communications with the insurer. Counsel may evaluate likely costs, delays, and outcomes before recommending either path. The claimant generally makes the final decision, guided by practical needs and the available evidence.
Florida Laws That May Affect Your West Palm Beach Property Claim Roof & Structural Damage Case
When a West Palm Beach property claim involves roof or structural damage, several Florida laws may affect coverage, deadlines, evidence, and the insurer’s obligations. Property insurance statutes address policy interpretation, required notices, claim handling, and duties imposed on carriers and policyholders. Applicable building codes may also affect whether repairs meet safety requirements and whether the damage resulted from a covered event.
Key considerations include:
- Florida claim deadlines governing prompt notice and required supporting documentation.
- Statutory standards addressing insurers’ investigation and communication duties.
- Policy provisions concerning deductibles, exclusions, matching, and mitigation.
- Building-code requirements affecting repair scope, permits, and compliance.
- Rules concerning sworn statements, examinations, estimates, and proof of loss.
A careful review can help property owners and those assisting them identify missing evidence, preserve repair records, and communicate accurately with insurers. Public adjusters, contractors, and legal counsel may each provide distinct support, but their roles should remain coordinated. Because statutory requirements and policy language can change, a qualified professional should evaluate the claim’s specific facts before action is taken. This approach promotes fair treatment and responsible service to affected property owners.
The Statute of Limitations for West Palm Beach Property Claim Roof & Structural Damage Injury Cases
How long a property owner has to pursue a roof or structural damage claim in West Palm Beach depends on the applicable Florida statute, the insurance policy, and the date the loss was discovered or should reasonably have been discovered. Florida law may impose a filing period for property insurance lawsuits, while policy provisions can establish earlier notice requirements and other Insurance claim deadlines. Because deadlines may differ according to the loss date, policy language, and claim type, prompt review is important.
A property owner should report suspected damage according to the policy, document conditions, and preserve evidence. Photographs, inspection reports, repair estimates, weather records, correspondence, and damaged materials may help establish when damage occurred and how it progressed. Delayed notice can create disputes about causation, prejudice, or compliance with policy terms. Missing a statutory or contractual deadline can restrict recovery even when damage appears substantial. Timely attention accordingly supports fair evaluation and protects the interests of owners, occupants, and others affected by unsafe conditions.
How a West Palm Beach Property Claim Roof & Structural Damage Lawyer Can Help You
Prompt legal guidance can help a West Palm Beach property owner address roof or structural damage before notice requirements, policy deadlines, or evidentiary problems impair a claim. A lawyer can serve the owner by organizing a reliable case and communicating with insurers, engineers, contractors, and public agencies.
Prompt legal guidance helps West Palm Beach property owners protect claims, coordinate professionals, and address roof or structural damage responsibly.
- Reviews policy language, exclusions, endorsements, and coverage obligations.
- Documents damage through photographs, repair records, inspections, and expert opinions.
- Evaluates Local ordinance impacts affecting permits, safety standards, and required repairs.
- Calculates covered repair costs, additional living expenses, and related losses.
- Prepares Claim denial appeals supported by policy terms and admissible evidence.
Counsel may also identify inconsistencies in an insurer’s investigation, challenge unsupported causation theories, and seek appropriate payment through negotiation or litigation. Clear explanations help property owners understand available remedies and make informed decisions while preserving resources for repairs and community responsibilities. A lawyer’s involvement can promote fair treatment, careful documentation, and accountable resolution without overstating the claim or compromising critical evidence. This support helps owners protect occupants, maintain safe premises, and respond responsibly to those affected by property damage.
When to Contact a West Palm Beach Property Claim Roof & Structural Damage Lawyer
Early legal consultation can be important when a West Palm Beach property owner discovers roof or structural damage, receives a claim denial, or encounters delays in the insurer’s investigation. Prompt guidance may help the owner understand policy deadlines, notice requirements, and documentation obligations before making statements that could affect coverage. The owner should file a timely claim, even when the full extent of damage remains uncertain, and should preserve evidence through photographs, videos, repair estimates, inspection reports, receipts, and damaged materials when safe. A lawyer may also be contacted after a storm, plumbing failure, fire, or suspected construction defect if damage appears progressive or difficult to attribute.
Early contact is particularly appropriate when an insurer requests an examination, proposes a limited payment, identifies a coverage dispute, or suggests the loss resulted from maintenance issues. Timely legal attention can help protect your options while you coordinate necessary safety measures and serve occupants, tenants, or affected community members responsibly.
Why You Need an Experienced West Palm Beach Property Claim Roof & Structural Damage Lawyer
An experienced West Palm Beach property claim roof and structural damage lawyer can evaluate the policy, investigate the cause and scope of loss, and address disputes with the insurer. This experience is important because roof failures and structural problems may involve multiple causes, intricate exclusions, and substantial repair costs. A lawyer can coordinate qualified inspections, preserve photographs and records, and present evidence supporting a complete claim. Hiring a property attorney also gives the policyholder informed guidance when deadlines, proof requirements, or competing estimates affect recovery. Counsel can recognize Insurer communication tactics that may delay evaluation, narrow the claimed damage, or encourage an inadequate settlement.
By managing correspondence and negotiations, the attorney helps reduce confusion and protects the client’s position while treating the affected household’s needs with care. Experienced representation can further identify inconsistencies in adjustment decisions and pursue appropriate remedies when coverage or payment remains disputed, supporting a fair process for those relying on their property insurer after serious loss.
How to Choose the Right West Palm Beach Property Claim Roof & Structural Damage Lawyer for Your Case
Selecting the right West Palm Beach property claim roof and structural damage lawyer requires careful review of the attorney’s experience, investigative resources, and record handling complex insurance disputes. A qualified professional should understand policy language, construction evidence, deadlines, and the methods insurers use to evaluate covered losses. Prospective clients should ask whether the lawyer has managed roof failures, water intrusion, foundation concerns, or related structural claims and can coordinate qualified engineers, contractors, and other specialists when necessary.
Before retaining counsel, individuals should verify license history through the Florida Bar and review disciplinary information, qualifications, and professional standing. They should also request a clear explanation of representation, communication practices, anticipated milestones, and potential conflicts. Clients should evaluate attorney fees, including contingency percentages, litigation costs, expert expenses, and circumstances that could create additional charges. Comparing written agreements helps prevent misunderstandings. A lawyer who communicates clearly, preserves evidence, and diligently advances the client’s interests can better support a fair resolution.
About The Law Offices of Anidjar & Levine
The Law Offices of Anidjar & Levine represents policyholders seeking assistance with roof, water intrusion, and structural damage claims in West Palm Beach. The firm evaluates reported losses, reviews insurance policies, and helps clients understand potential coverage issues affecting their homes and financial stability.
Its attorneys may help document damage, communicate with insurers, and respond to claim delays, denials, or inadequate settlement offers. A thorough Homeowners rights overview can help residents recognize policy obligations, evidence requirements, and available avenues for disputing an insurer’s position. The firm also provides Claim timeline tips, encouraging prompt reporting, organized records, professional inspections, and careful preservation of damaged materials when safe.
Frequently Asked Questions
Does Homeowners Insurance Cover Temporary Living Expenses After Roof Damage?
Homeowners insurance may cover temporary living expenses after roof damage when the home becomes uninhabitable because of a covered peril. Additional living expenses can include temporary housing, meals, transportation, and other necessary costs exceeding normal household spending. Coverage limits, deductibles, exclusions, and proof requirements vary by policy. Policyholders should document damage, preserve receipts, notify the insurer promptly, and request written guidance regarding eligibility and the expected settlement timeline.
Can I Repair My Roof Before the Insurance Adjuster Inspects the Damage?
A homeowner should generally avoid permanent roof repairs before the insurance adjuster inspects the damage, unless immediate action is necessary to prevent further loss. Photographs, videos, damaged-material samples, and documented estimates should be preserved. Interim repairs, such as tarping or covering openings, are usually appropriate when carefully recorded and supported by receipts. Notify the insurer promptly, and whenever possible, hold nonessential repairs until you receive written guidance to protect the claim.
What Happens if My Mortgage Company Is Listed on the Insurance Check?
If a mortgage company is listed on an insurance check, it generally must endorse the payment before funds can be deposited or released. This protects the lender’s interest in the property and may require a formal check endorsement procedure. The borrower should contact the mortgage servicer promptly, provide the insurance estimate and repair documents, and confirm its endorsement requirements. The servicer may release funds in stages as repairs progress and inspections occur.
Can Denied Claims Be Reopened When New Structural Damage Appears?
A denied claim may be reopened when newly discovered damage establishes that the original investigation was incomplete or the loss was misinterpreted. The policyholder should promptly document the structural condition, preserve photographs, obtain qualified inspections, and notify the insurer in writing. Policy deadlines and appraisal or dispute procedures may apply. If coverage remains contested, an experienced professional can evaluate the evidence, communicate with all parties, and help protect the policyholder’s rights.
Are Public Adjusters Different From Property Insurance Claim Lawyers?
Public adjusters and property insurance claim lawyers serve different functions. A public adjuster’s role generally involves documenting damage, estimating repair costs, and negotiating with the insurer on the policyholder’s behalf. A lawyer provides legal advice, interprets policy provisions, addresses claim denials, and may pursue litigation. They can collaborate, but neither replaces the other. An informed policy claim strategy considers the claim’s intricacy, disputed coverage, deadlines, and potential need for court intervention.
—————————
Property owners facing roof or structural damage in West Palm Beach may face complex insurance disputes, costly repairs, and uncertainty about their options. An experienced property claim attorney can review the policy, document damage, respond to insurer delays or denials, and pursue fair compensation. Prompt legal guidance can help protect critical rights and support a stronger claim.
The Law Offices of Anidjar and Levine offer representation tailored to each property damage case. For additional legal assistance, speak with a West Palm Beach Personal Injury Lawyer.

